


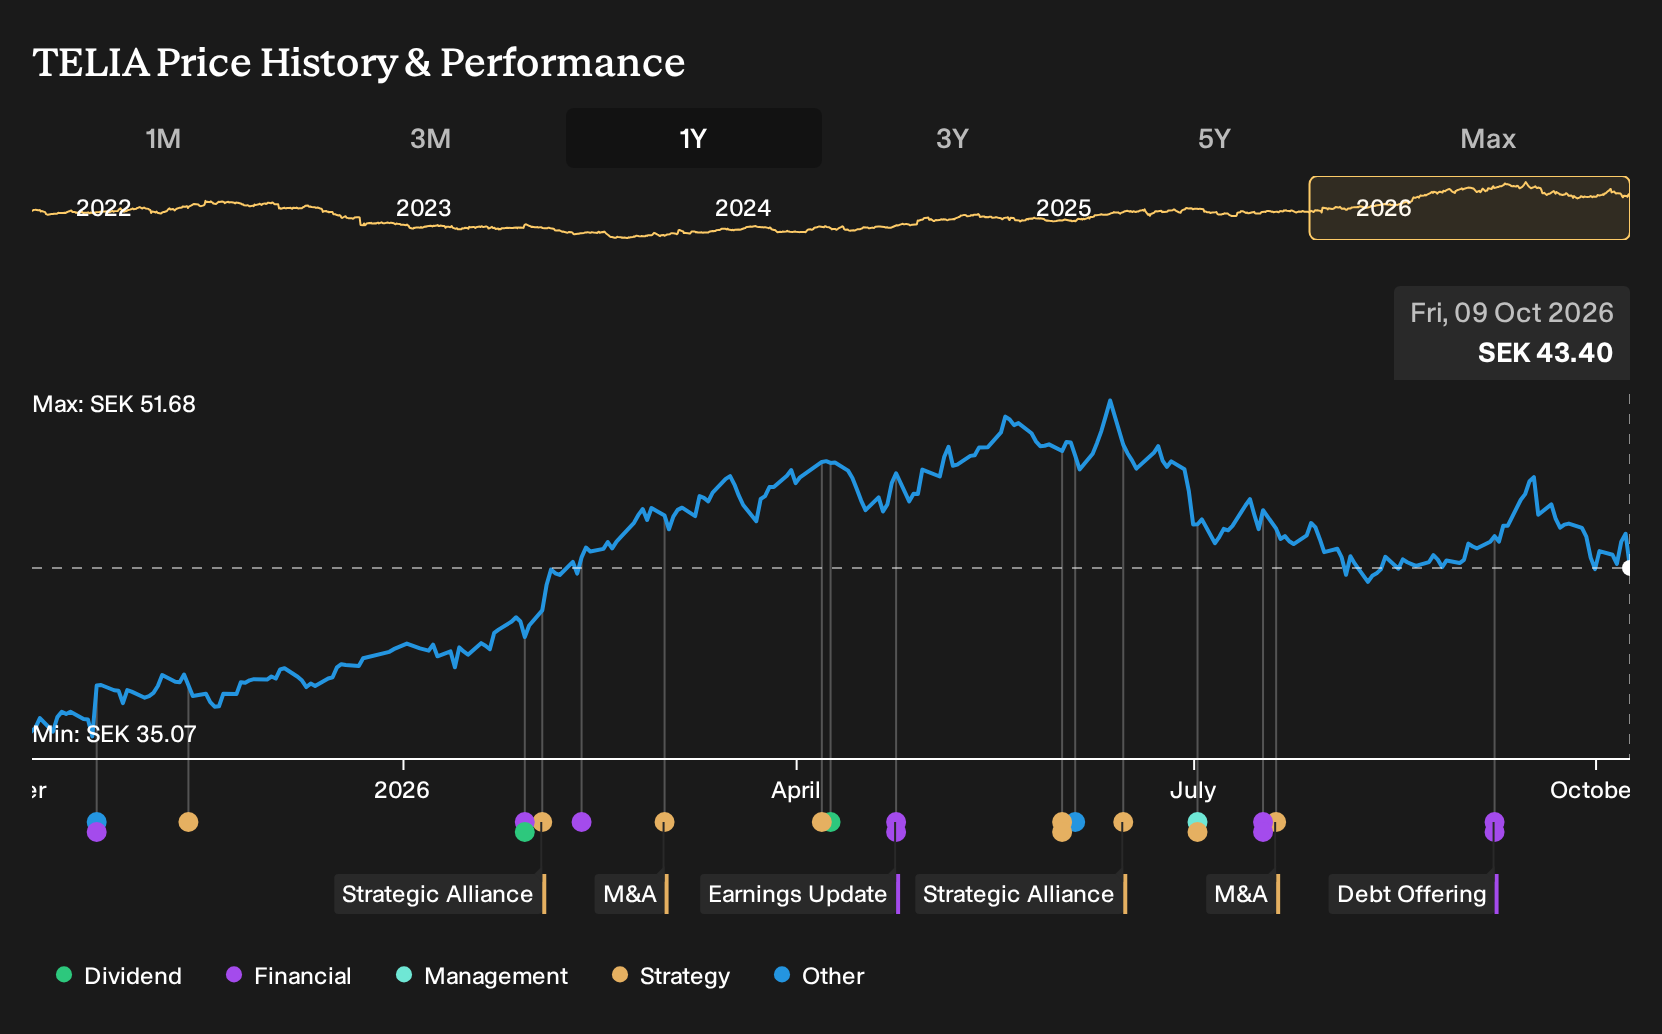
Telia’s year featured a string of concrete moves, from selling its Finnish cloud and IT services arm to CGI to launching Sweden’s first commercial 5G standalone IoT offerings for critical sectors. For Telia shareholders, the return over the past year was 26.5%, including dividends. If you were weighing a purchase back in October 2025, what had to be true about these digital bets and Nordic focus to make that outcome feel reasonable?
The move put Telia in the middle of this trade. Scan 92 AI infrastructure stocks for other companies exposed to it.
The Two Telia Stories Investors Were Arguing About
The shares cost SEK35.5 at the start of the period, and investors were trying to work out whether Telia’s refocused Nordic telecom model could justify a higher price or not.
The bullish narrative pointed to a Fair Value of SEK47, a price level implied by expectations that a streamlined structure, efficiency gains and portfolio simplification could lift net margins and free cash flow as digitalization and 5G services expanded.
The bearish view anchored on a Fair Value of SEK27, built on concerns that structural decline in legacy services and rising energy and regulatory costs could compress margins and leave Telia exposed to slower Nordic and Baltic markets.
What The Telia Evidence Actually Tested
Telia’s Q2 2026 report showed revenue of SEK20,705m and net income of SEK2,230m, both higher than Q2 2025, with net margin rising from 9.9% to 10.8%. That outcome leaned toward the bullish view that efficiency and portfolio simplification could support healthier profitability, even though it did not address longer term worries about legacy decline or energy costs.
The useful takeaway is simple. When a telecom pitch leans on margin improvement, track net margin and absolute profit in later filings to see whether cost cuts and network investments are actually turning into sturdier earnings.
What Telia’s 26% Run Leaves You Paying For Now
With Telia at SEK43.4 after a 26.5% gain over the past year, this Narrative’s Fair Value estimate sits above the current price and leans heavily on quality of earnings and the potential of sovereign AI projects.
The Narrative argues today’s price still does not credit a structural reset in Telia’s cost base and earnings mix from its simplified Nordic and Baltic focus.
"Analysts broadly agree on cost program benefits for EBITDA, but the positive surprises already seen, such as exceptional reductions in group OpEx, new efficiency tailwinds from the reorganization, and ongoing benchmarking, point to a sustainable, structural reduction in fixed costs well beyond expectations, positioning free cash flow and net margins for even greater upward revisions as digitalization accelerates."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
One Step Beyond Telia
Look past Telia for a moment and consider what its customers actually need. Reliable connectivity is only half the story.
Those same households and businesses also want faster home broadband and dependable office circuits. Many prefer a single provider handling both services with fewer billing surprises.
Another large telecom operator is leaning into that problem. It links wireless access with fiber style broadband and pares back legacy activities that drain cash.
The plan relies on AI tools to personalize offers and predict churn. If that approach gains traction, your checklist for telecom opportunities may need updating.
That argument has a Narrative and a number behind it. → See the company one Narrative values 29% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com