


- United Rentals scheduled its third quarter 2026 earnings release for October 21, 2026, with management hosting a conference call on October 22 to discuss the results and operating trends across its General Rentals and Specialty segments.
- The focus on Specialty offerings such as trench safety and HVAC, alongside equipment sales and service, keeps attention on how well United Rentals is monetising its broad fleet and service platform as demand for large projects and industrial work continues to shape its rental mix.
- We will now look at how United Rentals' upcoming third quarter earnings call could influence the existing investment narrative around execution.
Scan how United Rentals’ setup compares with other capital intensive businesses gearing up for earnings season with the hand picked list of solid balance sheet and fundamentals (25 results).
United Rentals Investment Narrative Recap
To own United Rentals, you need to be comfortable with a capital heavy model that leans on large projects, specialty rentals and digital tools to keep equipment earning. The near term hinge is whether that project pipeline and the expanded fleet are busy enough to support high utilization into year end. The biggest near term risk is that any slowdown in big jobs or a mix shift toward lower margin ancillary revenue squeezes profitability further.
The upcoming third quarter 2026 release and call should help you test that thesis. Management commentary on specialty traction, pricing discipline and repositioning costs will matter more than the headline beat or miss. If trends in those areas are broadly in line with recent quarters, the earnings event may not materially change the near term story around execution risk and capital intensity.
The most relevant near term announcement is the timing of United Rentals’ third quarter 2026 results and conference call. This update clarifies when investors will get fresh detail on how the rental fleet, particularly Specialty, is being put to work against the larger CapEx commitments flagged for 2026.
Use that call to listen closely for data points that touch the key catalysts you care about. That includes how large infrastructure and industrial projects are converting into rental demand, whether specialty revenue is tracking toward a higher mix, and how management is thinking about free cash flow, leverage and capital returns given the existing debt load and recent insider selling signals.
What The Current Analyst Setup Implies For United Rentals
United Rentals' analyst consensus ties the medium term story to a handful of concrete markers. Revenue is projected to rise by 10.0% a year over the next three years, profit margins are assumed to lift from 15.7% today to 17.7%, and earnings are expected to move from US$2.6b now to US$4.0b by 2029, with a more cautious camp modeling earnings closer to US$3.5b. Those same forecasts underlie a price target framework that applies a 23.9x P/E multiple to that 2029 profit pool, roughly in line with the multiple cited for United Rentals today and just under the 24.4x level referenced for the US Trade Distributors industry.
United Rentals' narrative projects US$22.4b revenue and US$4.0b earnings by 2029. This setup implies 10.0% yearly revenue growth and an earnings increase of about US$1.4b from the current US$2.6b base.
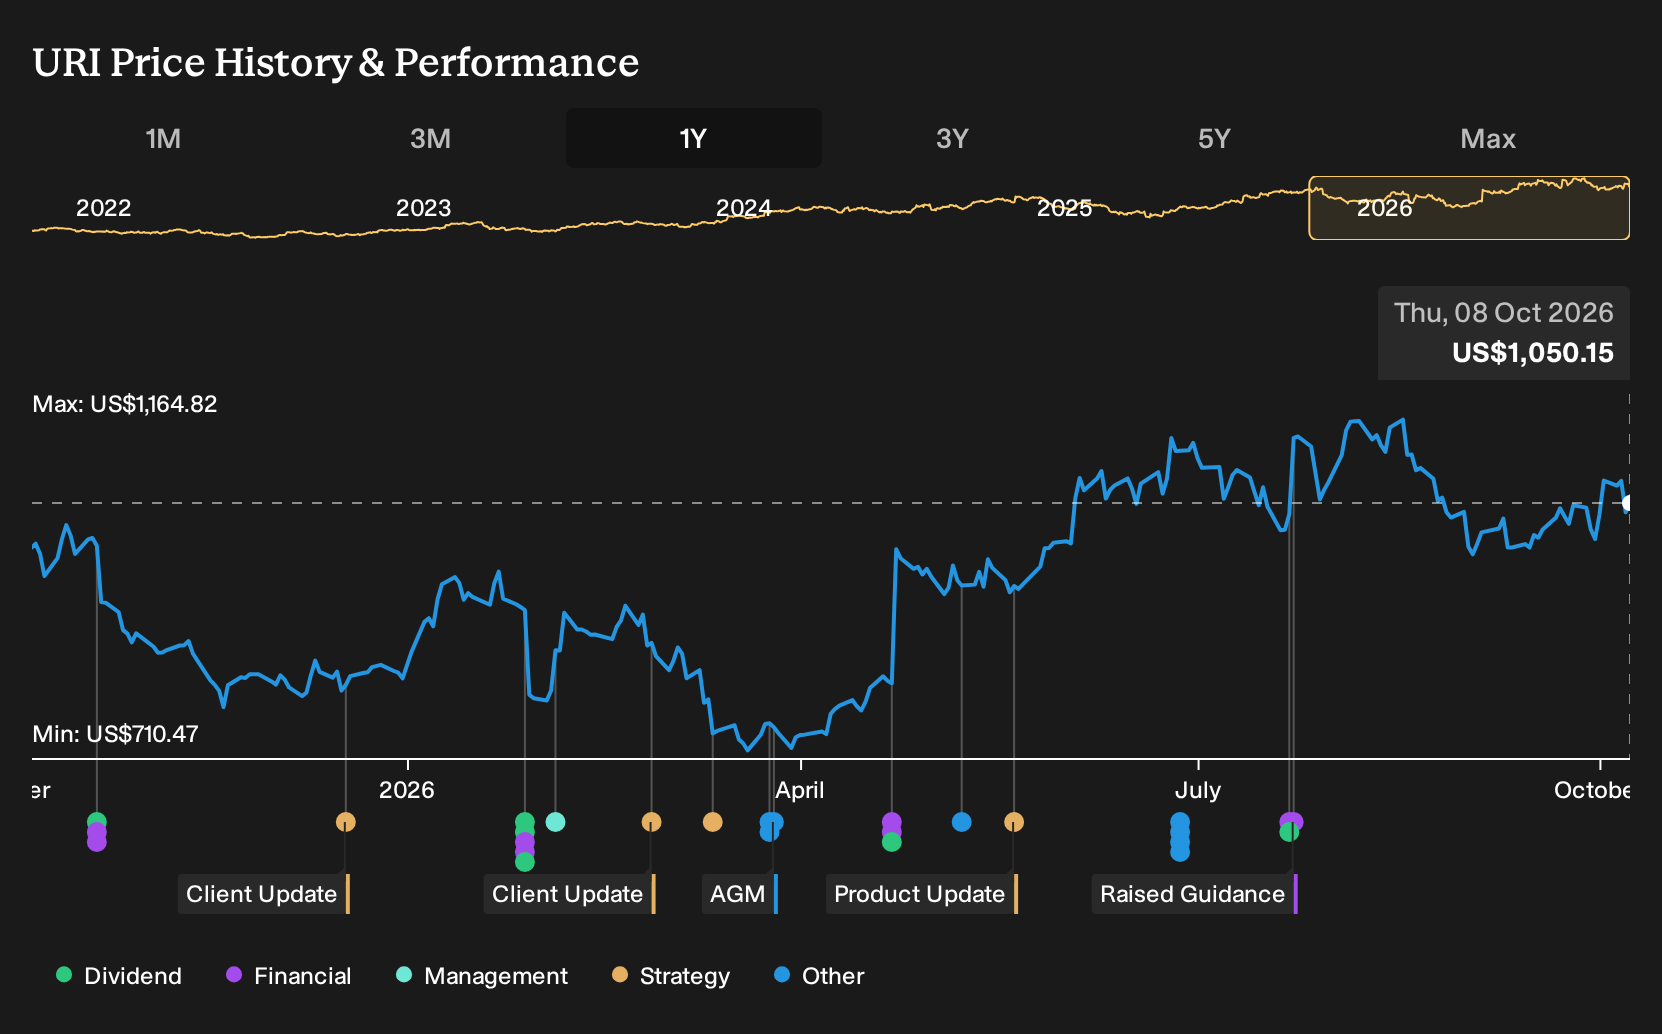
Uncover why United Rentals' fair value indicates a 21% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle on United Rentals focuses on operating leverage. The most optimistic analysts were modeling revenue of about US$23.5b and earnings near US$4.3b by 2029, compared with the US$22.4b and US$4.0b used in the consensus. Those forecasts came before this earnings date news, so treat the call as a chance to see which story appears closer to reality and to weigh several competing viewpoints before you decide what makes sense for you.
Explore 2 other United Rentals fair value estimates, including one that suggests as much as 21% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your United Rentals research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for United Rentals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Rentals' overall financial health at a glance.
Looking For More Investment Ideas Beyond United Rentals?
Once you have a handle on United Rentals, it helps to compare it with a broader set of opportunities so your portfolio is not leaning on a single story or sector. The Simply Wall St screener lets you filter by quality, valuation, income profile and more so you can line up alternatives that match the risk and return characteristics you are aiming for.
- If you want stronger income support from your holdings, start with companies that combine higher yields with resilient fundamentals through the 8 dividend fortresses.
- If capital preservation and steadier business profiles matter most to you, narrow the field to resilient enterprises using the 31 resilient stocks with low risk scores.
- If you are hunting for high quality stocks that the market may not be fully pricing yet, scan the 20 high quality undiscovered gems and see which stories deserve a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com