


ZIM Integrated Shipping Services (NYSE:ZIM) has shaken up expectations by sharply increasing its full-year 2026 profit outlook, tying the new guidance to strong container demand and firmer freight rate trends.
Recent trading reflects that higher guidance. ZIM Integrated Shipping Services’ share price is up 26.24% over the past 90 days and 38.11% year to date, contributing to a 1-year total shareholder return of 145.85% and a very large 3-year total shareholder return of about 7x. This points to strong momentum as investors reassess both earnings potential and deal risk around the proposed Hapag-Lloyd acquisition.
Spot fresh momentum stories beyond ZIM Integrated Shipping Services by scanning hand-picked shipping and transport plays in the 27 high quality undervalued stocks.After a 145% 1 year total return and a takeover offer on the table, ZIM Integrated Shipping Services now presents a simple choice: pay up after the jump, or wait and risk watching it run without you as valuation gets unpacked next.
Most Popular Narrative: 7% Overvalued
The most followed narrative puts ZIM Integrated Shipping Services fair value at $28.30, slightly below the last close of $30.26. That gap frames the stock as pricing in more optimism than the underlying assumptions suggest.
Substantial orderbook-induced industry overcapacity, as highlighted by management's comments on ongoing supply growth, poses a persistent risk to freight rates and load factors, undermining long-term revenue growth assumptions, especially in the absence of strong demand or meaningful scrapping. ZIM's asset-light charter-heavy model, while offering operational flexibility in theory, exposes the company to elevated fixed costs and higher charter expenses in volatile markets. With 250,000 TEUs coming up for renewal, there is downward risk to margins and free cash flow should market conditions worsen, contrary to expectations of stable or expanding profitability.
See why 93 investors see ZIM Integrated Shipping Services as 7% overvalued.
The narrative builds this valuation using a 12.17% discount rate and a view that annual revenue could decline by 2.8% over the next three years, with margins needing to expand toward a 28.6% level to support longer term earnings power. That combination of falling top line, improving profitability and a future P/E of 2.83x on 2029 earnings implies investors are relying on a much lower multiple than both the current 26.3x and the broader US shipping sector ratio of 11.0x.
At today’s share price, the analyst consensus target of $28.30 is about 5% below the market price, which aligns with the narrative’s conclusion that ZIM Integrated Shipping Services is broadly fairly priced with a tilt toward being slightly rich. For readers, the key test is whether assumptions like $5.9b in 2029 revenue and $1.7b in earnings look realistic given exposure to Transpacific trade, ongoing overcapacity and the charter-heavy fleet model.
Result: Fair Value of $28.30 (OVERVALUED)
Still, if ZIM Integrated Shipping Services squeezes more value from its LNG powered fleet and route mix, or its digital tools lift efficiency, those gains could challenge this slightly overvalued call.
Find out about the key risks to this ZIM Integrated Shipping Services narrative.
Another View: ZIM Integrated Shipping Services Through A Cash Flow Lens
Analysts leaning on traditional earnings multiples see ZIM Integrated Shipping Services as richly priced, with a 26.3x P/E versus about 9.8x for US shipping peers and a fair ratio estimate of just 2.8x. Our DCF model tells a very different story, with ZIM trading about 80% below an assessed future cash flow value of $150.55 per share. For an investor, that kind of gap raises a simple question: Is the profit line misleading you more than the cash flow math, or is the model asking you to believe too much about the long haul for this stock?
Look into how the SWS DCF model arrives at its fair value.
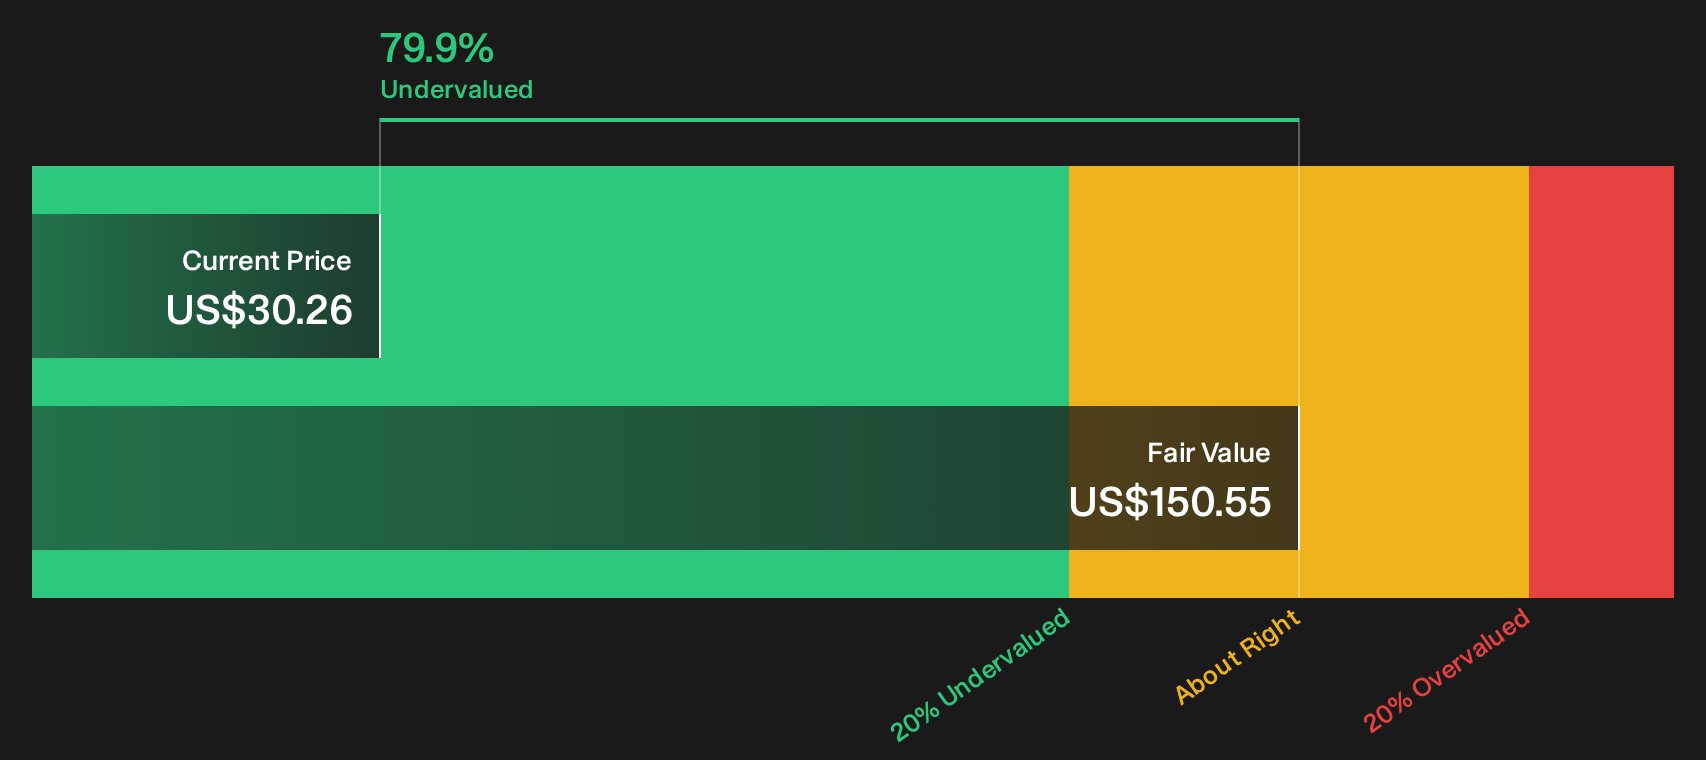
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ZIM Integrated Shipping Services for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The debate around ZIM Integrated Shipping Services is already intense, so do not sit on the sidelines while others set the narrative for you. Weigh both the upside potential and the downside risk signals before you commit fresh capital, and then pressure test your own take against the 1 key reward and 4 important warning signs.
Looking for more investment ideas beyond ZIM Integrated Shipping Services?
If ZIM Integrated Shipping Services has sharpened your focus, do not stop here. Broaden your watchlist with fresh ideas built from clear data and disciplined filters.
- Target resilient opportunities that pair financial strength with lower risk profiles by running the 31 resilient stocks with low risk scores.
- Hunt for potential mispriced quality by scanning the 20 high quality undiscovered gems that combine solid fundamentals with limited market attention.
- Strengthen your income shortlist by checking companies in the 8 dividend fortresses that focus on substantial yields backed by durable cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com