


FuelCell Energy (FCEL) is under pressure after disclosing production shortfalls tied to its Fit Energy agreement, a related US$17.0 million charge, weaker Q3 2026 results, and multiple securities class action lawsuits.
Recent trading shows how sharply sentiment on FuelCell Energy can swing. The share price dropped 6.10% over the last session and is down 18.00% over 90 days, yet it still carries a 111.08% year to date share price return and a 74.54% one year total shareholder return. This suggests earlier enthusiasm has cooled as production issues, the Fit Energy charge, CFO transition and securities class actions reshape how investors view both risk and potential.
Scan beyond FuelCell Energy and compare this setback with other hand-picked clean power and infrastructure stocks by reviewing the 43 power grid technology and infrastructure stocks in the same session.
For FuelCell Energy, after a sharp pullback yet strong year-to-date run, the real tension is simple: step in after this reset or wait for the valuation math to offer a clearer margin of safety.
Most Popular Narrative: 16% Undervalued
The favored narrative on FuelCell Energy pegs fair value at $20.50 against a last close of $17.25, so the debate shifts from survival to how much future execution is already built into that gap.
The partnership with Diversified Energy to deliver up to 360 megawatts to data centers in Virginia, West Virginia, and Kentucky is anticipated to drive significant revenue growth as it positions FuelCell Energy at the forefront of powering AI and high-performance computing sectors.
The joint development agreement with Malaysia Marine and Heavy Engineering to co-develop large-scale hydrogen production systems is expected to enhance revenue by expanding FuelCell Energy's market presence in Asia, New Zealand, and Australia, tapping into growing demand for hydrogen.
See why 53 investors see FuelCell Energy as 16% undervalued.
Result: Fair Value of $20.50 (UNDERVALUED)
Still, the narrative can break if FuelCell Energy continues to report heavy losses, or if execution problems on Fit Energy and data center projects deepen.
Find out about the key risks to this FuelCell Energy narrative.
Another View: FuelCell Energy Looks Expensive On Sales
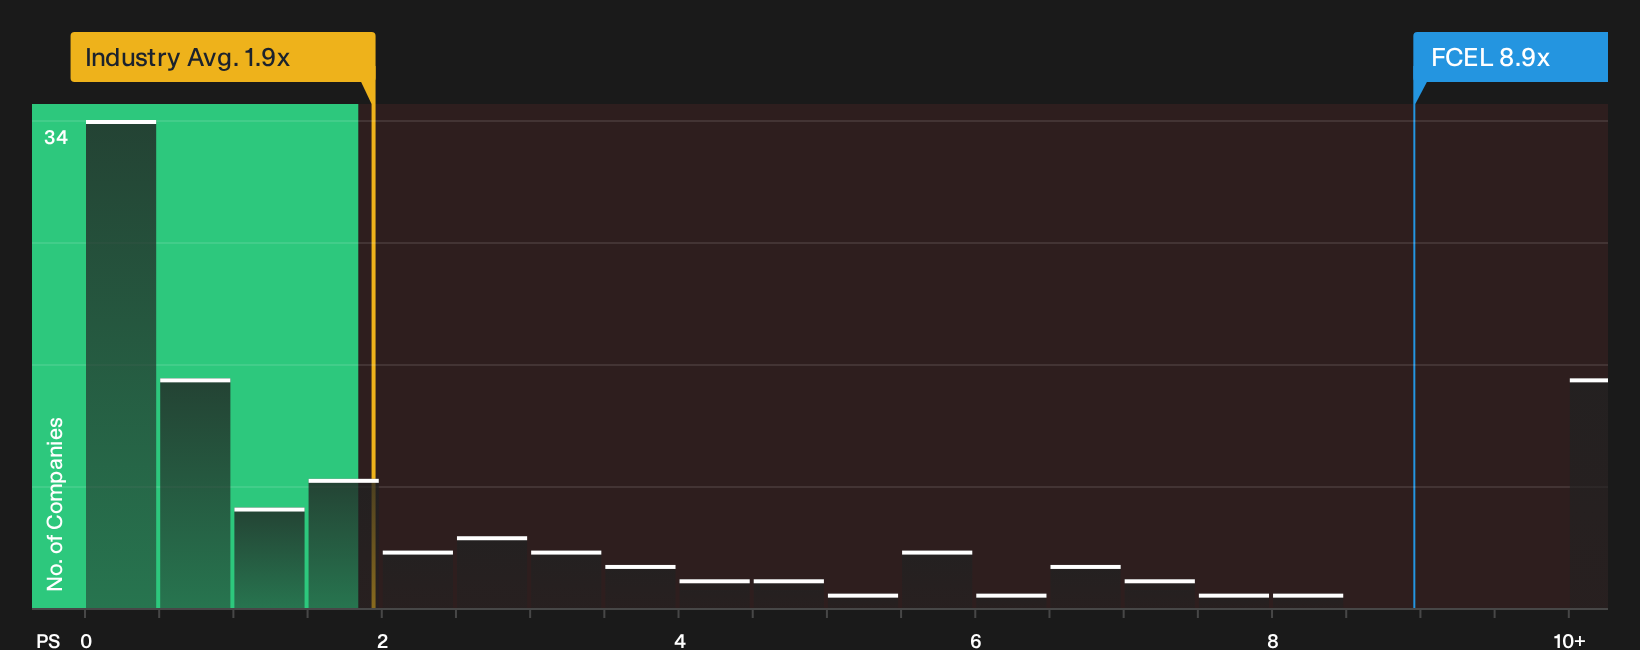
The fair value narrative around FuelCell Energy leans on long term earnings scenarios and analyst targets. A quick check on today’s P/S ratio of 8.9x against the US Electrical industry on 1.9x and a fair ratio of 1.7x paints a very different picture. That kind of gap points to real valuation risk if expectations slip even a little, so which signal do you treat as your anchor?
For a closer look at how this pricing gap shows up in the numbers, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on FuelCell Energy is clearly divided, so move quickly to review the underlying numbers, weigh the trade off between concerns and upside, and focus on the 1 key reward and 3 important warning signs.
Looking for more FuelCell Energy sized ideas?
FuelCell Energy shows how quickly a story can change. Do not stop here. Use fresh watchlists to widen your opportunity set and pressure test your next move.
- Target resilient compounding opportunities by reviewing the 31 resilient stocks with low risk scores before short term headlines crowd out longer term potential.
- Hunt for mispriced quality and see whether any on the 20 high quality undiscovered gems deserve a place alongside or instead of FuelCell Energy.
- Strengthen portfolio foundations by scanning the list of solid balance sheet and fundamentals (25 results) so you are not relying on just one volatile clean energy bet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com