


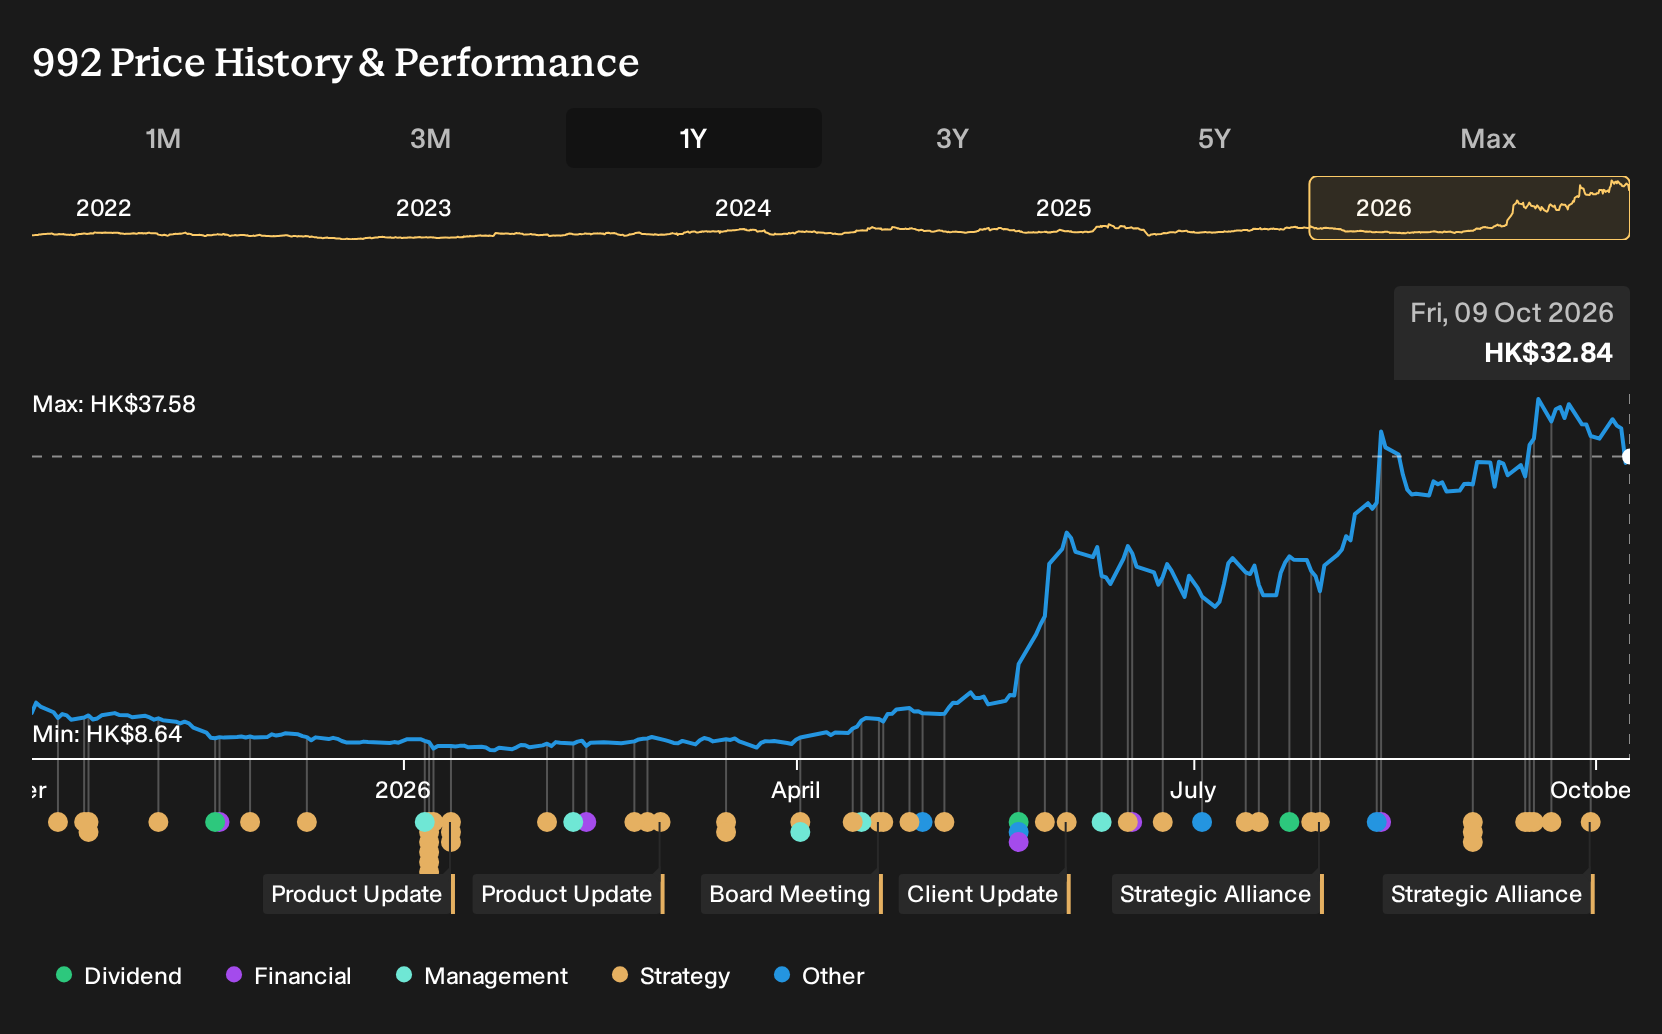
- Lenovo Group has launched Lenovo AI Express with NVIDIA, offering three validated AI configurations that combine hardware options from AMD and Intel with enterprise software and data protection tools to reduce deployment complexity.
- The Lenovo AI Express program positions Lenovo deeper in AI infrastructure workflows by tying hardware, software and lifecycle services into a single, streamlined path to production for customers of different sizes.
- The next area of focus is how Lenovo Group's broader investment narrative could be reshaped by this integrated AI Express deployment model.
Lenovo Group Investment Narrative Recap
To own Lenovo Group you need to be comfortable with a transition story. The business still leans heavily on PCs and devices, yet a lot of energy and capital is now flowing into servers, AI infrastructure and services. Lenovo AI Express fits that shift neatly, since it turns the AI push into a clearer product and services bundle for customers.
The near term swing factor remains how quickly Infrastructure Solutions Group and Solutions and Services Group can scale profitably while net profit margin sits at 0.9%, below last year’s 2.3%. AI Express matters here, but the bigger risk is that heavy AI and data center spend keeps dragging on margins longer than expected.
Lenovo AI Express directly links to a key existing catalyst for Lenovo Group: the push into higher margin, recurring style services such as TruScale and broader solutions offerings. By packaging hardware, NVIDIA software options and lifecycle services, this program appears designed to support that services and infrastructure thesis in a more repeatable way.
The flip side is execution risk inside Infrastructure Solutions Group, which is already carrying operating pressure from AI and R&D investment. If AI Express attracts demand without enough pricing power or utilization, the segment might absorb more cost than benefit in the short run, keeping group profitability and Lenovo’s elevated 65x P/E under scrutiny.
What Lenovo AI Express Implies For The Forecast Story
Lenovo Group's AI Express rollout plugs straight into the numbers analysts are using to frame the next phase. The consensus view assumes revenue grows at 14.4% a year over the next three years while profit margins move from 0.9% today to 4.4% by 2029. That earnings bridge runs from current profit of US$798.0 million to US$6.0b in about three years, with some analysts sitting as low as US$4.8b and others up at US$9.8b.
The jump from earnings today to the US$6.0b consensus is very large, more than 7x current profit, and it rests on the idea that higher margin infrastructure and services scale well. AI Express feeds into that narrative because it gives Lenovo Group a clearer route to sell full AI stacks, not just boxes. It links servers, configuration software and lifecycle support into one commercial conversation, which is the kind of bundle that can make TruScale style recurring contracts easier to land and renew.
That scale up path is already baked into how the stock is framed. To support the current analyst price targets, Lenovo Group would need to generate US$136.6b of revenue and US$6.0b of earnings by 2029 while trading on a P/E of 15.2x, down from 65.4x today and slightly below the wider Hong Kong tech sector on 16.0x. AI Express does not change those headline targets on its own. However, it does give investors a more concrete view of how the Infrastructure Solutions Group and Solutions and Services Group might contribute to that margin uplift if execution lines up with expectations.
Lenovo Group's narrative projects US$136.6b revenue and US$6.0b earnings by 2029. This assumes 14.4% yearly revenue growth and a very large earnings increase from US$798.0 million today to the US$6.0b consensus level.
Uncover why Lenovo Group's fair value indicates a 35% potential upside to its current price before that discount closes.
Exploring Other Perspectives
You can read Lenovo AI Express in a very different light if you focus on margin risk instead of upside. The most bearish analysts saw limited profitability even before this news, with revenue at US$118.4b and earnings of US$5.0b by 2029, plus an 8.4x P/E. That is a much more cautious story. Those estimates were set before this alliance, so treat them as a starting point and explore how your own view might shift as the AI Express impact becomes clearer.
Explore 4 other Lenovo Group fair value estimates, including one that suggests there could be as much as 16% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment decisions rarely come from following the herd, so go with your own analysis.
- A great starting point for your Lenovo Group research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Lenovo Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lenovo Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Lenovo Group?
If Lenovo Group's AI Express story has you thinking more broadly about how to position your portfolio, it can help to scan for other businesses with fundamentals that match your preferences. The Simply Wall St Screener lets you filter for very different types of opportunities in a few clicks, so you can compare Lenovo Group with peers that share similar balance sheet strength, income potential, or valuation traits.
- If you prefer opportunities with stronger downside protection, start with companies flagged as 221 resilient stocks with low risk scores. These may offer more measured exposure to equity markets.
- If stable cash generation and financial resilience matter most to you, search across the list of solid balance sheet and fundamentals (204 results) list to see which businesses pair healthy fundamentals with cleaner balance sheets.
- If you are hunting for ideas that are not yet heavily followed, broaden your watchlist through the 618 high quality undiscovered gems group, which combines quality metrics with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com