


COSCO SHIPPING International (Hong Kong) (SEHK:517) has reshaped its board structure after appointing veteran accountant Cheng Yuk Wo as independent non executive director and audit committee chair, while reallocating several key committee responsibilities.
Recent trading has been strong for COSCO SHIPPING International (Hong Kong), with the share price at HK$7.03 after a 1 day share price return of 3.38% and a 90 day share price return of 29.23%. The 1 year total shareholder return of 33.75% and 5 year total shareholder return of 371.66% point to momentum that investors appear to be reassessing in light of tighter governance signals from the latest board reshuffle.
Compare COSCO SHIPPING International (Hong Kong)'s governance driven momentum with a curated set of transport and infrastructure players by scanning 222 resilient stocks with low risk scores that pair steadier risk profiles with solid fundamentals.
Bulls see COSCO SHIPPING International (Hong Kong) as a governance backed compounding story, while bears point to revenue contraction and past share gains. Which case does the current valuation support next?
Preferred P/E of 13.4x: Is it justified?
COSCO SHIPPING International (Hong Kong) closed at HK$7.03, which leaves the stock trading on a P/E of 13.4x against both its peer group and the wider Asian infrastructure sector. That price tag sits at the higher end of the range suggested by the comparison set, so investors are paying up for each dollar of recent earnings.
The P/E multiple compares the current share price with earnings per share, and it is a common way to benchmark mature, profit generating businesses like COSCO SHIPPING International (Hong Kong). With net profit margins at 19.9% on HK$3,864.06m of revenue and high quality earnings highlighted, the ratio is being applied to a relatively solid profit base rather than a speculative story.
Even so, the market is assigning a richer P/E than both the Asian infrastructure average of 13x and the narrower peer basket at 7.9x. That premium sits awkwardly next to several pressure points, including revenue that declined 2.5% over the last year, net profit margins that eased from 21.2%, and a dividend yield of 7.4% that is flagged as not well covered by earnings or free cash flow.
On top of that, Simply Wall St's DCF work estimates future cash flow value at HK$2.45 per share, which is well below the current HK$7.03 price, and forecasts point to revenue declining around 2.5% a year with return on equity expected to remain in low double digits. Put together, the picture is of a stock that screens as expensive on earnings relative to both its own cash flow valuation and to sector benchmarks.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 13.4x (OVERVALUED)
Still, COSCO SHIPPING International (Hong Kong) faces pressure from revenue that declined 2.5% and a dividend flagged as not well covered, which could challenge sentiment.
Find out about the key risks to this COSCO SHIPPING International (Hong Kong) narrative.
Another View: COSCO SHIPPING International (Hong Kong) Through Cash Flows
The P/E points to COSCO SHIPPING International (Hong Kong) looking expensive, yet the SWS DCF model is even harsher. It pegs future cash flow value at around HK$2.45 per share versus the HK$7.03 quote, which suggests the cash flow view also leans toward an overvalued picture. If earnings stay solid but cash generation stays weaker, which signal do you treat as more important?
Look into how the SWS DCF model arrives at its fair value.
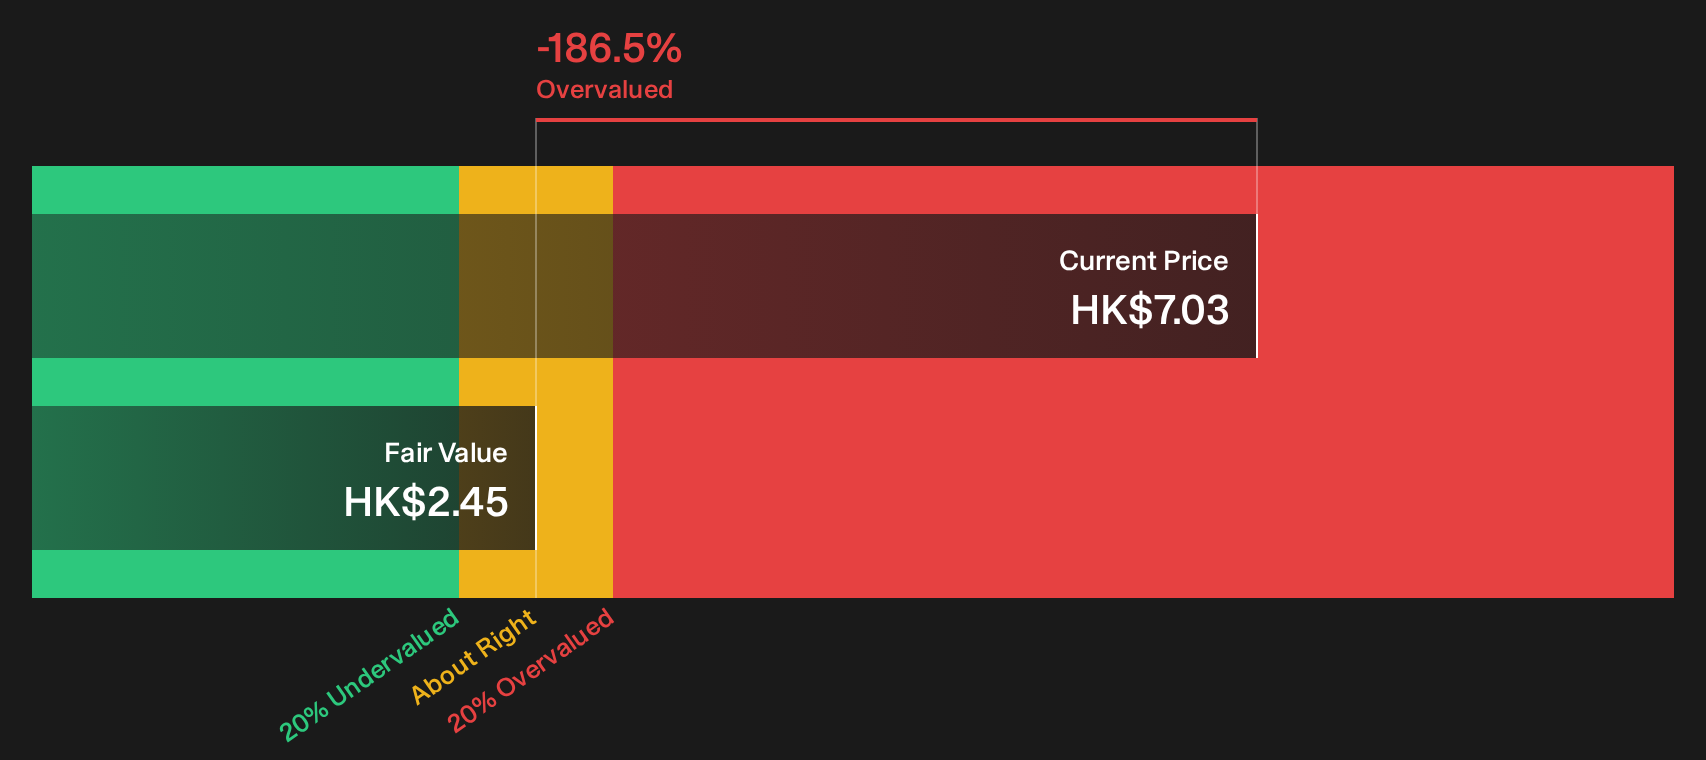
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out COSCO SHIPPING International (Hong Kong) for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 174 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of strong recent returns and softer cash flow signals feels conflicted, move quickly from headline impressions to your own conclusions by reviewing the 1 important warning sign that our analysis has highlighted through 1 important warning sign
Looking for more investment ideas beyond COSCO SHIPPING International (Hong Kong)?
If COSCO SHIPPING International (Hong Kong) has sharpened your focus on valuation and governance, do not ignore other corners of the market that may better match your risk and income preferences.
- Target resilient balance sheets and cut through noise by scanning a focused list of solid balance sheet and fundamentals (204 results) that filters for financial strength and fundamental support.
- Hunt for potential bargains by reviewing a hand picked 174 high quality undervalued stocks that couples quality metrics with pricing that may not last.
- Strengthen your income watchlist by checking a high yielding 223 dividend fortresses that spotlights companies prioritising regular cash returns to shareholders.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com