


BETA Technologies (BETA) just put its all electric ALIA CTOL aircraft through time sensitive cargo and medical flights across Utah, giving investors fresh, real world data on how its platform performs in regional healthcare logistics.
These Utah test flights arrive after a steady run of headlines for BETA Technologies, from new workforce partnerships at Marshall University to operational approvals that support more flight testing. Yet the ticker still carries a year to date share price return of down 23.23%, even as the 90 day share price return of 18.46% points to momentum rebuilding off recent lows.
Scan beyond BETA Technologies and compare this electric aviation story with a curated pool of capital goods peers using the list of solid balance sheet and fundamentals (25 results).
The recent rebound in BETA Technologies looks tied to real contracts, flight data, and partnerships rather than a mood swing in the chart. How does that backdrop line up with what investors are paying today?
Most Popular Narrative: 33% Undervalued
BETA Technologies closed at $20.98, while the most followed narrative pegs fair value at $31.50. The story focuses on whether today’s heavy investment phase eventually turns into the earnings power that model assumes.
Long duration aftermarket economics from annually refreshed batteries and power by the hour agreements, including for Eve’s H500B motors and BETA’s own aircraft, can turn each $4 million to $4.5 million sale into roughly $13 million of lifetime aftermarket revenue, supporting durable, compounding gross profit and a path to positive earnings as the installed base grows over the next two decades.
See why 9 investors see BETA Technologies as 33% undervalued.
Result: Fair Value of $31.50 (UNDERVALUED)
Still, the BETA Technologies story leans on supportive FAA timelines and ongoing access to fresh capital. Setbacks on either front could quickly challenge that 33% undervalued case.
Find out about the key risks to this BETA Technologies narrative.
Another View: What BETA Technologies Looks Like On P/B
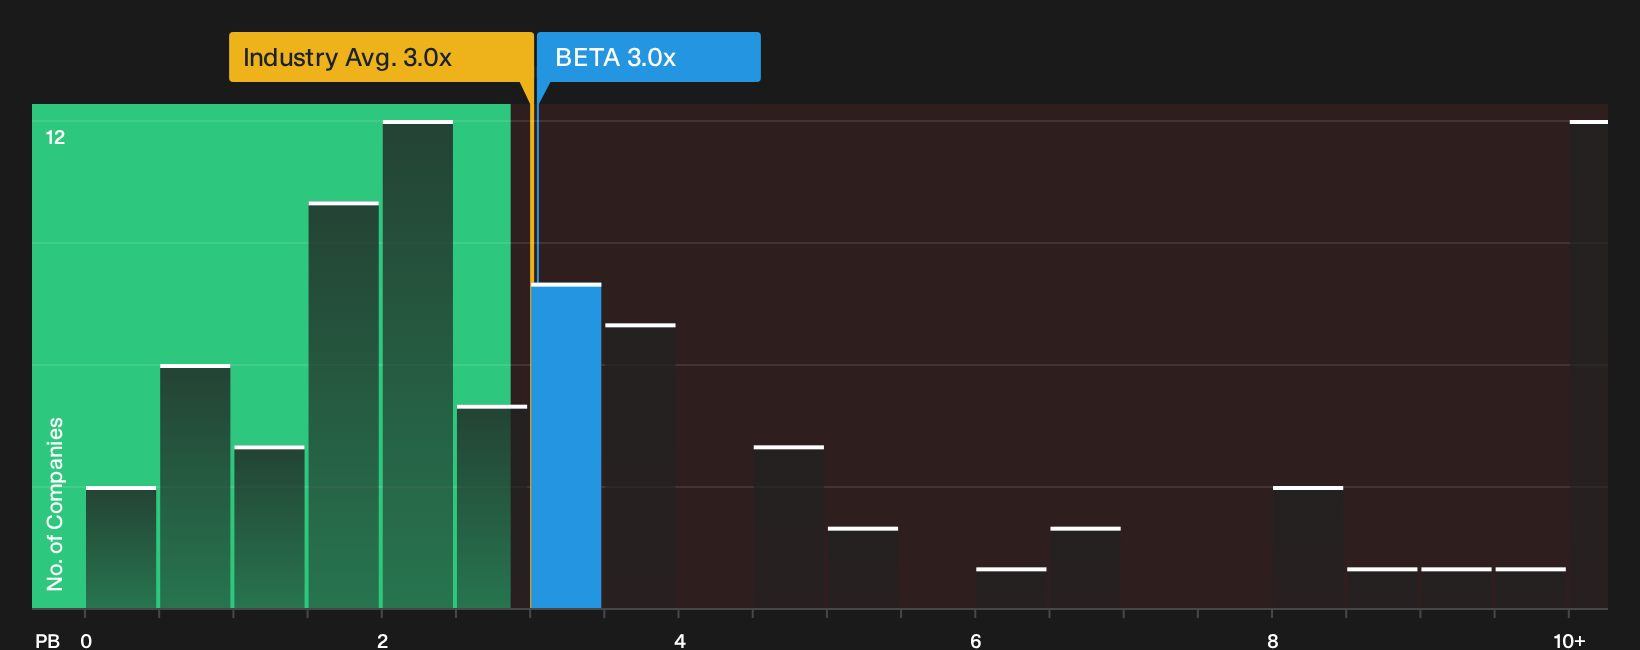
The story shifts when you stop looking at fair value models and focus on what the market is actually paying for BETA Technologies today. On a P/B of 3x, the stock is in line with the US Aerospace and Defense sector at 3x but sits cheaper than its peer average of 5x.
That mix sends a split message. The sector level comparison points to a full price, while the peer gap hints at a possible discount for investors who believe book value will matter more as the business matures. The real question is which crowd the market listens to next.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in BETA Technologies is clearly mixed, with real progress on one side and open questions on the other, so move quickly and weigh the evidence for yourself before the story shifts again. To see both the upside and the pressure points in one place, review the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond BETA Technologies?
If the BETA Technologies story has your attention, do not stop here. Put fresh ideas on your radar now so you are not reacting after the best setups move.
- Target dependable cash generators by scanning for companies with strong finances using the list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at a potential discount by reviewing the 28 high quality undervalued stocks that combine sturdy balance sheets with healthier cash flows.
- Build a more resilient watchlist by filtering for stocks with lower overall risk profiles through the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com