


Fresh analysis on A. O. Smith (AOS) focuses on weakening sales, softer earnings per share, and pressured returns on capital as tough end markets weigh on the business and influence sentiment around the stock.
The recent weakness in A. O. Smith’s end markets is showing up in the chart as well, with the share price at US$56.38 after a year-to-date share price decline of 17.48% and a 1-year total shareholder return that has fallen 14.93%. This suggests momentum has been fading as investors reassess earnings risk.
Rebalance away from A. O. Smith headwinds by scanning a hand picked set of resilient industrials and capital goods businesses in the list of solid balance sheet and fundamentals (25 results) list.
The share price slide and softer returns at A. O. Smith put you at a crossroads. Step in after a 17% year to date drop, or wait for cheaper terms to match the risks now showing up in the valuation?
Most Popular Narrative: 2.5% Overvalued
A. O. Smith last closed at $56.38, which sits slightly above the $55 fair value implied in the most followed narrative. You are weighing a modest premium against an otherwise steady industrial cash generator.
AOS manufactures water heaters and boilers in North America, with a secondary business in China that is in structural decline. The North American franchise is genuinely strong: three players control 90%+ of the market, the product is a non-discretionary emergency replacement in more than 80% of cases, and prices have risen above inflation for twelve consecutive years.
See why 2 investors see A. O. Smith as 3% overvalued.
Result: Fair Value of $55 (OVERVALUED)
Still, the heat pump mandate and any drawn out China review could force A. O. Smith to reconsider its distribution edge and capital allocation strategy.
Find out about the key risks to this A. O. Smith narrative.
Another View On A. O. Smith’s Valuation
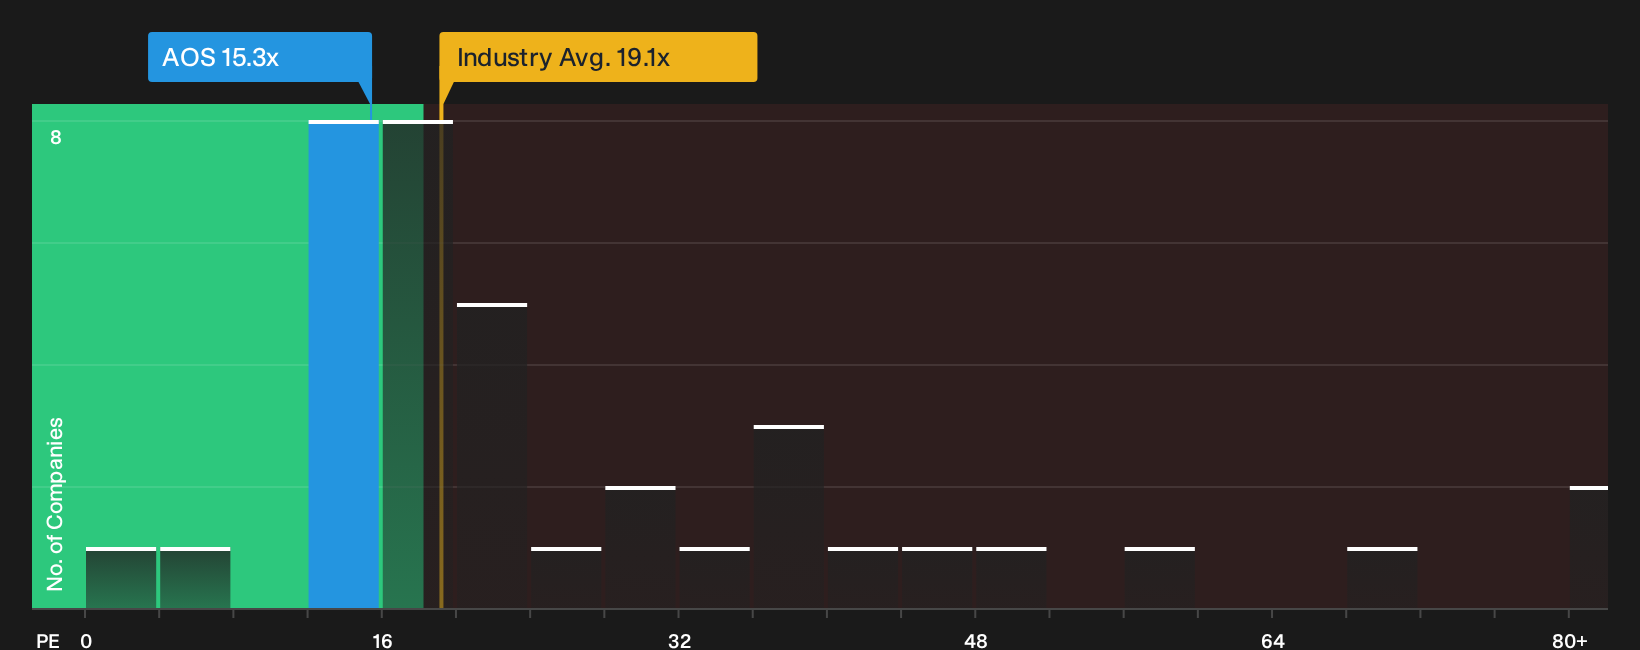
The first narrative pegs A. O. Smith as roughly 2.5% overvalued at $56.38 versus a $55 fair value, based on a required return near 9%. A different lens tells a softer story. On a P/E of 15.3x, the shares sit below both the peer average of 22.3x and an 18.5x fair ratio the market could move toward. This points to less valuation risk if earnings hold up or recover.
If one approach flags limited margin of safety and another hints at room for the multiple to close the gap, which signal do you trust more when real money is on the line?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in A. O. Smith is clearly split, and hesitation is visible in the recent price action. If you want to move past the noise and judge the situation on your terms, start by reviewing the 5 key rewards.
Looking for more investment ideas beyond A. O. Smith?
Do not stop at A. O. Smith. Use the same clear-eyed approach to scan fresh opportunities, compare quality, and tighten your shortlist with data that actually helps decisions.
- Target value first and hunt for mispriced quality by reviewing the 28 high quality undervalued stocks.
- Prioritise resilience and stress test your downside by focusing on the 31 resilient stocks with low risk scores.
- Spot under-the-radar potential and broaden your watchlist with the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com