


- Emerson Electric is heading into its next earnings release with consensus expectations for earnings of $1.84 per share and revenue of about $5.1 billion, which would represent double digit earnings growth and mid single digit top line expansion compared with the same period a year earlier.
- The key thread is execution, because analyst estimate upgrades and a Zacks Rank #2 rating are now tied directly to whether Emerson Electric can translate its current order funnel into sustained earnings power.
- We will now see how Emerson Electric's investment narrative could be shaped by this stronger earnings outlook and recent estimate upgrades.
Scan how Emerson Electric's setup compares to other industrials showing strong execution on earnings and order momentum by screening for 43 power grid technology and infrastructure stocks in one place.
Emerson Electric Investment Narrative Recap
Owning Emerson Electric means believing its automation, software and Test & Measurement lines can keep converting a large project funnel into steady earnings, even as some regions stay choppy. In the near term, the hinge is execution. Markets are watching whether the incoming quarter around the expected US$1.84 EPS and US$5.1b revenue confirms that order conversion is holding up.
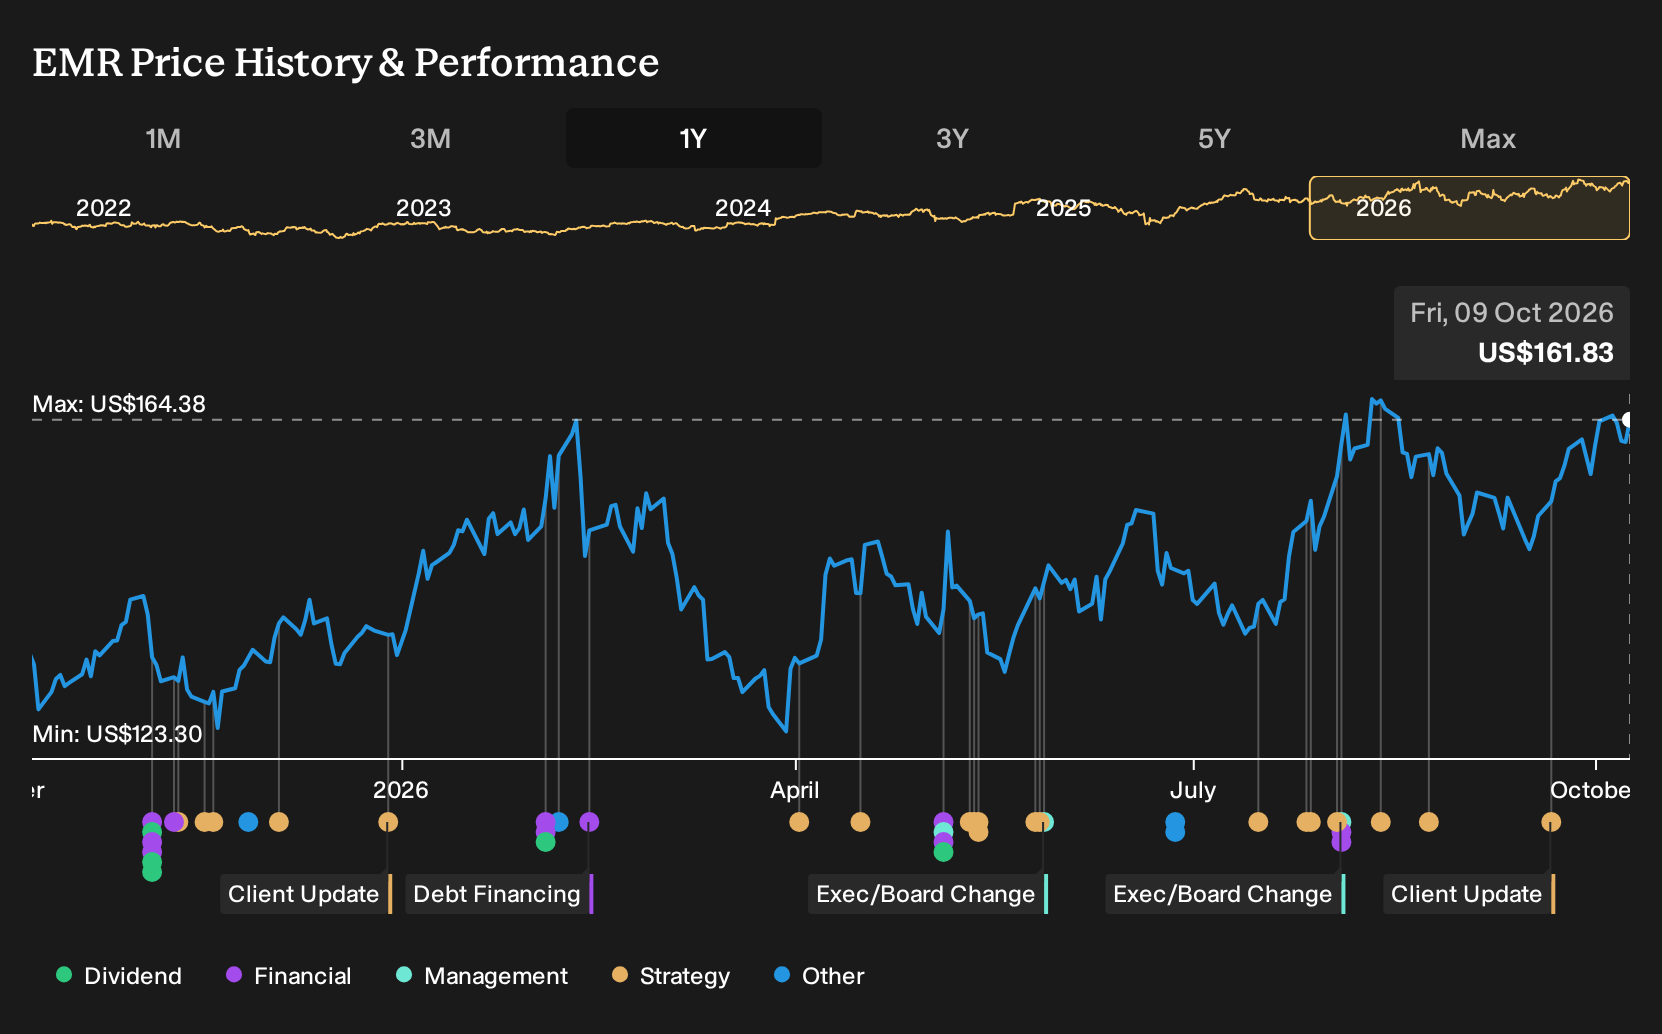
The biggest swing factor remains project timing in power, LNG, AI software and Test & Measurement. Conflict related disruption in the Middle East and softer demand in China already weigh on the story. The latest share price strength and upbeat forecasts do not fundamentally change those operational risks.
The clearest link to the current move in Emerson Electric is the projected 13.6% year over year EPS increase to US$1.84 and revenue expectations of US$5.1b, up 5.15%. That is where the catalyst sits. If those figures are met, it reinforces the idea that digital automation, recurring software and Test & Measurement are doing the heavy lifting.
Estimate revisions and the Zacks Rank #2 rating simply reflect that backdrop rather than create it. Your focus is better spent on whether software annual contract value, LNG and power orders, and Test & Measurement momentum can offset pressure from the Middle East and China. Execution across those projects, not the short term share move, is what will matter most.
Emerson Electric's current analyst blueprint points to revenues of US$21.9b and earnings of US$3.8b by 2029, built on an assumed 5.6% yearly revenue growth rate and an earnings increase of about US$1.2b from US$2.6b today to that 2029 consensus level.
Uncover why Emerson Electric's fair value indicates a 7% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For Emerson Electric, the alternate view centers on pressure from rising protectionism. The most bearish analysts were assuming only 4.8% annual revenue growth and earnings of about US$3.7b by 2029, versus the higher consensus path. That group paints a cooler outlook, and the latest price and earnings news could easily reshape both stories.
Explore 3 other Emerson Electric fair value estimates, including one that suggests as much as 50% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Emerson Electric research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Emerson Electric. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Emerson Electric's overall financial health at a glance.
Looking For More Investment Ideas Beyond Emerson Electric?
If you want to stress test your view on Emerson Electric against other opportunities, it can help to scan a wider field of companies with different strengths and risk profiles.
- If quality at a discount is your priority, sift through 28 high quality undervalued stocks that combine solid fundamentals with potentially appealing pricing.
- If capital preservation matters more to you than high octane returns, weigh up 31 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- If you prefer under followed opportunities with room for fresh coverage, comb through 20 high quality undiscovered gems that pair strong financial traits with lower visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com