


Monolithic Power Systems (MPWR) just posted record quarterly revenue, driven by stronger enterprise data demand and more than 1,500 new automotive product launches. This has drawn fresh attention to its earnings scalability and institutional interest.
Over the past year, Monolithic Power Systems has moved from an April breakout, when the share price surged more than 32%, into a new consolidation phase. A 30-day share price return of 16.88% and a year-to-date share price return of 48.06% point to building momentum. Recent volatility, including a 7-day share price return that declined 3.71%, sits against a 1-year total shareholder return of 54.30% and a roughly 2x total shareholder return over both three and five years. This suggests the latest record quarter is being read as reinforcing an already strong longer term story rather than sparking a new one out of nowhere.
Capitalize on Monolithic Power Systems’ earnings momentum by scanning a curated set of AI infrastructure peers through our 92 AI infrastructure stocks.Monolithic Power Systems has already rewarded patient holders, yet the sharp re-rating after record results leaves a live question. Are you now paying mostly for past execution, or is the valuation still pricing in headroom?
Most Popular Narrative: 25% Undervalued
The most followed narrative pegs Monolithic Power Systems at a fair value of $1,839.80, well above the last close of $1,386.29. That gap rests heavily on the idea that today’s capacity build lines up cleanly with future AI and automotive demand.
The company's significant investments in manufacturing and technology are now tied to a capacity plan extended beyond US$6b in annual revenue equivalents and a long term 300mm manufacturing partnership in Singapore that targets early 2027 volume. Successful utilization of this footprint and ramp of silicon carbide and GaN power products could support higher revenue and help protect gross margins over time.
See why 81 investors see Monolithic Power Systems as 25% undervalued.
Result: Fair Value of $1,839.80 (UNDERVALUED)
Still, the story around Monolithic Power Systems can change quickly if extended capacity weighs on free cash flow or if investigations around customer orders escalate into heavier costs.
Find out about the key risks to this Monolithic Power Systems narrative.
Another View: Monolithic Power Systems Through The P/E Lens
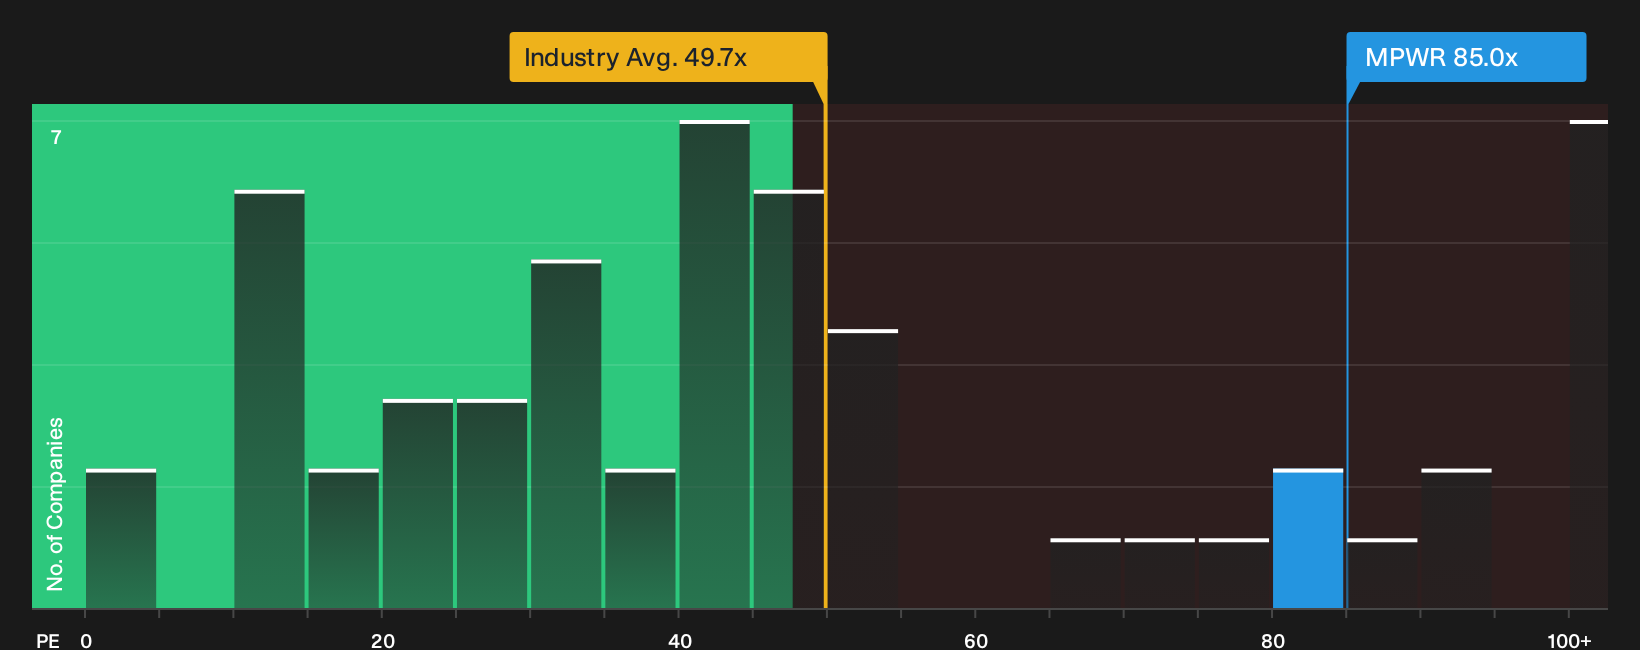
There is a catch. On the preferred earnings multiple, Monolithic Power Systems trades on a P/E of 85x, compared with a fair ratio of 35.4x, an industry average of 49.7x and peer average of 73.9x. That is a rich setup. Is this premium headroom or downside risk?
For a closer look at how that earnings multiple lines up with fundamentals and peers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the current mood around Monolithic Power Systems feels too optimistic or too cautious? Move quickly, review the underlying data, and weigh both sides yourself before sentiment shifts. Then round out your view with the 2 key rewards and 1 important warning sign
Looking for more Monolithic Power Systems investment ideas?
If you are serious about sharpening your edge beyond Monolithic Power Systems, use the screener to surface fresh opportunities before everyone else catches on.
- Target resilient performers that aim to protect your downside first by running a focused search for 31 resilient stocks with low risk scores.
- Hunt for companies where price and quality still look out of sync by scanning a curated universe of 28 high quality undervalued stocks.
- Strengthen your income stream and potential total return mix by zeroing in on 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com