


- Mettler-Toledo International recently reported a quarter where sentiment toward its life-science tools improved, supported by stronger China sales and management commentary about robust biopharma investment.
- A key angle is the growing focus on AI driven lab automation and analytical instruments, which more closely links Mettler-Toledo International to pharmaceutical R&D productivity spending.
- We will now look at how Mettler-Toledo International's investment narrative interacts with stronger China demand for its life-science tools.
Scan beyond Mettler-Toledo International and compare it with a curated group of lab and automation beneficiaries by checking out 91 robotics and automation stocks tied to the same AI productivity theme.
Mettler-Toledo International Investment Narrative Recap
To own Mettler-Toledo International, you need to believe its mix of precision instruments, software and services stays tightly linked to pharma, biotech and other customers that care about R&D productivity and automation. The latest quarter supports that thesis, with better sentiment in life-science tools, stronger China demand and rising interest in AI driven lab automation.
The key near term swing factor is how quickly lab and bioprocessing demand translates into orders for automation and process analytics. The main risk remains external, not internal, with tariffs, European industrial softness and the firm’s high debt level all capable of offsetting benefits from higher value services and pricing discipline.
One of the most relevant data points tied to this news is management’s commentary on China, where lab activity and broader biopharma investment showed strength. That sits directly against earlier concerns that tariffs and regional weakness might cap organic growth or weigh on net margins for Mettler-Toledo International.
If China lab demand continues to improve, it could support the automation and bioprocessing catalyst that many investors focus on, alongside existing projects in semiconductors and clean energy. Execution still matters, especially around cost savings, pricing and service expansion, because softer specialty chemical and European markets remain a live drag on the overall story.
What The Current Forecasts Assume For Mettler-Toledo International
Mettler-Toledo International's narrative projects revenues of US$4.8b and earnings of US$1.1b by 2029. Analysts are building this on revenue growth assumptions of 4.9% per year and an increase in profit from US$905.6m today to that US$1.1b level, which implies an earnings uplift of about US$194m from current earnings.
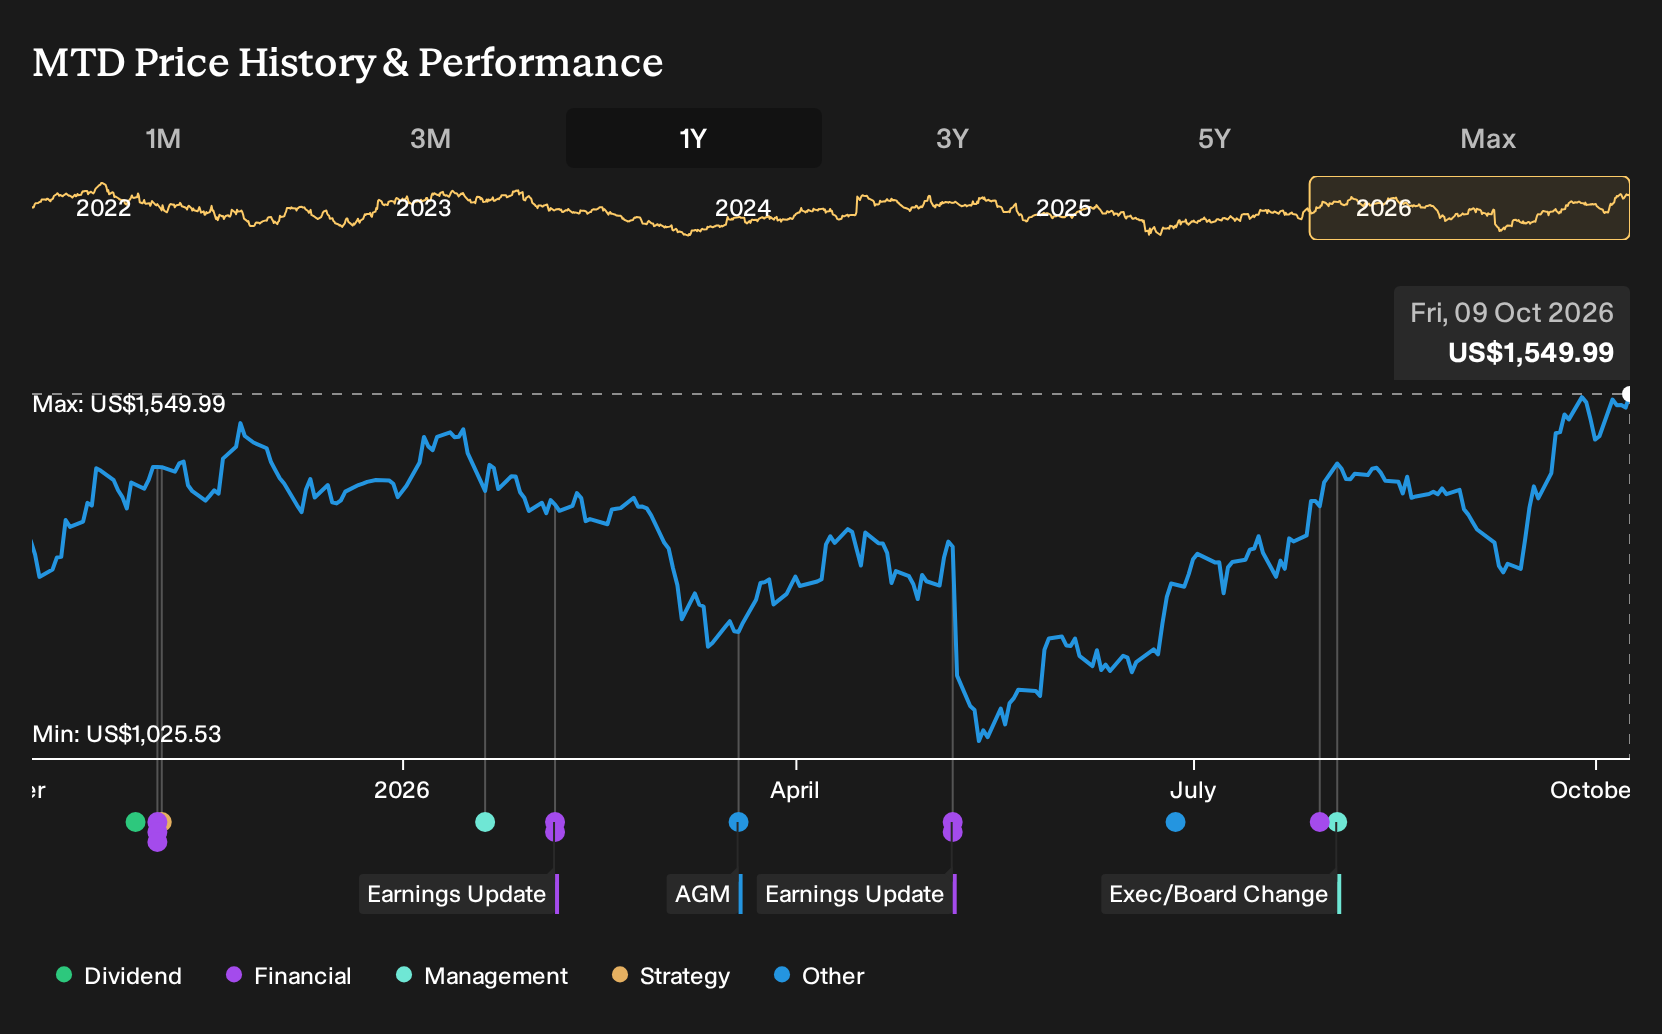
Uncover why Mettler-Toledo International's fair value indicates a 4% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between about US$1,408 and US$1,494, which shows just how narrow some retail views on Mettler-Toledo International can be. Your own stance might differ once you weigh tariff uncertainty, European demand risk, and the potential pull from long running automation projects.
Explore another Mettler-Toledo International fair value estimate, including one that suggests it could be worth as much as $1494.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Mettler-Toledo International research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Mettler-Toledo International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mettler-Toledo International's overall financial health at a glance.
Looking for more investment ideas beyond Mettler-Toledo International?
Once you form a view on Mettler-Toledo International, it often helps to set it beside other opportunities that match your risk tolerance, income needs, or focus on quality. The Simply Wall St screener can surface a range of stocks that fit those different angles.
- If you want to stay focused on quality at a sensible entry point, compare Mettler-Toledo International with a 28 high quality undervalued stocks that pair strong fundamentals with more modest pricing.
- If capital preservation sits high on your list, you can widen your watchlist to include a 31 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- If you are hunting for less crowded ideas, scan through a 20 high quality undiscovered gems that combine solid fundamentals with relatively limited current attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com