


- Boston Beer Company’s Twisted Tea brand previously launched a limited edition fall collaboration with outdoor label Realtree, adding camouflage packaging and a camo themed merch line to reinforce the hard tea’s outdoor identity.
- The collaboration highlights Boston Beer’s effort to deepen lifestyle branding, while recent financial results and thinner operating margins put pressure on the core business model.
- Next, the focus will be on how Boston Beer Company’s results, in the context of Twisted Tea’s Realtree tie up, reshape its investment narrative.
Boston Beer Company Investment Narrative Recap
For Boston Beer Company to make sense in your portfolio, you need to believe the shift toward higher priced beyond beer brands and tighter cost control can eventually outweigh volume pressure in Twisted Tea, Truly and the legacy beer labels. The key near term catalyst is execution on productivity gains, internal production and trimming lower return marketing in order to rebuild operating margin from today’s loss making position.
The biggest current risk is that category headwinds and brand fatigue in hard tea, seltzer and flavored malt beverages keep dragging on depletions and shipments while selling costs stay elevated. The Twisted Tea and Realtree collaboration is eye catching but, by itself, appears immaterial for near term earnings or the aluminum can judgment overhang.
The Realtree camo rollout for Twisted Tea matters mainly as a test of how Boston Beer Company uses lifestyle partnerships to support brand health without overspending. It sits alongside management’s plan to cut about US$20m of lower return advertising and redirect spend toward more targeted, grassroots style activity, where payback is expected to be stronger.
For you as a shareholder, the key question is whether this sort of limited edition campaign can keep Twisted Tea culturally relevant while the broader portfolio pivots toward higher revenue per case offerings such as Sun Cruiser. If the outdoor themed push does not help stabilize Twisted Tea volumes, the burden on mix improvement, cost reductions and internalization to support future profitability increases further.
What The Twisted Tea Bet Implies About Boston Beer Company’s Earnings Path
Boston Beer Company's current analyst narrative anchors on earnings turning around more than the headline camo cans or Realtree hoodies. Analysts are assuming revenue stays roughly flat over the next 3 years while margins rebuild from a loss of 3.7% today to 5.6% in 2029. This would move the business from a US$70.4 million loss to US$108.7 million of profit in that year. That swing represents an earnings change of about US$179 million and underpins consensus forecasts that tie into the Twisted Tea outdoor lifestyle push, the shift toward higher revenue per case brands and tighter cost control.
Boston Beer Company's narrative projects US$1.9b revenue and US$108.7 million earnings by 2029. This reflects roughly flat yearly revenue trends and an earnings increase of about US$179 million from a loss of US$70.4 million today.
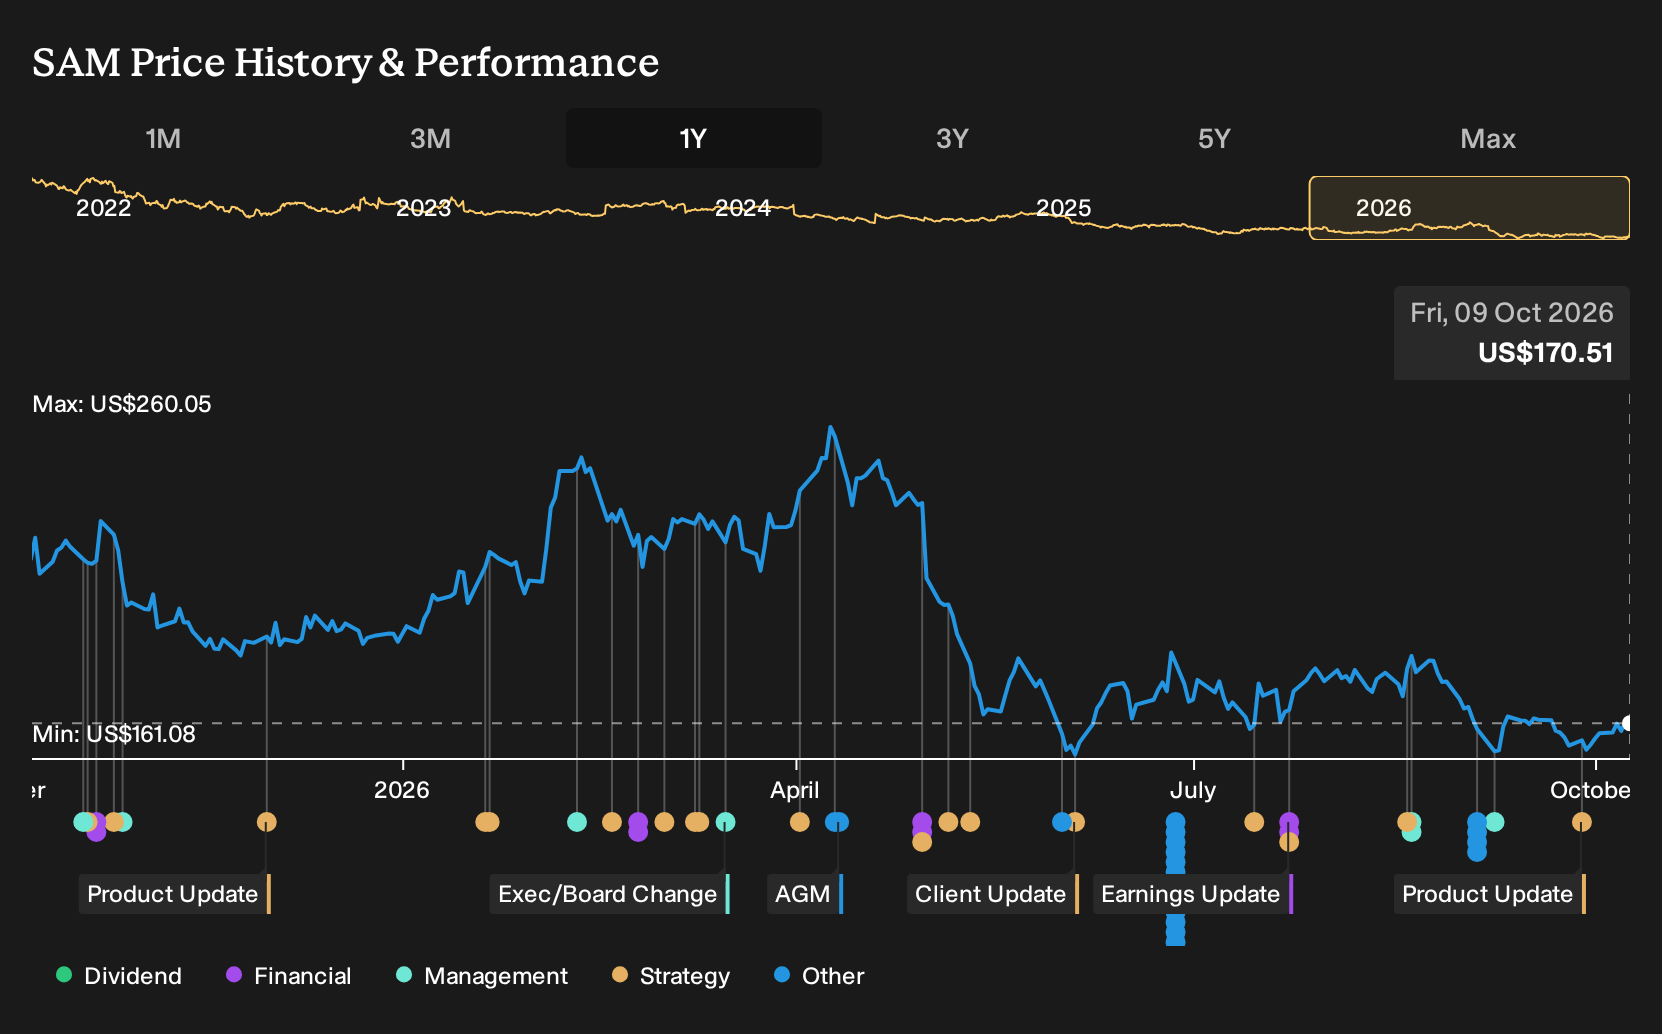
Uncover how Boston Beer Company's fair value indicates a 17% potential upside to its current price before that discount gap starts to close.
Exploring Other Perspectives
One bearish angle you might explore focuses on ongoing volume pressure rather than the Twisted Tea and Realtree marketing lift. The most pessimistic analysts were modelling revenue drifting to about US$1.8b and earnings of roughly US$128.7 million by 2029, before this collaboration. Their storyline could shift a lot if the outdoor push lands differently than expected.
Explore 2 other Boston Beer Company fair value estimates, including one that suggests it could be worth just $199.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Boston Beer Company research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Boston Beer Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Boston Beer Company's overall financial health at a glance.
Looking For More Investment Ideas Beyond Boston Beer Company?
Once you have a view on Boston Beer Company, it can help to test that thesis against other businesses with very different risk and return profiles. The Simply Wall St Screener lets you scan for stocks that match your priorities, whether that is value, resilience or under the radar potential.
- For investors who care most about quality at a sensible price, review a curated list of companies screened for attractive fundamentals and valuation through 28 high quality undervalued stocks.
- If capital preservation and steadier return profiles matter more to you than chasing the highest upside, filter for businesses with stronger balance sheets and more conservative risk scores using the 31 resilient stocks with low risk scores.
- When you want to get ahead of the crowd and research under followed stories, focus on financially solid but less widely covered opportunities via the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com