


Leadership shift puts Tetra Tech’s Commercial/International arm in focus
Tetra Tech (TTEK) is back on investor radar after promoting long-time executive David Bohmann to President of its Commercial/International Group, a move that more closely aligns leadership with its water and environmental consulting strategy.
The stock has been choppy rather than trending, with the share price down about 6.1% over the past month but higher by 7.6% over the last 90 days. Total shareholder return has slipped 1.1% over the past year yet still gained 7.4% over three years, pointing to momentum that has cooled recently rather than collapsed.
Scan beyond Tetra Tech and compare it with a hand picked list of solid balance sheet and fundamentals (25 results) that also leans on recurring cash flows and disciplined capital allocation.
Tetra Tech now trades around $33.34, while both analyst targets and intrinsic estimates cluster meaningfully higher. Does that gap reflect mispricing, or a fair discount on recent share volatility as leadership reshapes the Commercial/International arm?
Most Popular Narrative: 17% Undervalued
Tetra Tech’s most followed narrative pegs fair value at $40.33 per share, which sits well above the recent $33.34 close and frames the current debate around whether investors are underestimating its contract base and cash generation.
Increased global spending on water infrastructure programs, including the roughly £105b U.K. AMP8 cycle and Ireland’s planned €11.8b water investments, together with double digit municipal water treatment growth in the U.S., points to a long pipeline of projects where Tetra Tech can convert existing contract capacity into future net revenue and earnings.
See why 16 investors see Tetra Tech as 17% undervalued.
Result: Fair Value of $40.33 (UNDERVALUED)
Still, Tetra Tech’s story can break if USAID and Department of State work remains structurally lower, while offshore wind and broader renewables stay under pressure.
Find out about the key risks to this Tetra Tech narrative.
Another View: What Tetra Tech’s P/E Is Really Saying
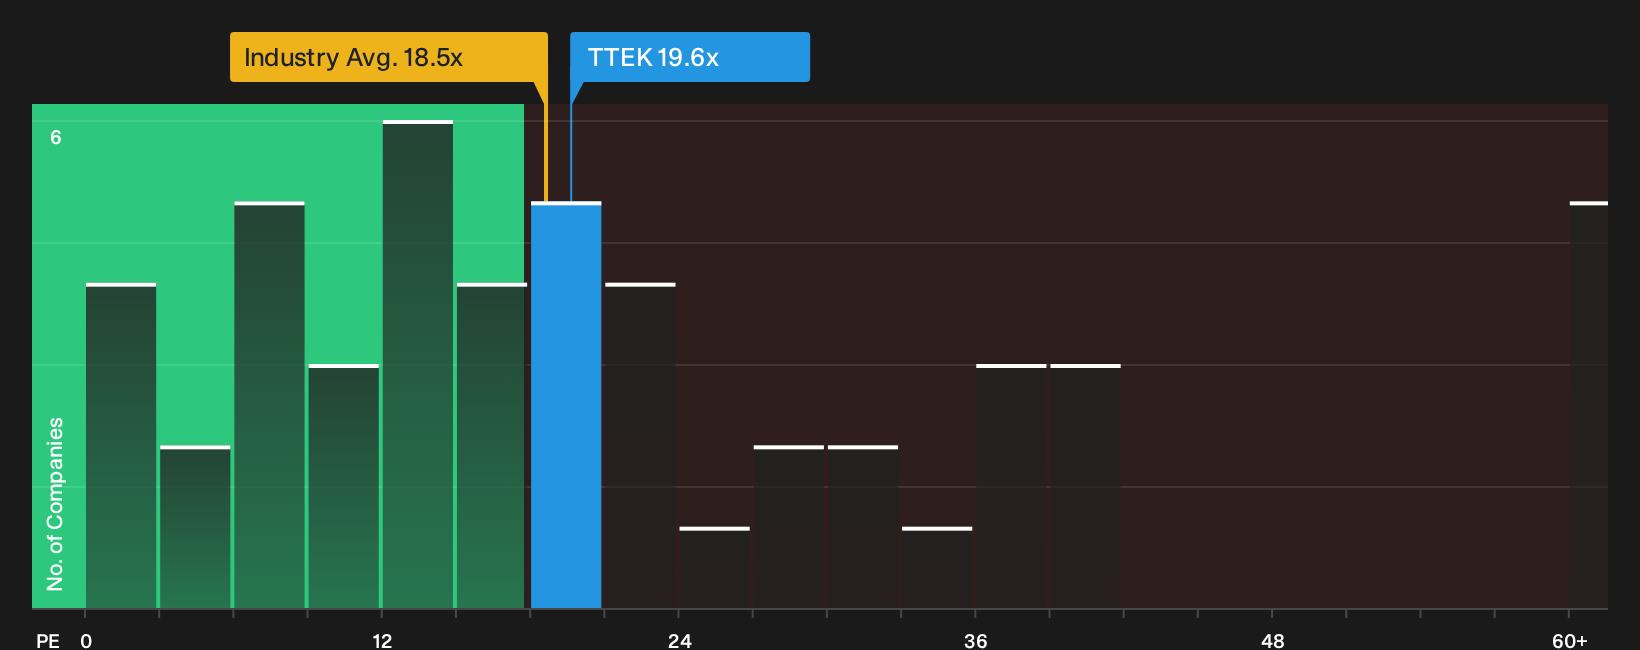
The first narrative casts Tetra Tech as undervalued, yet the P/E picture looks less forgiving. The shares trade around 19.6x earnings, which is higher than the US Commercial Services industry at 18.5x and above a fair ratio of 16.8x. That gap hints at less cushion if expectations slip, so is the discount to fair value as comfortable as it appears?
For investors who prefer to lean on earnings multiples, this kind of comparison can be a useful sense check before making any moves. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone here leaves you unsure, treat that hesitation as a cue to move quickly, review the data yourself, and weigh up both risks and potential upsides. To see what other investors flag as the main upsides, take a closer look at the 4 key rewards.
Looking for more Tetra Tech investment ideas?
Do not stop your research with Tetra Tech alone. Broader opportunities often appear where you least expect them, and missing them can quietly drag on long term returns.
- Target potential mispricing by scanning companies that screen as potential value opportunities through the 28 high quality undervalued stocks.
- Build a steadier income stream by reviewing the 8 dividend fortresses that focus on higher yielding payouts with more robust profiles.
- Reduce portfolio stress by filtering for businesses on the 31 resilient stocks with low risk scores that score better on resilience and balance sheet strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com