


Rambus has delivered a powerful run for long term holders, and the current share price now invites a closer look at how firmly its earnings support that move. With the stock recently changing hands around US$107.47, the key issue is whether the profit it generates is enough to justify that level.
- Over the past 5 years the stock has returned about 384.1%, which puts real pressure on the question of whether its earnings can carry that kind of re-rating any further.
- The business leans heavily on licensing and semiconductor related technology, so the durability of its royalty streams and margins may support or limit how much value investors can reasonably tie to its profit line.
- The analysts covering Rambus have run their own numbers. See what analysts think Rambus's shares could be worth.
For investors, the debate is whether Rambus' current share price fairly reflects what its earnings stream can justify today.
If you are weighing Rambus against other earnings driven ideas, a focused screen of stocks with solid balance sheets and fundamentals can be a useful next stop for research via the solid balance sheet and fundamentals stocks screener (25 results).
Has Rambus Run Too Far on Earnings?
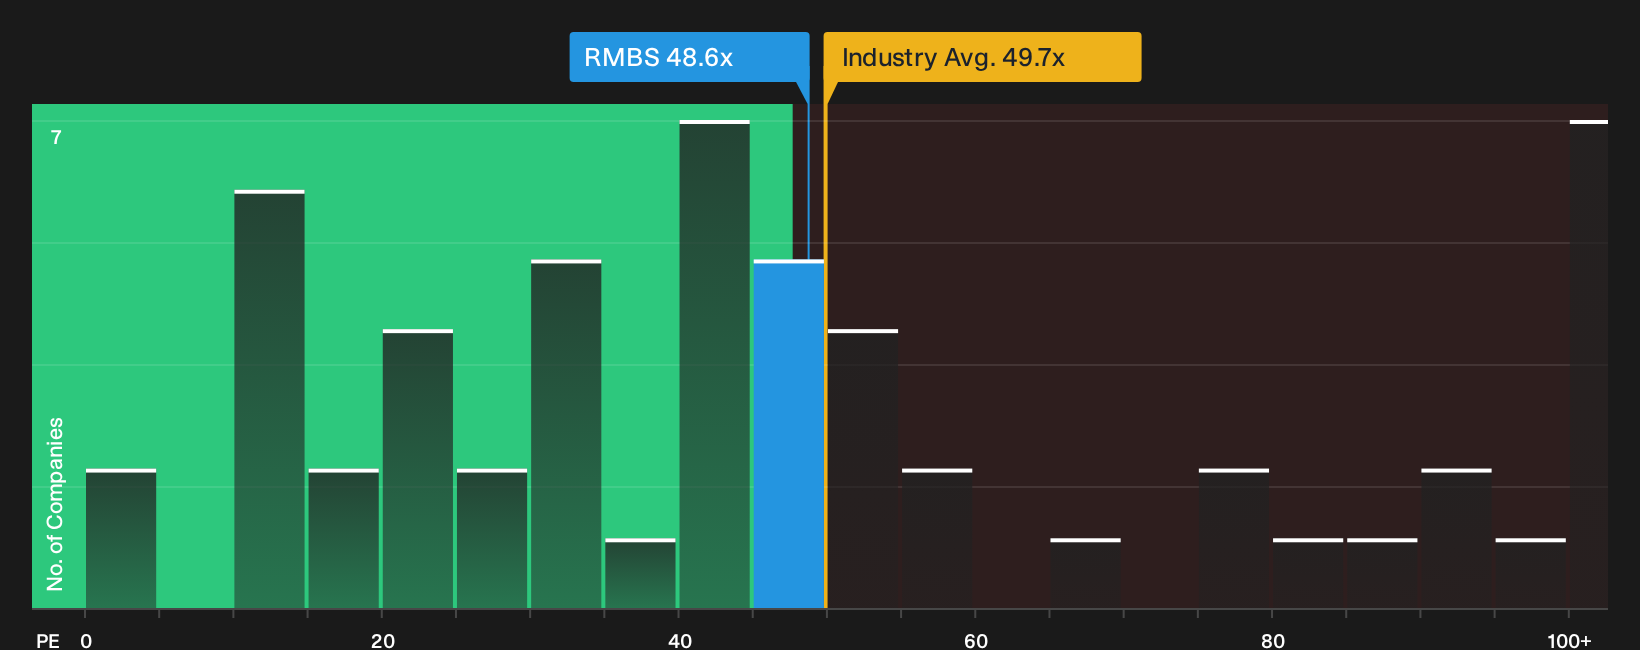
The P/E ratio fits Rambus because earnings still drive how investors frame the value of its licensing heavy model. On this yardstick, the stock changes hands at roughly 48.6x earnings, which is close to the wider semiconductor sector average near 49.7x and modestly above the peer group around 45.1x.
The fair value model suggests that, given Rambus' own mix of growth expectations, profitability and risk, a lower P/E would be more typical. The current 48.6x sits above that tailored benchmark and screens as overvalued on this lens. For you as a shareholder or potential buyer, that means the market already builds in a strong view of what Rambus' future earnings stream could be, and any reassessment of those assumptions can move the share price quickly in either direction. Explore the numbers behind Rambus's P/E valuation.
The Rambus Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Rambus valuation question leaves off by spelling out which specific paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today’s price. Each narrative links its number to a clear view on how Rambus' growth profile, profitability and risk could evolve, giving you something concrete to revisit as fresh information comes through.
Community views on Rambus split between investors who see an AI powered growth runway and others who think execution and legal risk make the current price demanding.
Bull case: 27% undervalued
"The current valuation implies that Rambus shares do not fully reflect the combination of record revenue, strong cash from operations and ongoing buybacks..."
Discover why this Narrative puts Rambus at 27% undervalued.
Bear case: 7% overvalued
"Ongoing tightness in back end capacity and longer lead times, combined with Rambus plans to build inventory, create a risk that sudden changes in server or AI demand leave the company with less productive stock..."
Explore why this Narrative puts Rambus at 7% overvalued.
One more important angle on Rambus to check
Before stopping at the current figures and ratios, it is worth asking who is actually steering Rambus and how their pay packets line up with your interests as a shareholder. See who runs Rambus and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com