


Cheniere Energy has ridden a strong multi year run in liquefied natural gas, and with the stock around recent highs the real question is whether its earnings are doing enough work to justify that price. For anyone looking at the ticker today, the issue is less about headlines and more about how the profit engine lines up with what the market is already paying.
- Over the past 5 years the stock has returned 164.6%, which puts a lot of weight on whether the underlying earnings profile can keep backing up that kind of share price journey.
- The new 22 year LNG supply agreement with Petrobras may support more visibility on future volumes and cash generation, which can influence how confidently investors treat current earnings as a guide for the business over time.
- There is a second opinion on Cheniere Energy worth weighing. See what analysts think Cheniere Energy's shares could be worth.
The issue now is whether Cheniere Energy's current share price is appropriately aligned with what its earnings justify when set against the Fair Ratio benchmark.
If you are considering whether Cheniere Energy's earnings justify today's price, it can help to compare that same question across 28 high quality undervalued stocks.
Does Cheniere Energy Look Fairly Valued on Earnings?
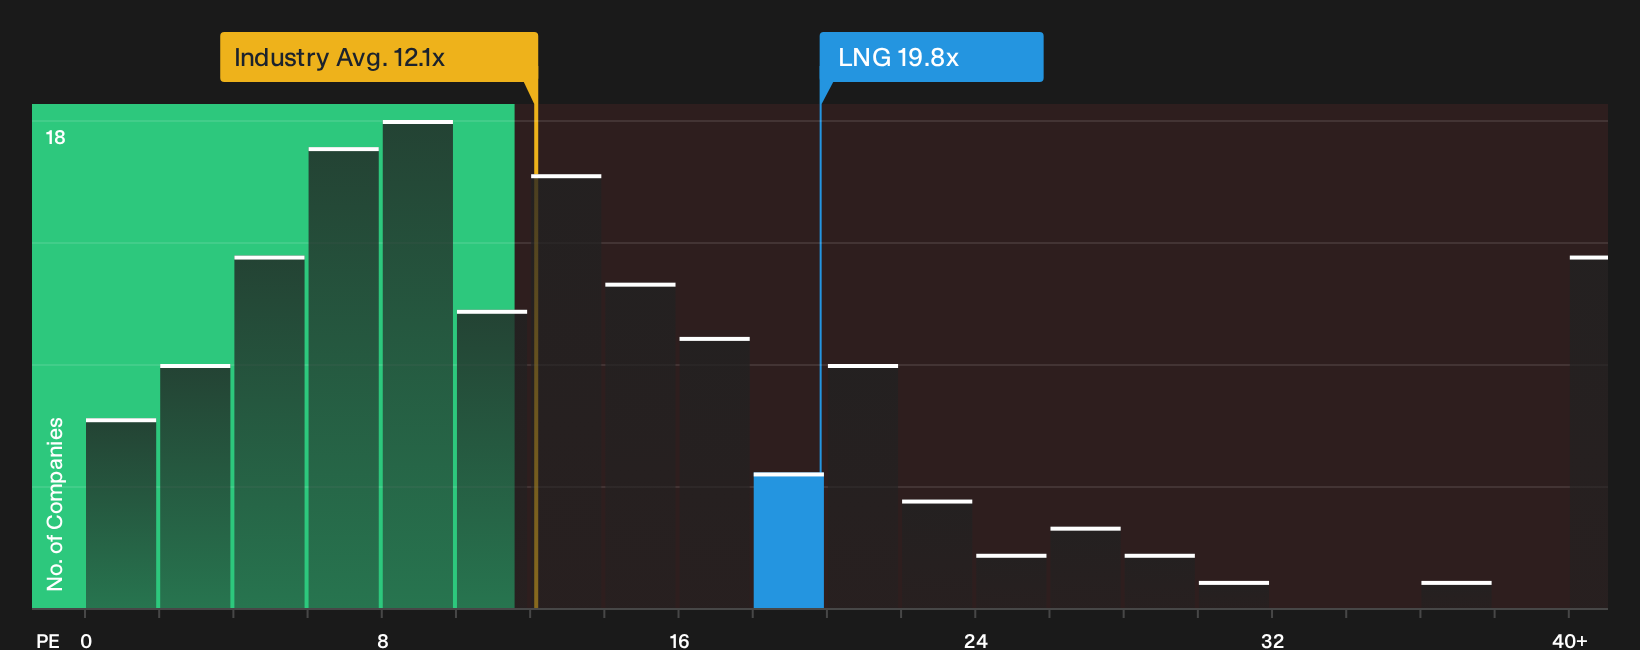
The P/E lens suits Cheniere Energy because investors often focus on the earnings power of long term LNG contracts when they think about valuation. On this measure, the stock trades on roughly 19.8x earnings, which is higher than the broader Oil and Gas sector average of about 12.1x yet close to the peer group on roughly 18.6x.
The Fair Ratio, which reflects what a tailored P/E might look like once earnings quality, size and risk are accounted for, points to a multiple very similar to where Cheniere Energy trades today. The current P/E therefore sits near that mark rather than far above or below it. Because the new 22 year Petrobras LNG agreement gives more visibility on contracted volumes, the market appears comfortable paying this level for the earnings stream even though it represents a premium to the wider industry. Explore the numbers behind Cheniere Energy's P/E valuation.
The Cheniere Energy Narrative: What Would Justify Today's Price?
Narratives for Cheniere Energy pick up where the P/E work leaves off and spell out which paths for growth, margins and earnings would need to hold for the stock to end up worth materially more or materially less than today's price on Simply Wall St's Community page. Instead of giving a single number, they describe the future that number reflects so you can follow how Cheniere Energy's actual progress lines up with those expectations over time.
One of the top community narratives on Cheniere Energy: 13% undervalued
"Cheniere operates the largest LNG export terminals in the US, Sabine Pass and Corpus Christi, and runs them like a toll road..."
Discover why this Narrative puts Cheniere Energy at 13% undervalued.
For Cheniere Energy, the share price is only one part of the story
Cheniere Energy's current valuation tells you what the market is willing to pay today. However, professional analysts have built detailed scenarios for where this business could be a few years from now. Explore where analysts expect Cheniere Energy to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com