


Mercury Systems (MRCY) is drawing fresh attention after expanding its Phoenix manufacturing campus by 50,000 sq. ft. and rolling out its RES One rugged edge server platform for long-life defense and industrial missions.
Recent moves suggest investors are weighing Mercury Systems' expansion and product launch against a mixed price trend. The 90 day share price return is down 26.38%, while the year to date share price return is 4.55% and the 3 year total shareholder return is 105.77%. This indicates long term momentum alongside shorter term volatility around the latest announcements.
Scan other defense and industrial electronics players showing similar momentum to Mercury Systems' recent expansion and product launch using the curated list of solid balance sheet and fundamentals (25 results).
Mercury Systems now sits between a bullish story built on long contracts and new capacity, and a bearish view focused on share price swings and current losses. Which side do today’s valuation signals lean toward?
Most Popular Narrative: 31% Undervalued
At a last close of $79.49 versus a narrative fair value of $115.78, Mercury Systems is framed as materially undervalued. That gap rests on confidence in record backlog, AI partnerships and margin improvement rather than short term share price weakness.
Growth in backlog and bookings across U.S. and European defense primes, particularly in radar, electronic warfare, and sensor modernization, demonstrates strong alignment with defense modernization and increased global defense spending, which is likely to support sustained revenue growth and future EPS expansion as these programs convert to production.
See why 9 investors see Mercury Systems as 31% undervalued.
Result: Fair Value of $115.78 (UNDERVALUED)
Still, the narrative around Mercury Systems could crack if legacy low margin contracts drag longer than analysts expect, or if defense order timing softens against those forecasts.
Find out about the key risks to this Mercury Systems narrative.
Another View: Mercury Systems Looks Expensive On Sales
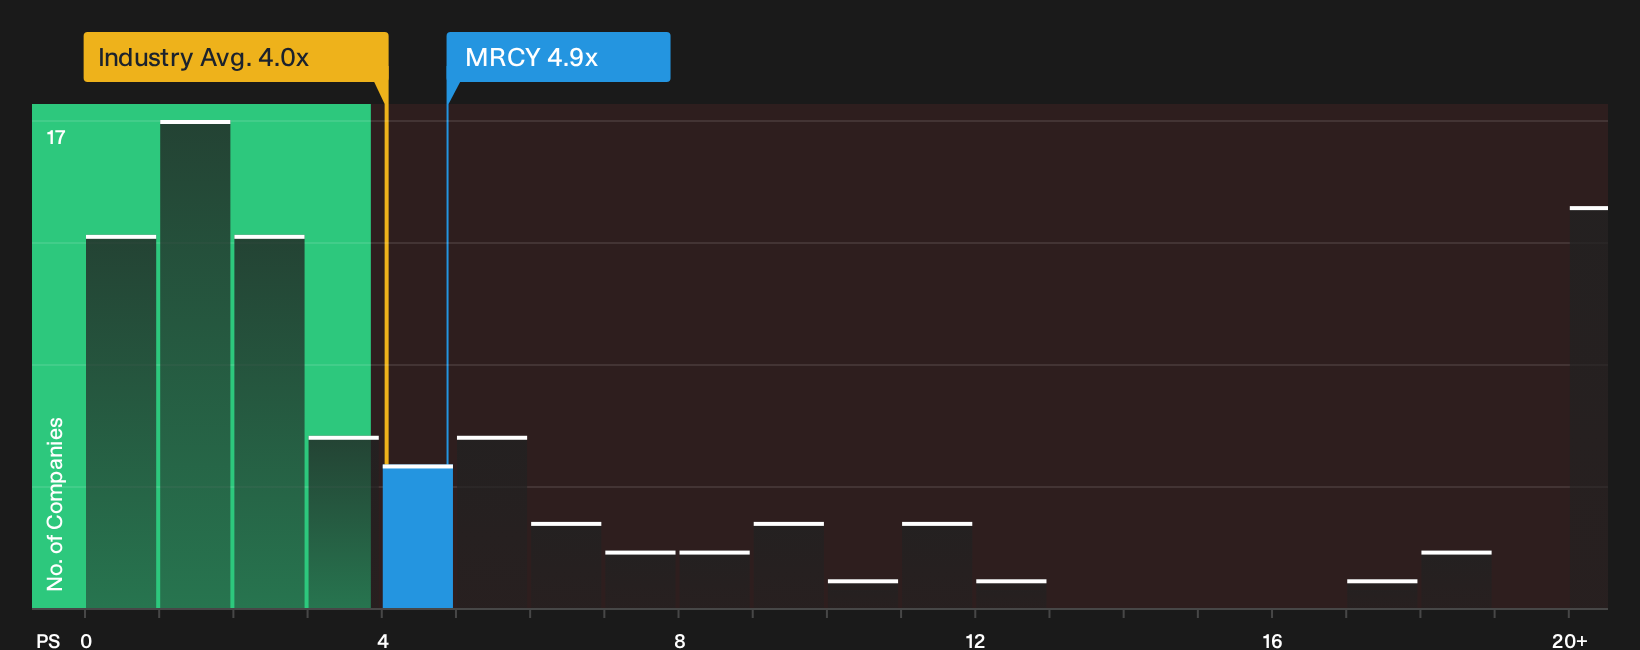
While the analyst narrative frames Mercury Systems as 31% undervalued on a fair value of $115.78, the current pricing on sales tells a tougher story. The stock trades on a P/S of 4.9x, versus a fair ratio of 1.9x and a US Aerospace & Defense average of 3.9x. That points to investors already paying a premium for each dollar of revenue, both against the wider sector and where the ratio could move toward, which raises the question of how much future improvement is already baked in.
To see what the numbers say about this price, run through the detailed valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Mercury Systems can feel confusing. Move quickly, review the key risk and upside drivers yourself, then weigh the 2 key rewards and 1 important warning sign.
Looking for more Mercury Systems style ideas?
If Mercury Systems has your attention, do not stop here. Use the same disciplined lens on other opportunities so you are not leaving potential returns on the table.
- Target potential mispricings by scanning a curated pool of quality companies that still look cheap on fundamentals through the 28 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on businesses with robust finances using the tailored 31 resilient stocks with low risk scores.
- Spot lesser known opportunities before they are crowded by reviewing the focused 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com