


Envista Holdings has delivered a mixed ride for shareholders, with the stock down sharply over 5 years but positive over the past 12 months. This puts a spotlight on whether the current US$23.00 share price is supported by its earnings power. With recent news highlighting solid revenue growth and profit expectations, a key issue for you is how much of that earnings story is already built into the valuation.
- The share price has fallen 40.6% over 5 years, which raises the question of whether the market has been too pessimistic about Envista Holdings' earnings profile or simply adjusting to what the business is actually producing.
- Recent reporting highlighted revenue growth and higher profit expectations, which can support the case for stronger earnings over time and influence how rich or conservative today's multiple looks against those prospects.
- The analysts covering Envista Holdings have run their own numbers. See what analysts think Envista Holdings's shares could be worth.
The stock's next move may depend on whether Envista Holdings' current earnings, relative to the Fair Ratio benchmark, make the recent share price level look well supported or demanding.
If you want to stress test the same earnings question you are asking of Envista Holdings across a wider group of companies, take a look at 28 high quality undervalued stocks
Is Envista Holdings Getting Expensive on Earnings?
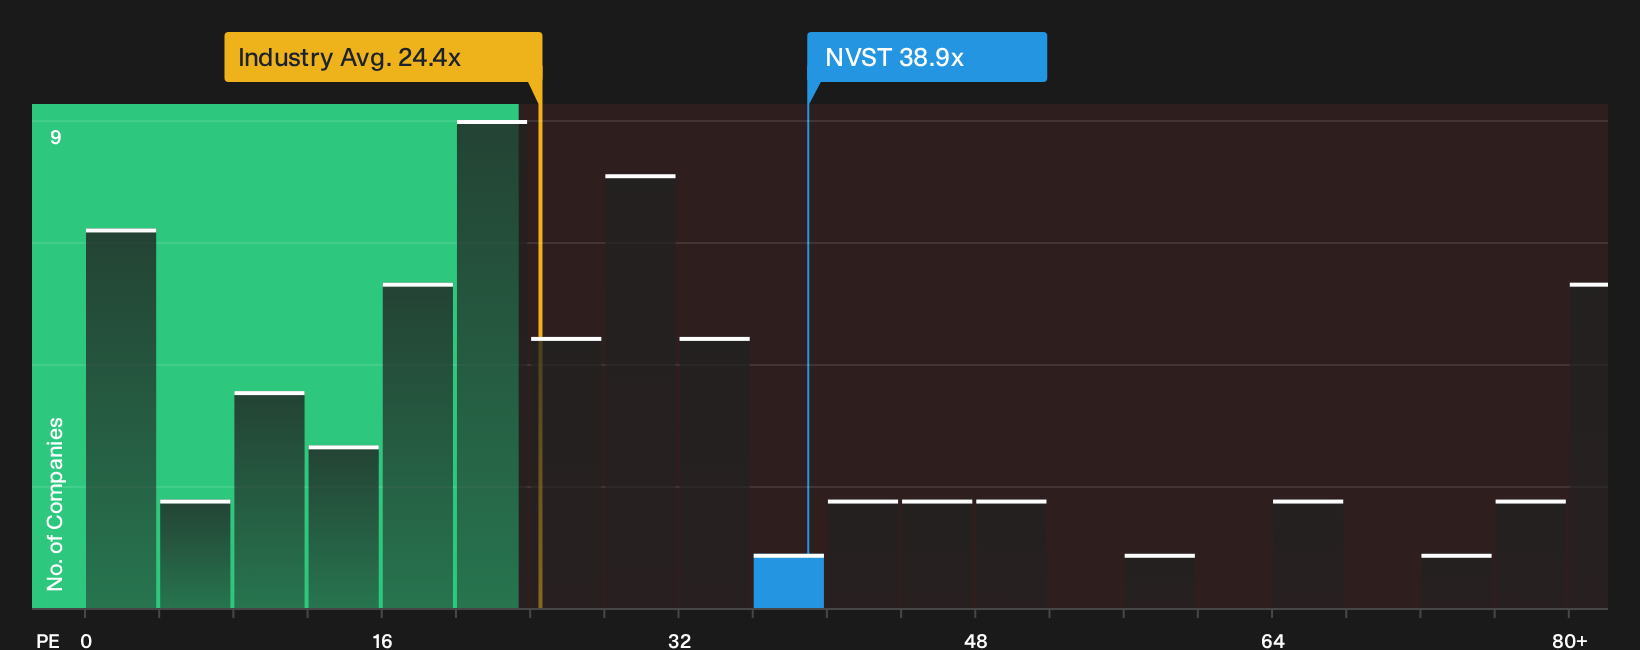
The P/E ratio is a useful anchor for Envista Holdings because earnings are a key focus for dental equipment investors after the recent results. Envista trades on a P/E of 38.9x, which is higher than both the Medical Equipment sector average of 24.4x and the peer group at 31.4x. That kind of premium means buyers today are paying a richer price for each dollar of current earnings than the typical stock in the same space.
Because the P/E that might be expected given Envista Holdings' growth profile, margins, size and risk comes out lower than the current level, the valuation screens as overvalued on this framework. Despite the strong Q2 where Envista beat revenue and EPS expectations, the latest share price still implies a fuller earnings multiple than those benchmarks support. This sets a high bar for future performance to keep the P/E from looking stretched. Explore the numbers behind Envista Holdings's P/E valuation.
The Envista Holdings Narrative: What Would Justify Today's Price?
Narratives for Envista Holdings pick up where the valuation question leaves off by spelling out which growth, margin and earnings paths would need to play out for the stock to be worth materially more or less than today’s price on Simply Wall St's Community page. Each narrative treats Envista Holdings' implied fair value as a thesis about the business that you can track over time, rather than a one off snapshot.
One of the top community narratives on Envista Holdings: roughly fairly valued
"This narrative explores a more pessimistic perspective on Envista Holdings compared to the consensus, based on a Fair Value that aligns with the bearish cohort of analysts..."
Discover why this Narrative puts Envista Holdings at roughly fairly valued.
For Envista Holdings, the sticker price is only half the story
Who actually runs Envista Holdings, how their incentives line up with ordinary shareholders and whether their rewards track results can matter as much as any P/E ratio you have just looked at. See who runs Envista Holdings and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com