


- Huntington Ingalls Industries recently secured a multiyear, approximately US$5.1b contract for the USS Harry S. Truman refueling and complex overhaul, advanced the John F. Kennedy carrier to preliminary acceptance, and won a U.S. Navy order for 10 ROMULUS unmanned surface vessels.
- These carrier milestones and unmanned vessel awards, together with a new Mission Technologies chief financial officer, sharpen focus on execution, capital intensity and long duration defense demand shaping Huntington Ingalls Industries' operating profile.
- We will now look at how Huntington Ingalls Industries' new carrier overhaul award could influence its broader investment narrative and risk profile.
Scan how Huntington Ingalls Industries fits into the wider defense build out by comparing it with hand picked 43 power grid technology and infrastructure stocks.
Huntington Ingalls Industries Investment Narrative Recap
To own Huntington Ingalls Industries, you need to believe its long cycle Navy programs, growing autonomous systems work and throughput efforts can turn a large backlog into steadier earnings and cash generation. The recent Truman refueling award, John F. Kennedy progress and ROMULUS win all reinforce revenue visibility. In the near term, the key swing factor remains whether 2026 free cash flow targets can be met without relying too heavily on late year advances and credits.
The biggest risk still sits in carrier execution at Newport News and estimate volatility on programs like CVN 80. New carrier milestones help sentiment but do not yet resolve build cadence concerns. In the short term, investors are likely to focus on each quarterly cash flow print and any signals that labor, supply chain and automation efforts are translating into more predictable margins.
The ROMULUS unmanned surface vessel contract looks most relevant for near term catalysts because it ties directly into throughput, mix and Mission Technologies execution. Moving from experimentation to fleet scale deployment gives Huntington Ingalls Industries a concrete production program where operational performance, partner coordination and campus expansion will quickly show up in segment results.
That award also sharpens the risk reward trade off. Successful delivery could support the case for Mission Technologies as a higher margin complement to shipbuilding, while any delays or cost issues would reinforce concerns about converting strong defense demand into durable profitability. For you as an investor, the practical question is how much weight to give this emerging unmanned portfolio versus the more mature but execution heavy carrier and submarine work.
Huntington Ingalls Industries is framed around analyst expectations that revenues reach US$15.3b and earnings reach US$963.2m by 2029, which implies 5.2% yearly revenue growth and an earnings increase of about US$302m from US$661.0m today.
Uncover how Huntington Ingalls Industries' fair value indicates a 39% potential upside to its current price before the market closes the gap.
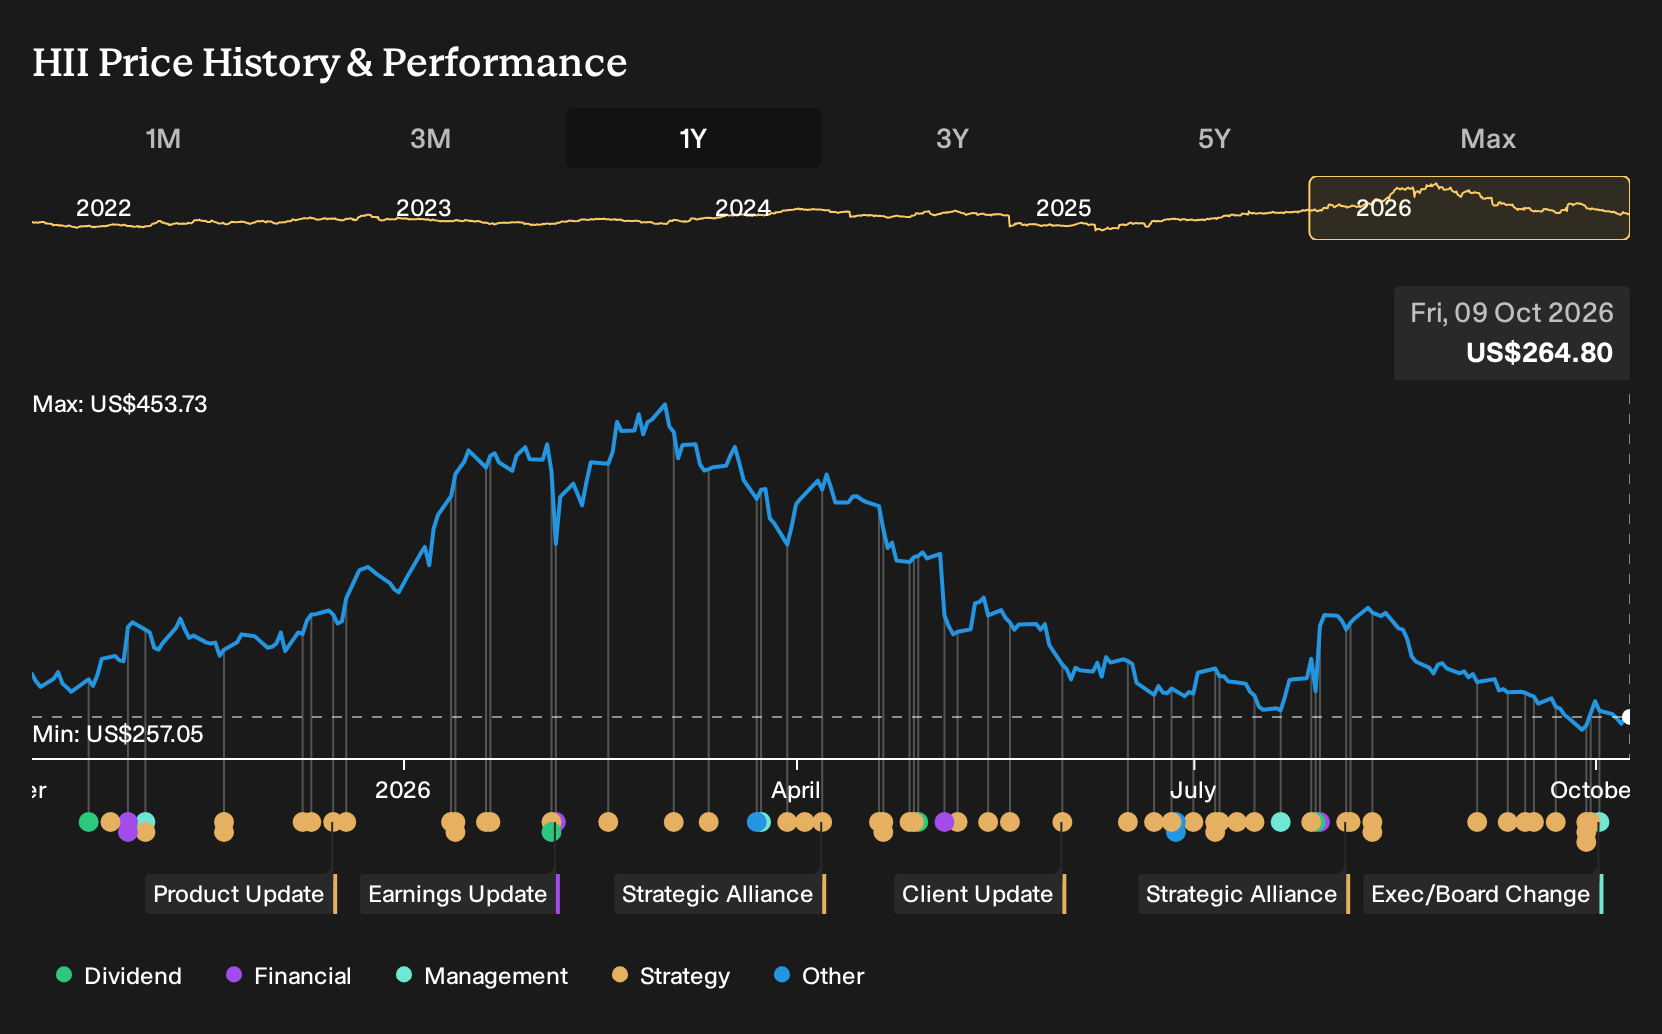
Exploring Other Perspectives
One alternate angle puts Mission Technologies execution risk at the center. The most cautious analysts, who were assuming Huntington Ingalls Industries only reaches about US$15.2b of revenue and US$887.0m of earnings by 2029, worry new contracts and a fresh CFO could still leave margins uneven. Views clearly differ. Compare both narratives before deciding how this latest news might reshape expectations.
Explore 4 other Huntington Ingalls Industries fair value estimates, including one that suggests it could be worth just $304.00.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Huntington Ingalls Industries research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Huntington Ingalls Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Huntington Ingalls Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Huntington Ingalls Industries?
Once you have a view on Huntington Ingalls Industries, it can help to cross check that thesis against other opportunities with different risk and income profiles. The Simply Wall St Screener gives you a way to move from a single stock story to a short list of candidates that fit the kind of portfolio you want to build.
- If capital preservation and smoother returns matter most to you, start with a set of 31 resilient stocks with low risk scores that score well on resilience and measured volatility.
- For investors who want quality at a measured entry point, there is a curated pool of 28 high quality undervalued stocks that combine fundamentals with what the model views as discounted pricing.
- If you are hunting for less crowded stories with solid underpinnings, scan through a group of 20 high quality undiscovered gems that filter for strong financial traits outside the usual spotlight.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com