


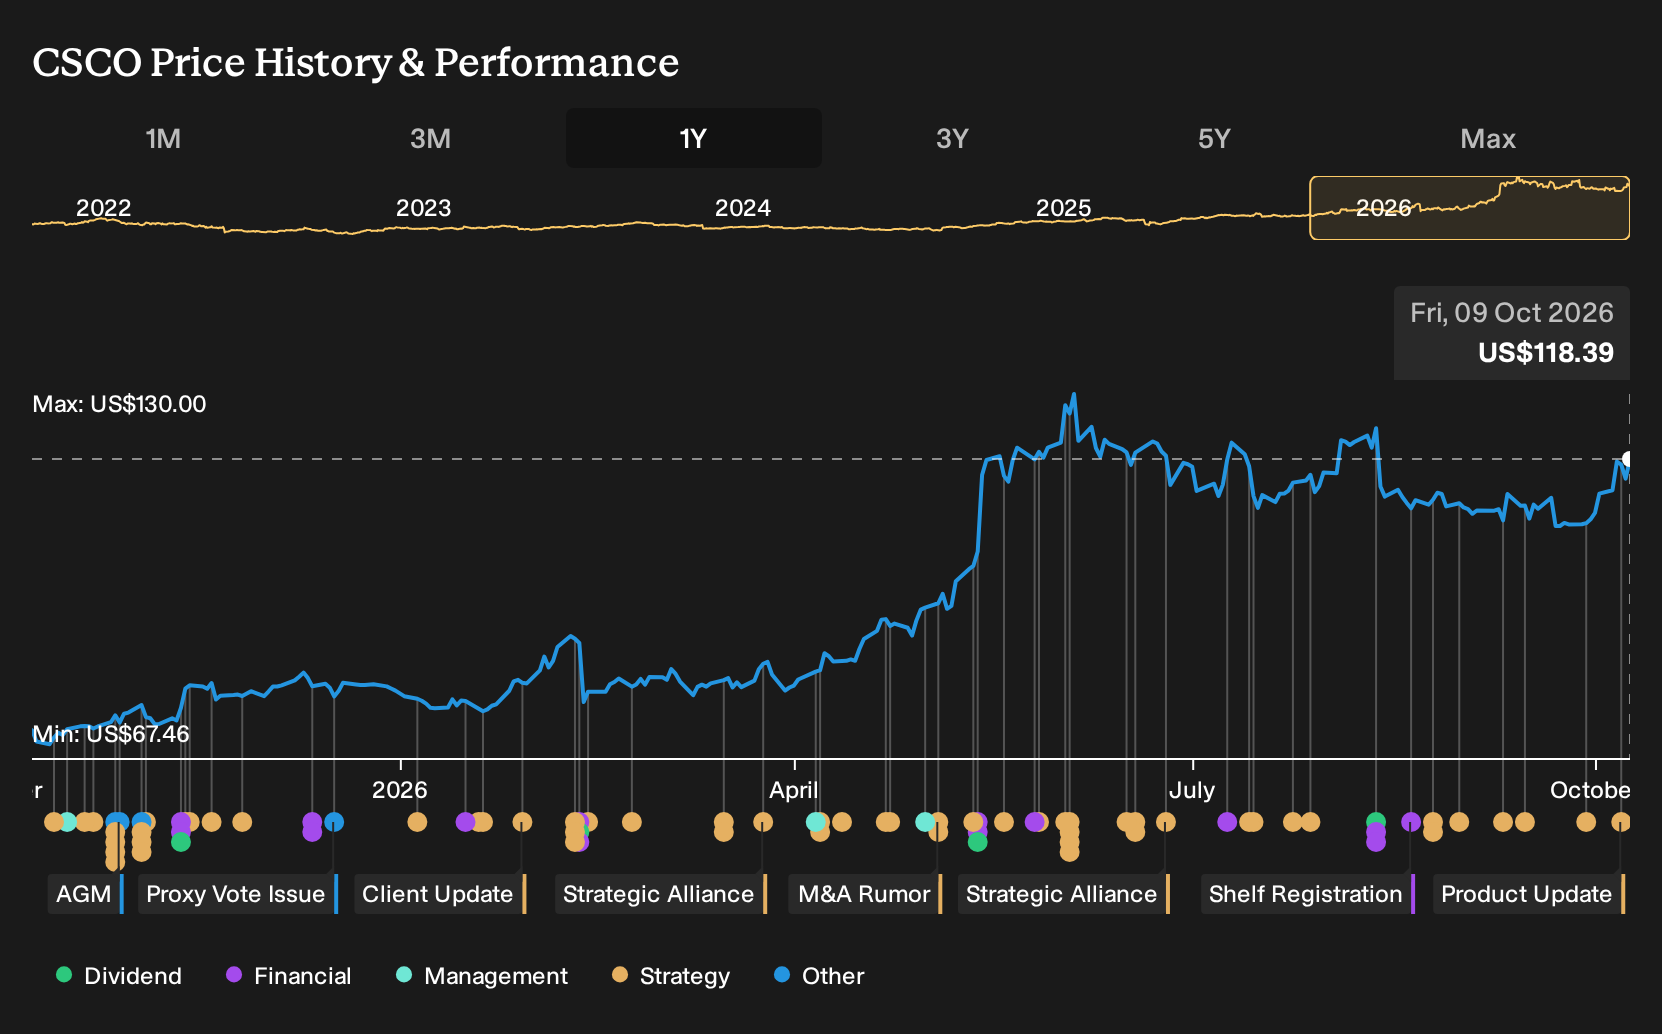
- Cisco Systems recently introduced a wide suite of AI driven collaboration, workplace management and customer engagement products, and added industrial AI leader Girish Rishi to its board in October 2026.
- Together with a new sovereign AI infrastructure collaboration with Bell Canada, these moves indicate Cisco Systems is placing greater emphasis on AI centric networking, security and data workloads across both hyperscale and regulated customers.
- We will now examine how Cisco Systems expanding AI focused product set and infrastructure partnerships could influence the existing investment narrative.
Scan how Cisco Systems fits into the broader AI infrastructure story by comparing it with a hand picked set of 92 AI infrastructure stocks.
Cisco Systems Investment Narrative Recap
To own Cisco Systems today, you need to believe the firm can turn its AI centric networking, security and collaboration push into steady demand from hyperscalers, enterprises and governments while keeping operating margins resilient despite known gross margin pressure from a heavier hardware mix and higher memory costs. The key near term swing factor is how smoothly those large AI infrastructure orders convert into revenue without eroding profitability.
The biggest risk remains that rising hardware intensity and any security related trust issues blunt the benefit of that demand. The recent board appointment does not materially change the near term earnings or margin story, although stronger AI and industrial data experience in the boardroom can help oversight as Cisco Systems leans harder into complex AI workloads.
The Bell Canada memorandum of understanding on sovereign AI infrastructure is the announcement that most directly connects to this AI heavy product and governance shift. It sits directly on the core thesis that Cisco Systems can supply secure, high performance networking and observability for sensitive AI workloads in regulated environments, not just for global hyperscalers.
If that collaboration moves from framework to scaled deployments, it can support the existing catalyst of US$9.3b in hyperscale AI orders by broadening AI infrastructure revenue beyond a handful of very large customers. Execution risk is real, though. Modular AI POD deployments, strict security requirements and potential cyber threats to critical routers all mean Cisco Systems still has to prove it can deliver complex, sovereign ready infrastructure at scale without fresh margin or trust setbacks.
Cisco Systems analysts are currently working off a narrative that points to US$83.4b in revenue and US$20.1b in earnings by 2029. This is based on an assumption of 9.6% yearly revenue growth and an earnings increase of about US$6.8b from US$13.3b today.
Uncover why Cisco Systems' fair value indicates a 16% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic Cisco Systems analysts already had a different angle. They viewed hyperscaler AI demand and security expansion as strong enough to support revenue rising about 12.7% a year and earnings reaching roughly US$23.0b by 2029. Board and product news like this could shift those views further, which is why you should compare several narratives before deciding what feels reasonable.
Explore 4 other Cisco Systems fair value estimates, including one that indicates potential upside of as much as 16% from the current price.
Decide For Yourself
Don’t just follow the ticker. Dig into the data and build a conviction that’s truly your own.
- A great starting point for your Cisco Systems research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Cisco Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cisco Systems’ overall financial health at a glance.
Looking For More Ideas Beyond Cisco Systems?
If you want to stress test your Cisco Systems thesis against other opportunities, the Simply Wall St Screener can help you line up similar or contrasting profiles side by side so your capital is not riding on a single story.
- If you prioritize companies with strong fundamentals and less fragile finances, start by scanning a list of solid balance sheet and fundamentals (25 results) that can serve as potential anchors in a diversified portfolio.
- If resilience matters more to you than excitement, filter for 31 resilient stocks with low risk scores that may offer a calmer ride when markets turn choppy.
- If you are hunting for future leaders before the wider market catches on, compare Cisco Systems with a 20 high quality undiscovered gems that already show quality in their numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com