


Gildan Activewear has had a choppy share price path, yet the real question for investors is whether the current tag at around US$59.82 is in line with what its earnings support. Recent legal headlines and a mixed return profile have pushed the conversation away from short term swings and toward what the business is genuinely earning for each share.
- Over the past 3 years the stock has returned 58.4%, which puts real pressure on the idea that the underlying earnings power has kept pace with the share price.
- Fresh scrutiny from short seller allegations and a securities class action may influence how reliable investors judge Gildan Activewear's reported profits to be, which can feed directly into what P/E multiple they are willing to pay.
- The analysts covering Gildan Activewear have run their own numbers. See what analysts think Gildan Activewear's shares could be worth.
The issue now is whether Gildan Activewear's present market value is justified by the level and quality of the earnings it is generating today.
If this kind of earnings focused story around Gildan Activewear has your attention, a targeted stock screen is a useful next step for research. You can start with 9 high quality undervalued stocks.
Is Gildan Activewear Fairly Priced on Earnings?
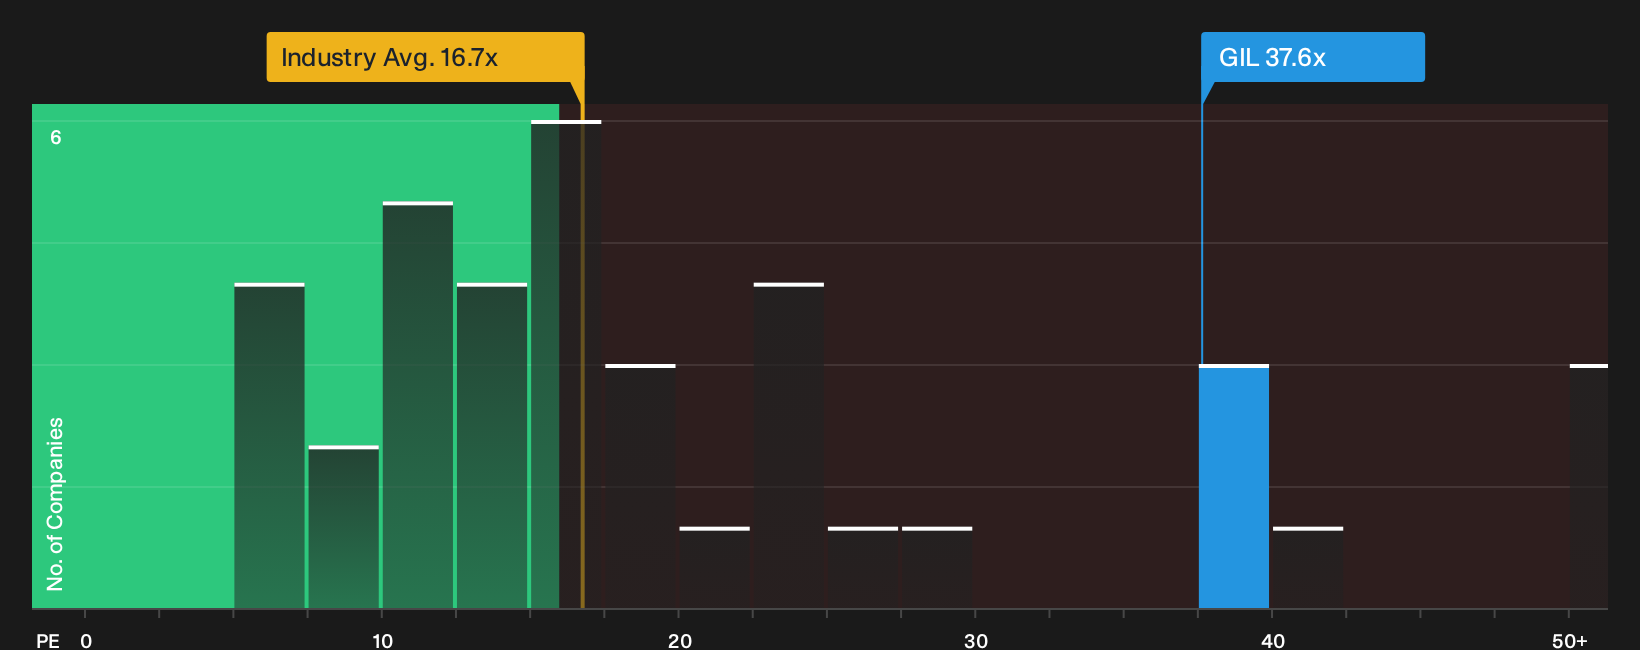
The P/E ratio works well for Gildan Activewear because earnings are a central focus of the current debate around the stock. At roughly 37.6x earnings, Gildan trades above both the peer group on about 29.7x and the broader luxury industry on about 15.8x. That premium means buyers today are paying more for each dollar of profit than is typical across comparable apparel businesses.
The fair P/E level implied by the valuation framework sits close to where Gildan Activewear currently trades, so the market price is broadly in line with what this model suggests for its earnings profile. Because the securities class action and short seller allegations directly question the quality of those profits, this kind of near fair P/E still leaves plenty of work for you to judge whether the earnings base feels solid enough to justify it. Explore the numbers behind Gildan Activewear's P/E valuation.
The Gildan Activewear Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Gildan Activewear leaves off by spelling out which combinations of future growth, profitability and earnings outcomes would need to hold for the share price to sit meaningfully above or below where it trades today. Each narrative sets out Gildan Activewear's implied fair value as a specific, testable view on the business so you can watch how that expectation holds up over time on the Community page.
One of the top community narratives on Gildan Activewear: 11% undervalued
"Rising labor costs and increasing volatility in global manufacturing hubs, particularly in Bangladesh and Central America, could significantly erode Gildan's low-cost sourcing advantage..."
Discover why this Narrative puts Gildan Activewear at 11% undervalued.
The open question for Gildan Activewear, what do experts think comes next
Valuation only tells you what the market is paying today, while the analysts covering Gildan Activewear have already mapped out where they expect the business to be a few years from now. Explore where analysts expect Gildan Activewear to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com