


Power Integrations has seen its share price move around sharply in recent years, which puts fresh attention on a simple question for anyone looking at the stock today. Is the current valuation supported by the earnings the business is generating right now and what investors expect it to earn in the future.
- The share price has fallen 46.9% over the past 5 years, so the long term slide makes the link between Power Integrations' earnings and today’s market value especially important for investors who are either holding on or thinking about starting a position.
- The company’s focus on power-efficient semiconductor solutions can influence how steadily it converts revenue into profit, which in turn feeds directly into how much investors might be prepared to pay for each dollar of earnings.
- Your read on Power Integrations is one view; the desks covering it have another. See what analysts think Power Integrations's shares could be worth.
The issue now is whether the current share price around US$49 aligns with what Power Integrations is actually earning, based on the earnings multiple the market is applying.
If you want a clearer benchmark for what you are paying for earnings, compare Power Integrations with other stocks screened on valuation using 30 high quality undervalued stocks
.Has Power Integrations Run Too Far on Earnings?
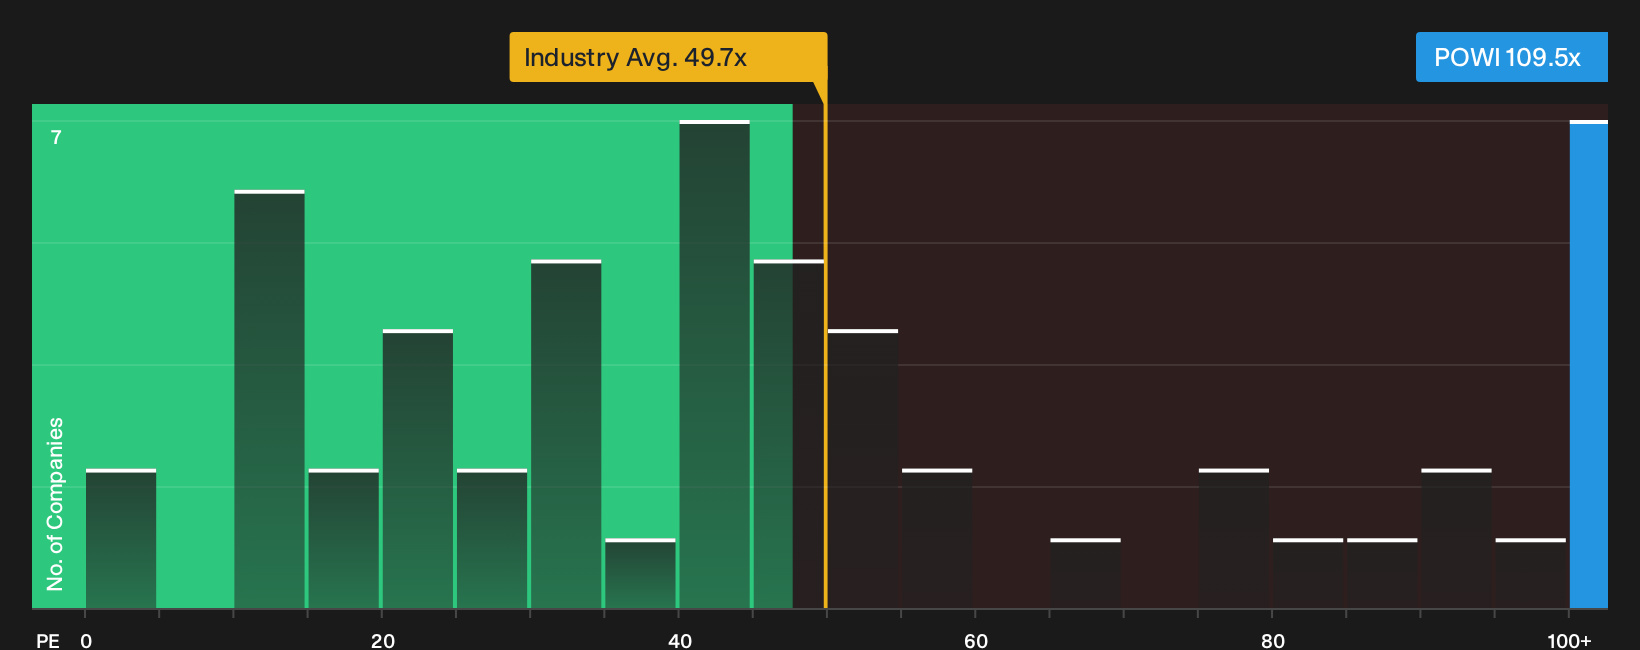
The P/E ratio suits Power Integrations because investors often look at this business through the lens of what they are paying for each dollar of current earnings. At a P/E of about 109.5x, the stock trades at more than double the broader semiconductor sector average of roughly 49.7x and sits well above peers around 40.0x. That kind of premium means the market is attaching a high price to the company’s earnings stream today.
The tailored fair multiple from the valuation model, which factors in Power Integrations’ profitability profile, industry context and risk, comes in below where the shares trade. Since the current P/E stands materially higher than that fair yardstick, the stock screens as overvalued on this measure, and anyone considering it needs to be comfortable paying a rich price for every dollar of earnings. Explore the numbers behind Power Integrations's P/E valuation.
The Power Integrations Narrative: What Would Justify Today's Price?
Narratives for Power Integrations sit on Simply Wall St's Community page and act as the missing link between today’s rich P/E multiple and the future path of growth, margins and earnings implied by that price. Instead of giving a single output from a ratio or model, they lay out the business future that figure relies on, so you can watch how the real world lines up with it over time.
One of the top community narratives on Power Integrations: 37% undervalued
"AI data center power opportunities, including auxiliary supplies for NVIDIA’s 800 V racks using 1,700 V InnoMux-2 ICs and a longer-term path into the main GPU power stage…"
Discover why this Narrative puts Power Integrations at 37% undervalued.
One more Power Integrations check that belongs next to the valuation work
Price, earnings and even growth stories only get you so far if you have not looked at who is steering Power Integrations and how their incentives are structured. See who runs Power Integrations and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com