


Camden Property Trust (CPT) has drawn fresh attention after recent trading left the stock down about 5% over the past month and roughly 15% over the past 3 months. That move raises questions about how investors are weighing this US apartment-focused REIT today.
Despite the recent slide, shorter term trading has steadied a little, with a 1-day share price return of 0.85% and a 7-day share price return of 1.69% from a last close of US$97.58. The bigger picture still points to fading momentum, as the 30-day and 90-day share price returns are down 5.27% and 14.55% respectively. The 1-year total shareholder return is roughly flat at a decline of 0.02%, while the 3-year total shareholder return is 13.61% and the 5-year total shareholder return is down 25.62%.
Compare Camden Property Trust’s recent pullback with a curated 30 high quality undervalued stocks that have stronger balance sheets and cash flows, yet are still priced as if the market is uncertain about them.
After a 3 month slide and a flat 1 year total return, Camden Property Trust now sits at a different starting line. Does that reset skew the risk reward toward buyers, or still argue for caution as the valuation math comes into focus?
Most Popular Narrative: 16% Undervalued
Against a last close of $97.58, the most followed narrative pegs Camden Property Trust’s fair value at about $116. This implies a meaningful gap that hinges on how supply, capital recycling, and Sunbelt demand trends play out.
Supply additions in Camden Property Trust’s markets peaked around late 2024 and are now declining, with projected completions in 2027 and 2028 below the long-term average and deliveries in its markets expected to fall from about 200,000 units in 2025 to about 120,000 by 2028, which can improve pricing power and support revenue and NOI growth.
See why 11 investors see Camden Property Trust as 16% undervalued.
Result: Fair Value of $116.10 (UNDERVALUED)
Still, Camden Property Trust’s heavy Sunbelt exposure and analyst expectations for profit margins to fall from 20.6% to 2.9% leave the narrative exposed.
Find out about the key risks to this Camden Property Trust narrative.
Another View: Camden Property Trust Through The P/E Lens
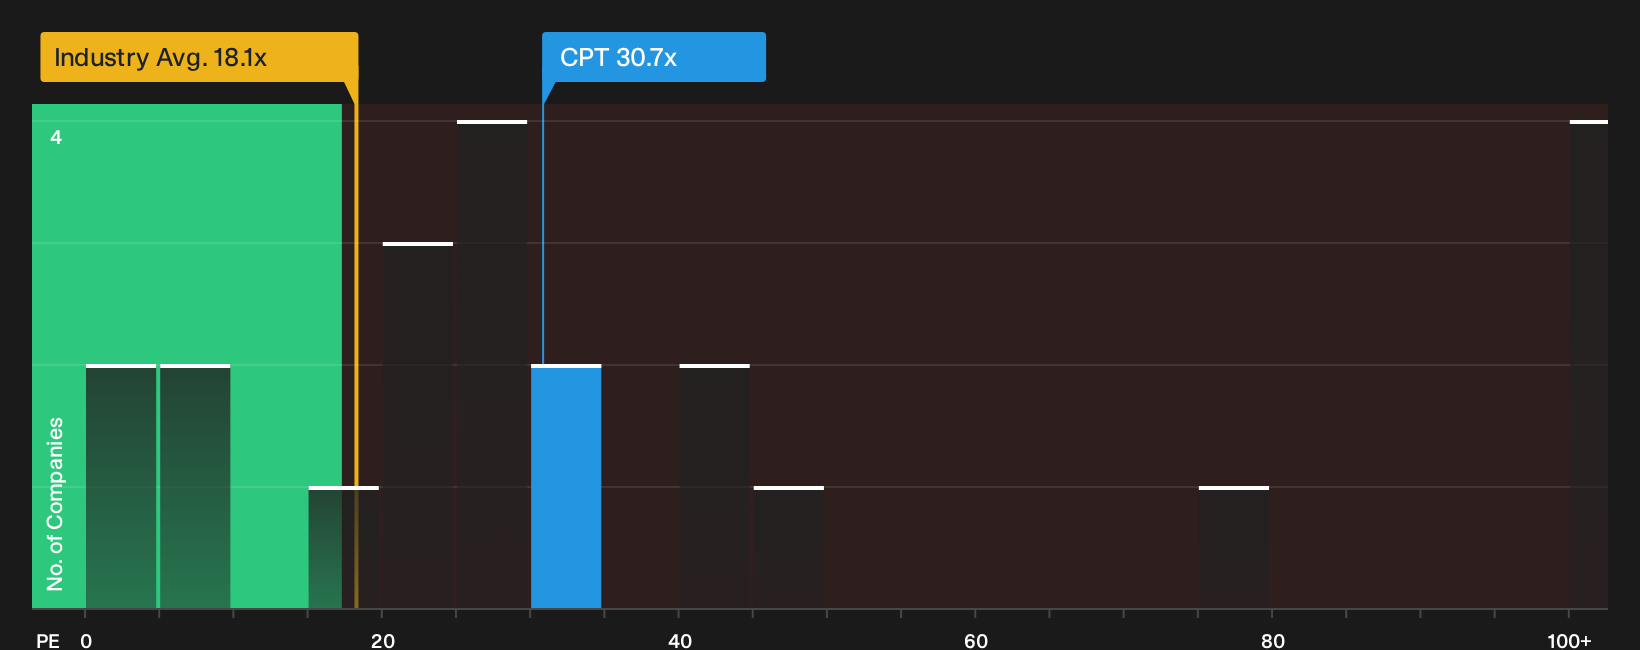
On one hand, Camden Property Trust screens as roughly 28.1% below an internal fair value estimate. On the other, the stock trades on a P/E of 30.7x, which is richer than both the global Residential REITs industry at 18.1x and a fair ratio of 15.2x that the market could move toward.
A higher P/E than peers can sometimes be earned by strong execution, but it also raises the risk that any disappointment in Sunbelt demand, NOI trends, or FFO per share leaves less room for error on the current tag. Which side of that trade off do you think dominates from here?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Camden Property Trust so far. If you want to move quickly and base your stance on the numbers, weigh both sides with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Camden Property Trust?
If Camden Property Trust has your attention, do not stop here. Use the same disciplined lens across other opportunities where pricing, quality, and risk can look very different.
- Target potential mispricings by scanning a 30 high quality undervalued stocks that match solid fundamentals with market skepticism.
- Build a steadier income stream by focusing on a 8 dividend fortresses that combine high yields with resilient payout histories.
- Prioritise resilience first by filtering for a 31 resilient stocks with low risk scores that score well on balance sheet strength and earnings stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com