


ASML Holding has delivered powerful share price gains in recent years, which puts a sharp spotlight on whether the current valuation can still be explained by the earnings that support it. With the stock now closely watched after a strong run, the core question for you is how much of the semiconductor story is already embedded in today’s price.
- Over the past 3 years the stock has gained 203.2%, so a lot of future profit expectations may already be wrapped into the market’s view of ASML.
- Recent updates around Extreme Ultraviolet and High-NA tools, together with ongoing AI related chip demand and export controls to China, can influence how reliably investors expect ASML to convert its technological position into sustained earnings power.
- There is a second opinion on ASML Holding worth weighing. See what analysts think ASML Holding's shares could be worth.
The issue now is whether ASML’s current share price is adequately supported by the earnings it is generating today and those investors reasonably expect in the years ahead.
If you want more context around whether ASML Holding’s earnings driven run still stacks up, it can help to compare it with other chip related opportunities in 92 AI infrastructure stocks.
Is ASML Holding Getting Expensive on Earnings?
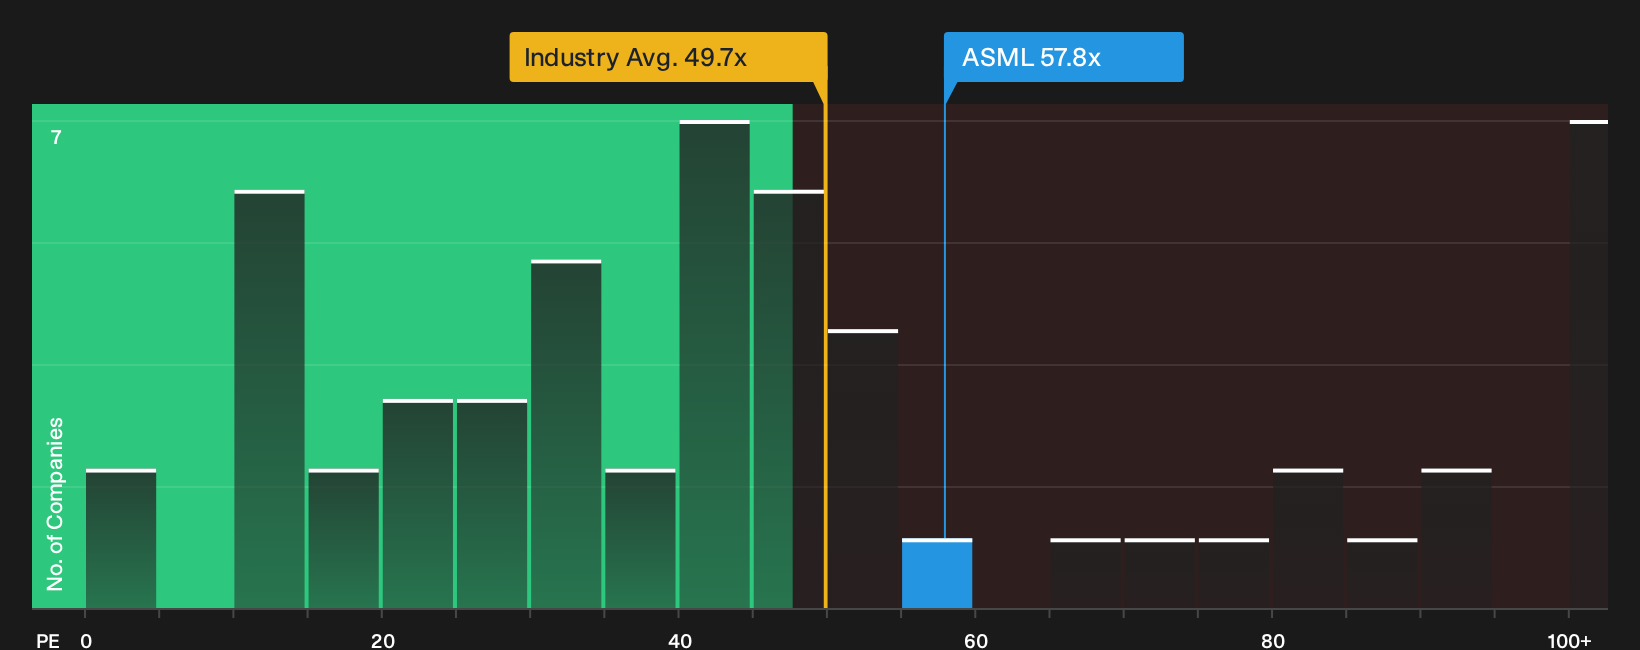
The P/E ratio suits ASML Holding because earnings remain the main yardstick investors use to weigh the value of a mature equipment supplier. On this measure, the stock trades on about 57.8x earnings, which is higher than the wider semiconductor sector on roughly 49.7x and also above the peer group around 51.5x. That places ASML on a premium multiple versus both its broader industry and closer comparables.
The Fair Ratio model, which blends factors such as growth expectations, profitability, market size and risk, points to a lower P/E than where ASML trades today, so the current level screens as overvalued on this framework. Despite robust recent commentary around AI driven capex and High-NA EUV demand, the price already assigns a richer earnings tag than these benchmarks imply. For anyone considering the stock now, the key question is whether ASML’s future earnings profile can justify paying above both industry and Fair Ratio reference points. Explore the numbers behind ASML Holding's P/E valuation.
The ASML Holding Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for ASML Holding pick up exactly where this valuation puzzle leaves you. They spell out which future paths for growth, margins and earnings would need to play out for the stock to be worth materially more or materially less than it trades for today on the market. Each scenario links a specific set of potential catalysts and risks to an implied fair value, so you can track over time which version of ASML Holding's story is gaining traction.
A written, number driven narrative on ASML Holding helps you clarify your views on topics such as AI linked capital expenditure, High-NA EUV rollouts and the impact of China export controls. You can then see in black and white how that view holds up as fresh results and policy decisions arrive. Instead of reacting headline by headline, you get a concrete earnings and valuation roadmap that can be updated as new data on margins, orders and guidance comes through.
Share your own Narrative for ASML Holding and set out the assumptions behind your valuation.
Before you act on ASML Holding's valuation, there is one more piece to check
Price, profits and tools only tell part of the story for ASML Holding, because the people steering the business and how their rewards are structured can tilt long term outcomes in very different directions. See who runs ASML Holding and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com