


Flowserve (FLS) is back in focus after a recent move in its share price, with the stock last closing at US$72.28. That shift invites a closer look at how the business now lines up.
For Flowserve, a 3.78% 1 day share price gain comes after a softer patch, with 7 day and 30 day share price returns both slightly in the red. Yet the 1 year total shareholder return of 48.99% and 5 year total shareholder return of 115.04% point to momentum that has been building rather than fading.
Scan for other industrials showing similar momentum to Flowserve by reviewing the hand picked list of solid balance sheet and fundamentals (25 results) in the same corner of the market.
For a stock that has added 49% over the past year yet just pulled back over the last month, the real puzzle with Flowserve now is whether the meaningful upside sits ahead of investors or behind them as valuation gets tested next.
Most Popular Narrative: 19% Undervalued
On the most followed valuation framework, Flowserve screens as undervalued, with a fair value of $89.00 against the last close at $72.28. This comparison puts the recent share price pullback into a different light for anyone weighing what comes next.
Ongoing work under the Flowserve Business System, including 80/20 portfolio actions, footprint realignment and commercial discipline, is aimed at pushing adjusted operating margin from the roughly 16% expected in 2026 toward the stated 20% target for 2030. This would directly support earnings and free cash flow.
See why 34 investors see Flowserve as 19% undervalued.
Result: Fair Value of $89.00 (UNDERVALUED)
Still, the Flowserve story carries real pressure points if Middle East disruptions persist or if margin work and aftermarket bookings fall short of current expectations.
Find out about the key risks to this Flowserve narrative.
Another Angle On Flowserve’s Valuation
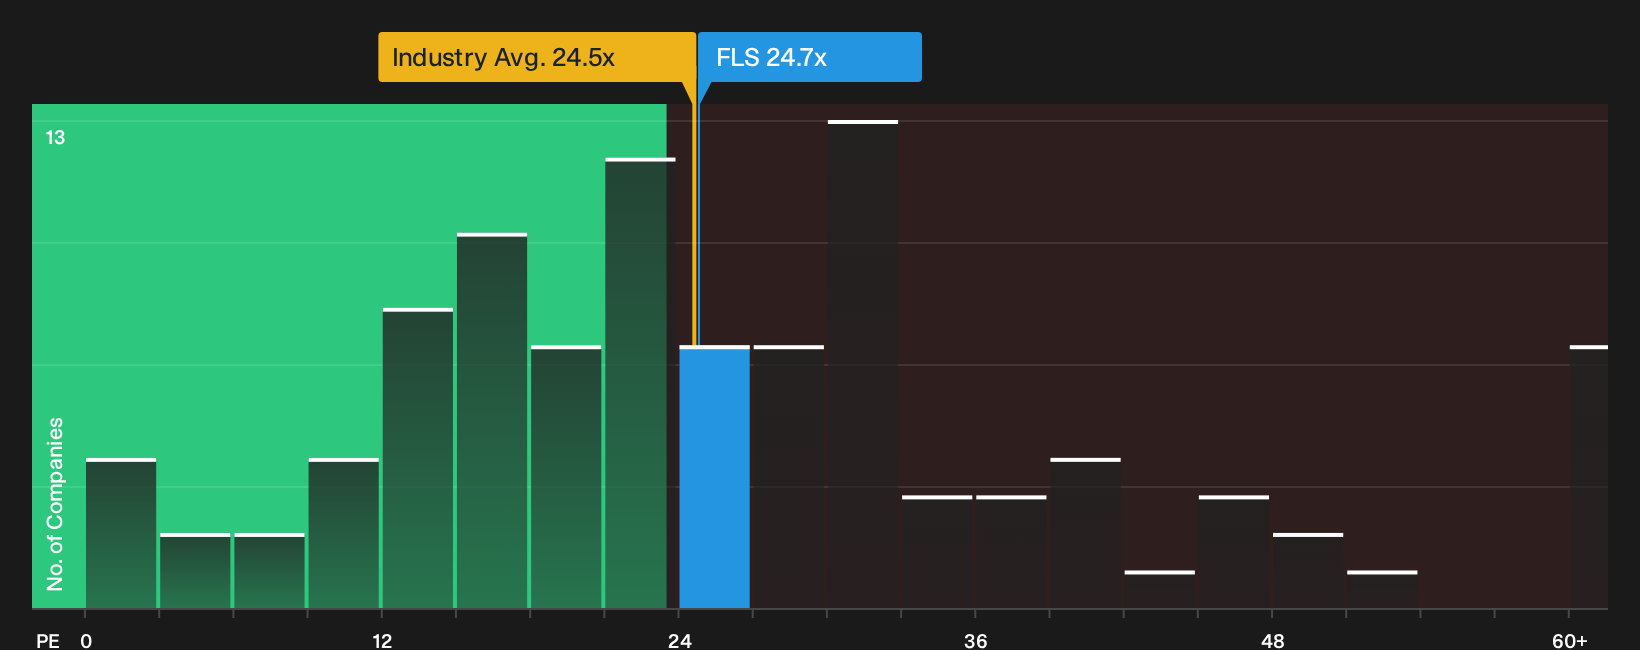
That 19% undershoot to fair value tells one story. The current P/E of 24.7x versus the US Machinery average of 24.5x and peer average of 24.1x tells another, especially when the fair ratio sits higher at 31.9x. Is the market underestimating execution risk or leaving room for upside?
To unpack what those earnings multiples might mean in practice, and how they compare with similar industrial stocks, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Flowserve's valuation and risk profile can pull opinions in opposite directions, so move quickly, test the data yourself, and weigh both sides using the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Flowserve?
If Flowserve has sharpened your interest, do not stop here. Broader context helps you judge opportunities, manage risk, and spot patterns the headline misses.
- Target resilient potential by reviewing companies with stronger balance sheets and fundamentals through the list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at a reasonable price by scanning the 29 high quality undervalued stocks that meet strict cash flow and balance sheet filters.
- Build income focused exposure by checking out the 8 dividend fortresses that combine higher yields with a focus on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com