


- BOK Financial has recently recorded a streak of earnings beats, surpassing estimates by an average of 6.67% over the last two reported quarters, with its next results scheduled for October 19, 2026.
- The pattern of outperforming expectations, together with a positive Earnings ESP, highlights how BOK Financial’s current operating setup is translating into stronger than modeled profitability.
- We will look at how BOK Financial's earnings beat streak and positive Earnings ESP reshape the broader investment narrative around execution.
See how BOK Financial's earnings momentum compares with other financially solid regional players by checking the hand-picked list of solid balance sheet and fundamentals (25 results) in the same bracket.
BOK Financial Investment Narrative Recap
To own BOK Financial, you need to be comfortable with a regional bank leaning on a mix of fee income and broad based lending, and with credit quality remaining disciplined. The recent pattern of earnings beats, averaging 6.67% above estimates in the last two quarters, points to an operating setup that is currently running ahead of external models rather than redefining the story.
The key near term swing factor is still management’s ability to grow core C&I and specialty lending while keeping losses in check, especially in commercial real estate and energy. The biggest risk remains a sector specific downturn in those books or a renewed squeeze on net interest income, and the recent results do not materially change that trade off.
With no fresh corporate announcements tied directly to this earnings run, the most relevant reference point remains management’s earlier focus on expanding fee based businesses and building out the mortgage finance warehouse platform. That platform has already reached US$452 million in outstandings and US$870 million in commitments by Q2 2026. That push matters because roughly 38% of 2025 revenue is projected to come from fees, which can help smooth performance when margins on lending come under pressure.
For you as a shareholder, the link to the latest earnings beats is execution. If BOK Financial keeps scaling areas like wealth management and mortgage warehouse while preserving credit quality and a P/E that screens as good value versus peers at 11.8x against 14.1x, then the recent momentum simply reinforces that the existing catalysts, rather than new ones, are still the ones to watch.
BOK Financial's current earnings are reported at US$646.9 million, and analysts see revenue rising by 4.4% each year. Forecasts point to US$2.6 billion of revenue and US$663.6 million of earnings by 2029, which implies an earnings increase of about US$16.7 million from today.
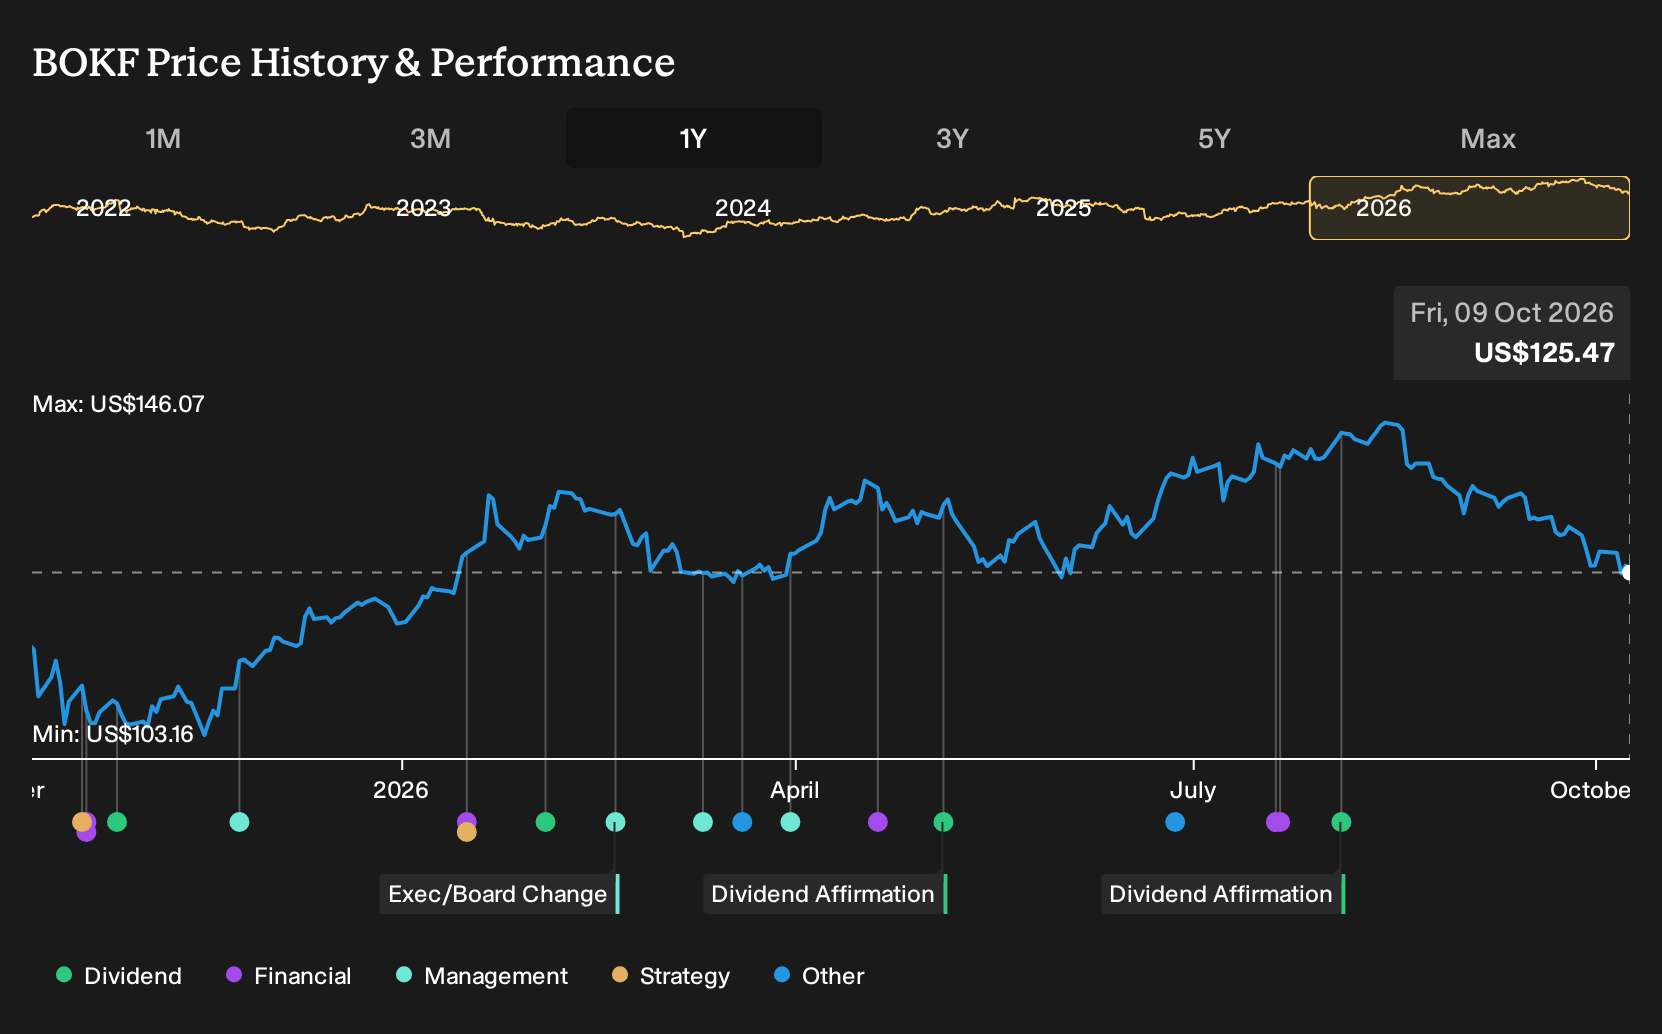
Discover why BOK Financial's fair value indicates a 20% potential upside to its current price, an opportunity that could narrow quickly.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your BOK Financial research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for BOK Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BOK Financial's overall financial health at a glance.
Looking for more investment ideas beyond BOK Financial?
If the BOK Financial story has you thinking about portfolio upgrades, it can help to line it up against other companies with clear financial traits, whether that is income potential, balance sheet strength, or a focus on value.
- For investors who want income to do more of the heavy lifting, review a curated group of higher yielding stocks screened as 8 dividend fortresses that may suit a dividend focused approach.
- If risk control comes first for you, scan through a carefully filtered universe of 31 resilient stocks with low risk scores to see which businesses align with a more defensive playbook.
- For those hunting for quality at a sensible entry point, compare BOK Financial with a broader pool of 29 high quality undervalued stocks that currently screen as compelling on both fundamentals and pricing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com