


GSK has delivered a solid multi year return, and with the stock recently closing at £17.50, the live question for you is whether that price still lines up with what the business is earning.
- Over the past 5 years GSK shares have gained 51.8%, which puts real weight on the issue of whether current earnings can carry that kind of share price performance.
- Fresh trial results for HIV therapy Cabenuva and ongoing work on the B7H3 cancer programme can shift expectations for future profit growth and cash generation, which feeds directly into how much investors may be willing to pay for each pound of earnings.
- The analysts covering GSK have run their own numbers. See what analysts think GSK's shares could be worth.
The stock's next move may depend on whether GSK's recent price is well supported by the earnings it is generating today.
If you are weighing GSK against other opportunities built on earnings power, it can help to compare it with 7 high quality undervalued stocks.
Does GSK Look Undervalued on Earnings?
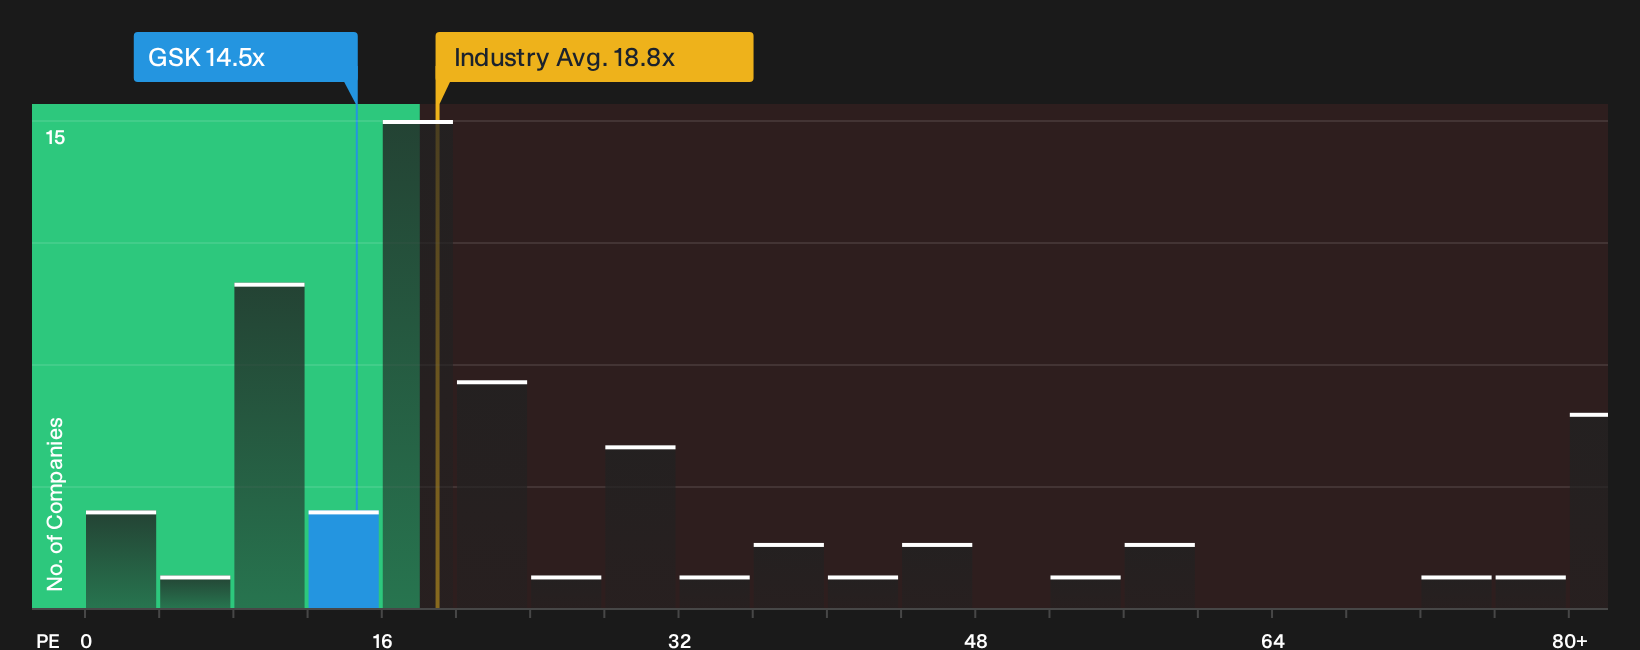
The P/E ratio is a useful lens here because GSK is an earnings focused pharmaceutical group where profit tends to anchor long term valuation. On current numbers, the stock trades on a P/E of about 14.5x, which is below the wider pharmaceuticals industry average of roughly 21.8x and also under the peer group mark of about 46.2x. That gap means you are paying less per pound of reported profit for GSK than for many similar drug makers.
The fair value model, which blends GSK specific factors like margins, growth assumptions, risk profile and size, points to a higher P/E than where the shares change hands today. Because of that, the current earnings multiple lines up more closely with an undervalued profile on this framework, even after the positive Cabenuva trial update and interest in the B7H3 cancer programme. If you think the underlying earnings base is durable, the present discount on this metric could matter for your long term return expectations. Explore the numbers behind GSK's P/E valuation.
The GSK Narrative: What Would Justify Today's Price?
GSK Narratives on Simply Wall St pick up where the P/E puzzle leaves off by explaining which future paths for revenue growth, profit margins and earnings power would need to occur for the share price to appear meaningfully higher or lower from here on a fundamental view. Where a single ratio or fair value model gives one number, these frameworks unpack the set of assumptions behind it so you can later judge whether GSK's actual progress is tracking that story or drifting away from it.
Community views on GSK are split between those who see the pipeline and cost savings story as underappreciated and those who think recent setbacks already test the valuation.
Bull case: 19% undervalued
"The current valuation implies investors are not fully crediting GSK for its stated >£40b 2031 sales outlook and the potential upside from oncology and long acting injectables…"
Discover why this Narrative puts GSK at 19% undervalued.
Bear case: 20% overvalued
"Although GSK is pushing hard to lift its specialty medicines mix, the 9% decline in General Medicines sales in Q2 and the downgrade to full year guidance indicate structural pressure from aging brands and generic competition that could drag on revenue and dilute the margin uplift expected from higher priced therapies…"
Explore why this Narrative puts GSK at 20% overvalued.
One more GSK angle worth checking before you move on
Everything so far has focused on what GSK looks like today, but there is a separate piece that matters just as much: how professional analysts currently map out this business a few years from now. Explore where analysts expect GSK to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com