


Why Alcon’s New Systane Launch Matters For Investors
Alcon (SWX:ALC) has just rolled out Systane PRO Preservative-Free in Canada, a new dry eye drop that targets a large, clinically recognised pool of dry eye disease patients.
The launch highlights how the eye care specialist continues to develop products within its Vision Care segment. It also gives investors a fresh data point to watch as the Systane franchise expands geographically.
Recent news has arrived against a weak backdrop for the stock, with Alcon’s share price at CHF53.14 and a year-to-date share price return down 16.37%, while the 1-year total shareholder return has declined 8.12% and the 5-year total shareholder return is down 25.42%. This suggests sentiment has cooled even as the new Systane launch gives investors a fresh reason to reassess future growth and risk.
Scan how Alcon compares with other eyecare and healthcare stocks that could be setting up for the next move using our curated list of list of solid balance sheet and fundamentals (204 results).
Alcon’s share price has pulled back while both analyst targets and intrinsic value estimates sit materially higher. The gap between CHF53.14 and those ranges is now wide enough that the valuation work really starts to matter.
Most Popular Narrative: 30% Undervalued
On the most followed view of Alcon, a fair value of CHF75.71 sits well above the last close at CHF53.14. That gap puts the focus squarely on whether new launches like Systane PRO Preservative-Free can support the long-term growth and profitability assumptions baked into that estimate.
Accelerated new product launches including Unity VCS (next-gen surgical platform), PanOptix Pro (premium IOL), Tryptyr (first-in-class dry eye Rx), Precision7 (novel contact lens), and recent pipeline-accretive M&A (STAAR, LumiThera, Voyager) provide significant near
and medium-term opportunities for share gain, mix improvement, and new market entry, underpinning upside to both revenue and net margins as these innovations scale.
See why 27 investors see Alcon as 30% undervalued.
Result: Fair Value of CHF75.71 (UNDERVALUED)
Still, the bullish Alcon narrative could unravel if competitive pressure in intraocular lenses persists, or if recent acquisitions prove slower to integrate than expected.
Find out about the key risks to this Alcon narrative.
Another Take On Alcon’s Valuation
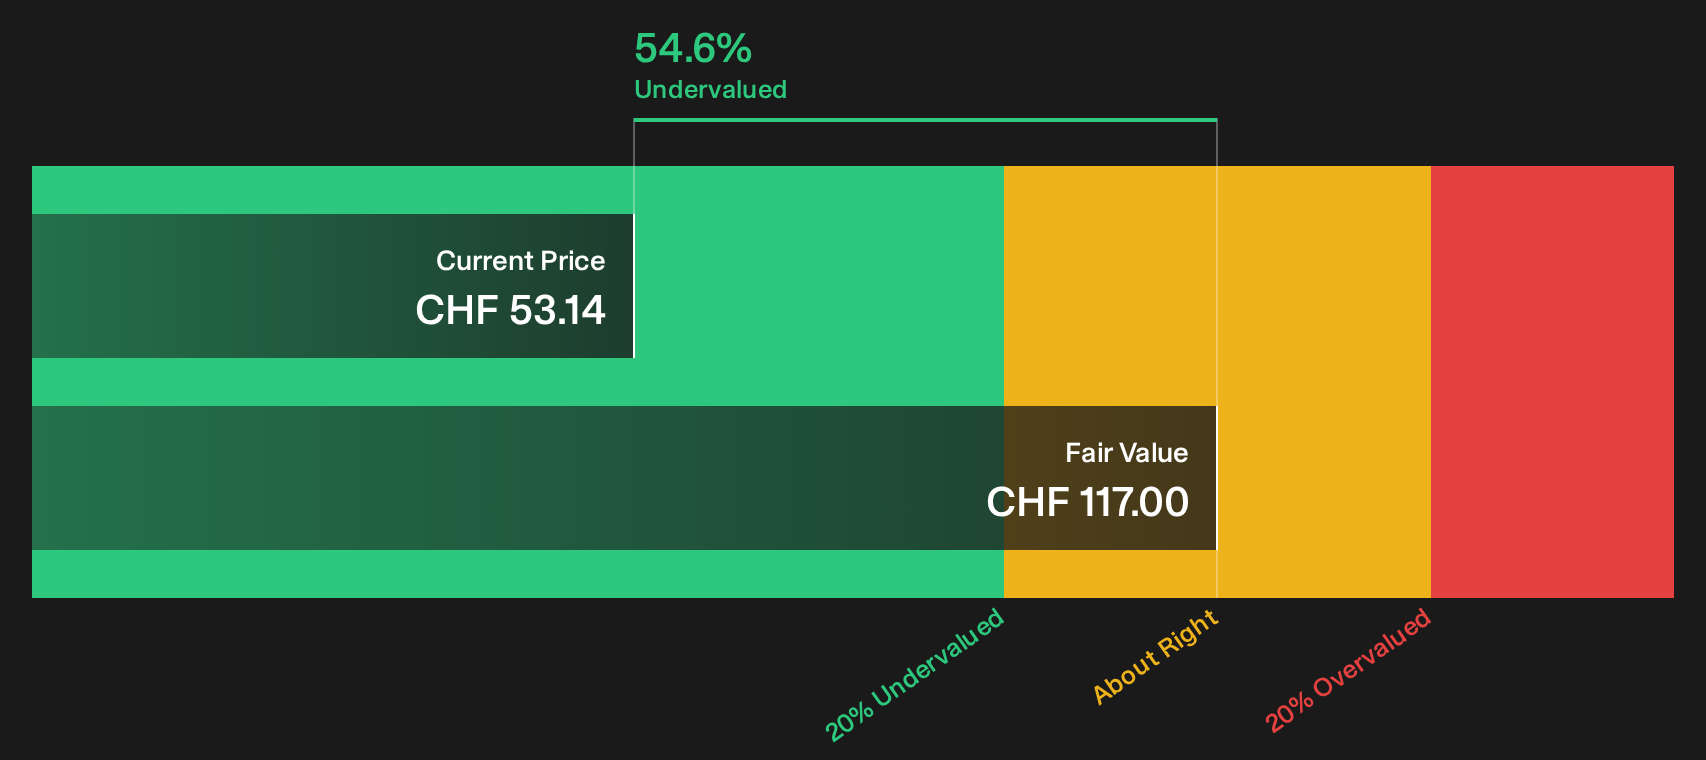
The DCF view presents Alcon as deeply undervalued, with CHF53.14 per share trading 54.6% below an estimated fair value of CHF117 based on future cash flows. That is a wide gap. The key question is whether you place more weight on those long range cash flow assumptions or on the current multiples.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Alcon’s valuation and outlook can be confusing. Move quickly, review the underlying data for yourself, and weigh both sides through the 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Alcon?
If Alcon has sharpened your focus on pricing and quality, do not stop here. Broader idea generation often separates patient investors from missed opportunities.
- Target resilient balance sheets by reviewing companies on the list of solid balance sheet and fundamentals (204 results) that pair financial strength with cleaner fundamentals.
- Hunt for mispriced quality and scan the 178 high quality undervalued stocks that some investors may not be watching closely yet.
- Spot potential future favourites early by filtering through the 618 high quality undiscovered gems before crowd attention catches up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com