


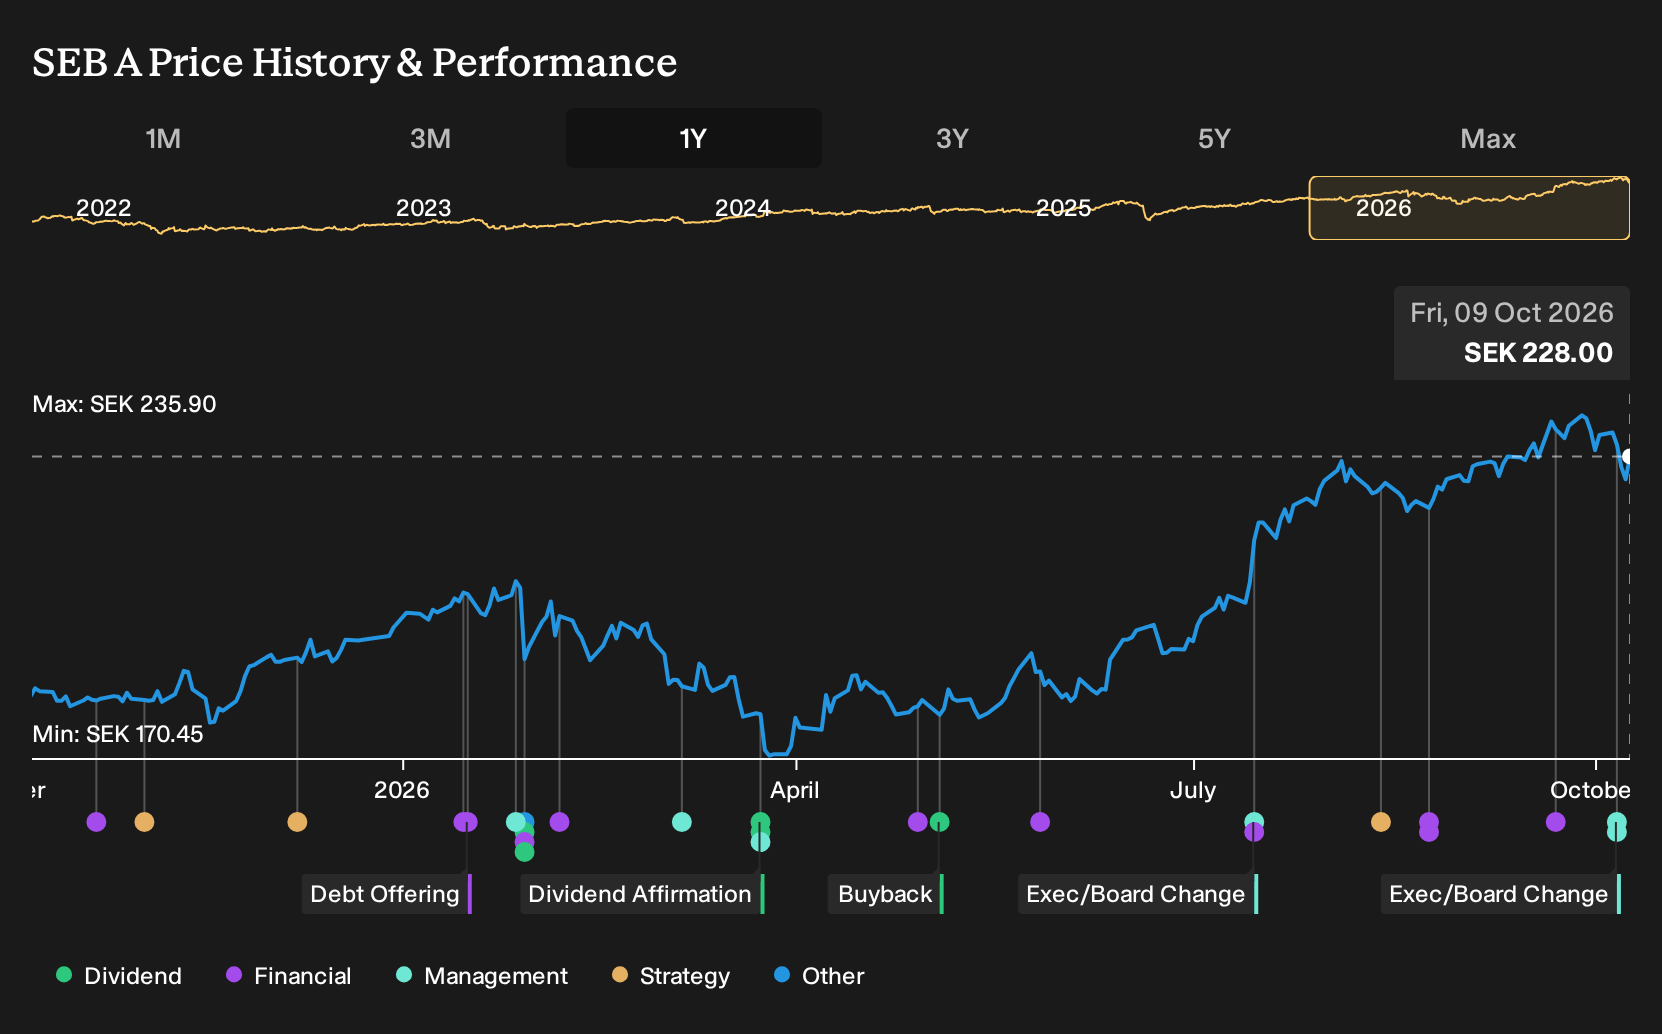
- Skandinaviska Enskilda Banken announced that long serving President and CEO Johan Torgeby resigned on 6 October 2026, with Deputy President and CEO Jonas Ahlström stepping in as acting President and CEO, subject to regulatory approvals.
- The shift from a decade long leadership tenure to an interim chief places SEB’s ongoing execution on fees, efficiency and capital return under fresh scrutiny.
- This article examines how SEB's investment narrative intersects with the sudden CEO transition and what that may mean for investors.
Skandinaviska Enskilda Banken Investment Narrative Recap
To own Skandinaviska Enskilda Banken, you need to trust its multi segment banking model, with Corporate & Investment Banking, Business & Retail Banking, Wealth & Asset Management and Baltic all pulling their weight. The story hinges on fee and commission income, wider product usage per client and efficiency gains from AI, while the new acting CEO keeps that playbook intact.
The main short term swing factor is client activity in CIB and wealth, especially if market volatility hits deal making or trading volumes. The biggest operational risk stays the same, pressure on net interest income and fees from competition, regulation and possible levies, rather than the CEO change itself.
The leadership announcement on 6 October 2026 is the key development to watch right now. Johan Torgeby stepping down after almost a decade as President and CEO, and leaving the Board, hands execution to acting chief Jonas Ahlström, who has been with Skandinaviska Enskilda Banken since 2005 and on the Group Executive Committee since 2020.
For you as a shareholder, this puts attention on whether Ahlström keeps momentum in areas that matter most, such as AI rollout, cross selling and capital allocation, including ongoing share buybacks. The handover may also draw focus to risk controls and regulatory relationships, which matter given SEB’s exposure to corporate lending, investment banking activity and Baltic operations.
Skandinaviska Enskilda Banken's current analyst story points to SEK 87.1b revenue and SEK 36.8b earnings by 2029, based on assumed 5.3% yearly revenue growth and an earnings increase of about SEK 5.7b from SEK 31.1b today.
Uncover why Skandinaviska Enskilda Banken's fair value is essentially in line with its current price.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly SEK 227 to SEK 390, so private investors are anchoring Skandinaviska Enskilda Banken across a wide price band. Set that against risks around fee reliant CIB activity, regulation and CEO transition timing, and you may benefit from weighing several contrasting viewpoints.
Explore 2 other Skandinaviska Enskilda Banken fair value estimates, including one that suggests it could be worth just SEK227.18.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Skandinaviska Enskilda Banken research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Skandinaviska Enskilda Banken. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Skandinaviska Enskilda Banken's overall financial health at a glance.
Looking for more Skandinaviska Enskilda Banken style investment ideas?
If this leadership reset at Skandinaviska Enskilda Banken has prompted you to rethink where you allocate capital, it can help to line it up against other businesses with different risk profiles, income potential and balance sheet strength. The Simply Wall St Screener lets you scan for companies that match the kind of traits you want in your next position, rather than relying only on headlines.
- For investors who want growth potential at a lower entry price, look across 125 elite penny stocks with strong financials that already have solid underlying financials.
- If resilience and capital preservation matter most to you, filter for 223 resilient stocks with low risk scores that score well on both earnings quality and balance sheet strength.
- For those hunting beyond the usual tickers, widen your opportunity set with a 618 high quality undiscovered gems that combine quality fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com