


Emerson Electric (EMR) is back in focus after analysts raised earnings estimates and management issued upbeat guidance that points to higher year over year profit and revenue expectations.
Recent trading suggests momentum is building. Emerson Electric’s share price has gained 19.2% year to date and delivered a 30.4% total shareholder return over the past 12 months, as upbeat guidance and earnings revisions reshape how investors view the company’s risk and growth profile.
Surf 92 AI infrastructure stocks to see which peers could be setting up for the next move as investors reassess automation and AI exposure after Emerson Electric's upbeat earnings outlook.After a 30.4% total return in 12 months and a rich AI and automation story building around Emerson Electric, the key issue now is whether the current valuation still leaves enough potential upside for new money coming in.
Most Popular Narrative: 6.8% Undervalued
On the narrative view, Emerson Electric’s fair value of $173.68 sits above the last close at $161.83. This keeps the debate squarely on how much of the AI, software and project funnel story is already reflected in the price.
Large-scale investments in power generation, LNG and life sciences driven by rising energy security concerns, electrification and sustainability initiatives are driving significant greenfield and modernization projects in regions such as North America, Asia and the Middle East. This is visible in the growth in power orders, the expansion of the power project funnel to about US$3b and the US$2.2b LNG funnel, and could support revenue and operating margin resilience.
See why 56 investors see Emerson Electric as 7% undervalued.
Result: Fair Value of $173.68 (UNDERVALUED)
Still, the Emerson Electric story can change quickly if Middle East project disruptions deepen, or if China weakness stretches beyond chemicals into broader industrial demand.
Find out about the key risks to this Emerson Electric narrative.
Another View: Cash Flow Says Emerson Electric Is Expensive
There is a catch. While the analyst narrative pegs Emerson Electric at about 6.8% undervalued on earnings and multiples, the Simply Wall St DCF model points the other way, with a future cash flow value of $81.53 versus the $161.83 share price. That flags a big valuation gap investors need to explain.
Before leaning on either lens too heavily, it helps to understand exactly how our DCF model treats growth, margins and discount rates in Emerson Electric's case. Look into how the SWS DCF model arrives at its fair value.
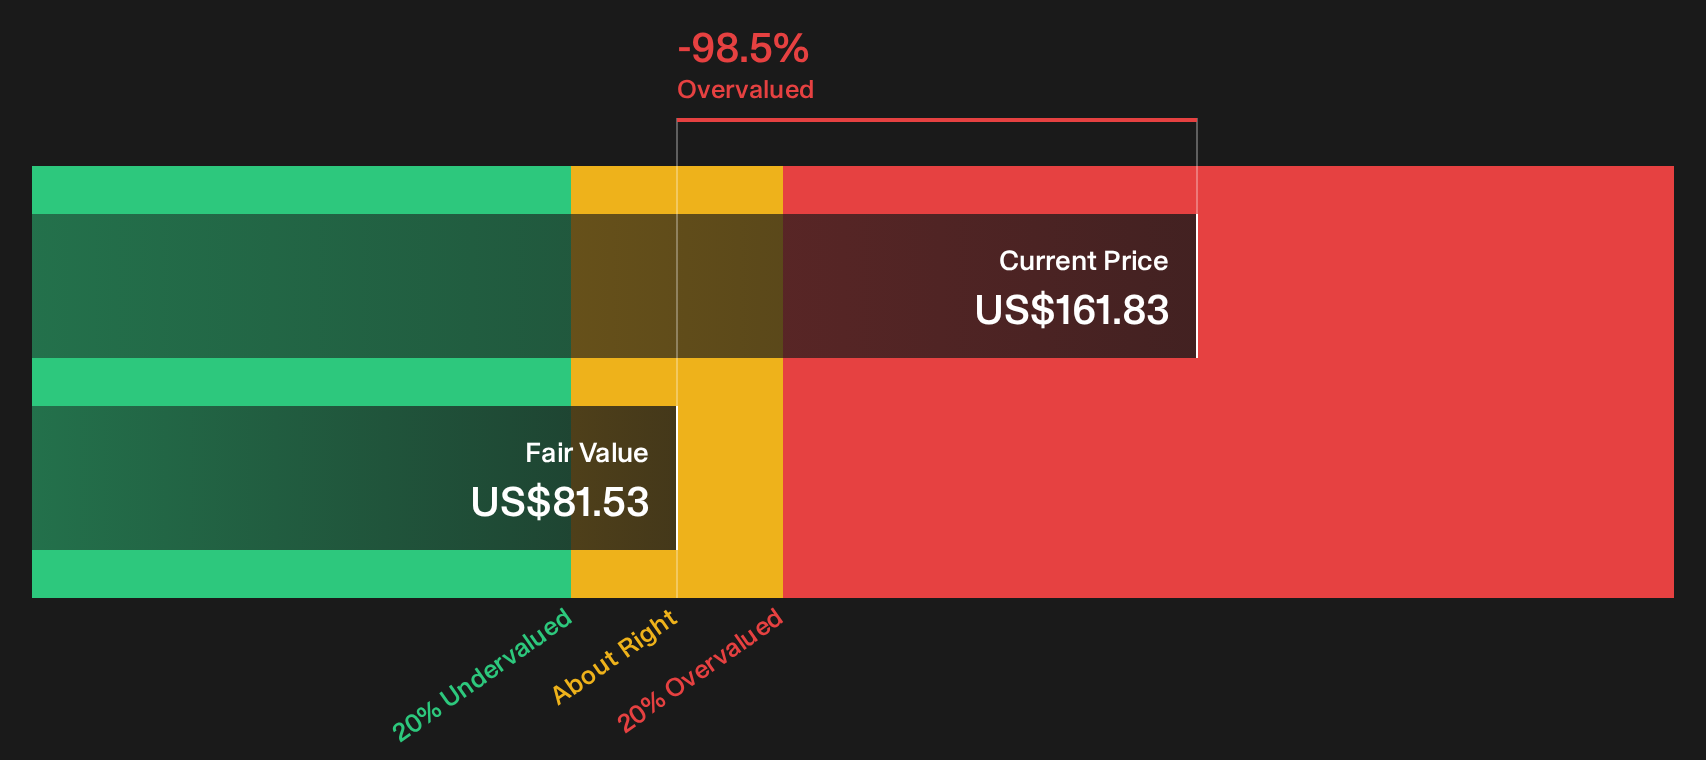
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Emerson Electric for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Emerson Electric’s value and cash flows make this a moment to move quickly. Review the underlying data yourself and decide where you stand using the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Emerson Electric?
If Emerson Electric has sharpened your thinking, do not stop here. Broaden your watchlist with focused screeners that surface clear, data driven opportunities tailored to different investing styles.
- Target potential bargains by zeroing in on quality companies trading below intrinsic estimates using the 29 high quality undervalued stocks.
- Strengthen your income playbook by hunting for robust payers through the 8 dividend fortresses.
- Dial down portfolio risk by scanning for sturdier balance sheets and cleaner fundamentals in the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com