


Verizon Communications has seen a sharp pullback in recent weeks after a strong multi year run. This puts a fresh spotlight on whether the current share price still matches up with what its earnings can support.
- Over the past 3 years the stock has returned about 65.1%. As a result, a lot of the long term case investors have built now feeds directly into the question of what earnings justify today’s valuation.
- SpaceX’s move into low band spectrum and Verizon’s own satellite focused joint venture with AT&T and T Mobile can influence how investors think about the company’s future profitability, capital spending needs and the timing of its cash flows.
- There is a second opinion on Verizon Communications worth weighing. See what analysts think Verizon Communications's shares could be worth.
The issue now is whether Verizon Communications' earnings profile is strong enough to support the price you see on the screen today.
If you want to test this same earnings question beyond Verizon Communications, compare it with a wider group of 29 high quality undervalued stocks.
Does Verizon Communications Look Undervalued on Earnings?
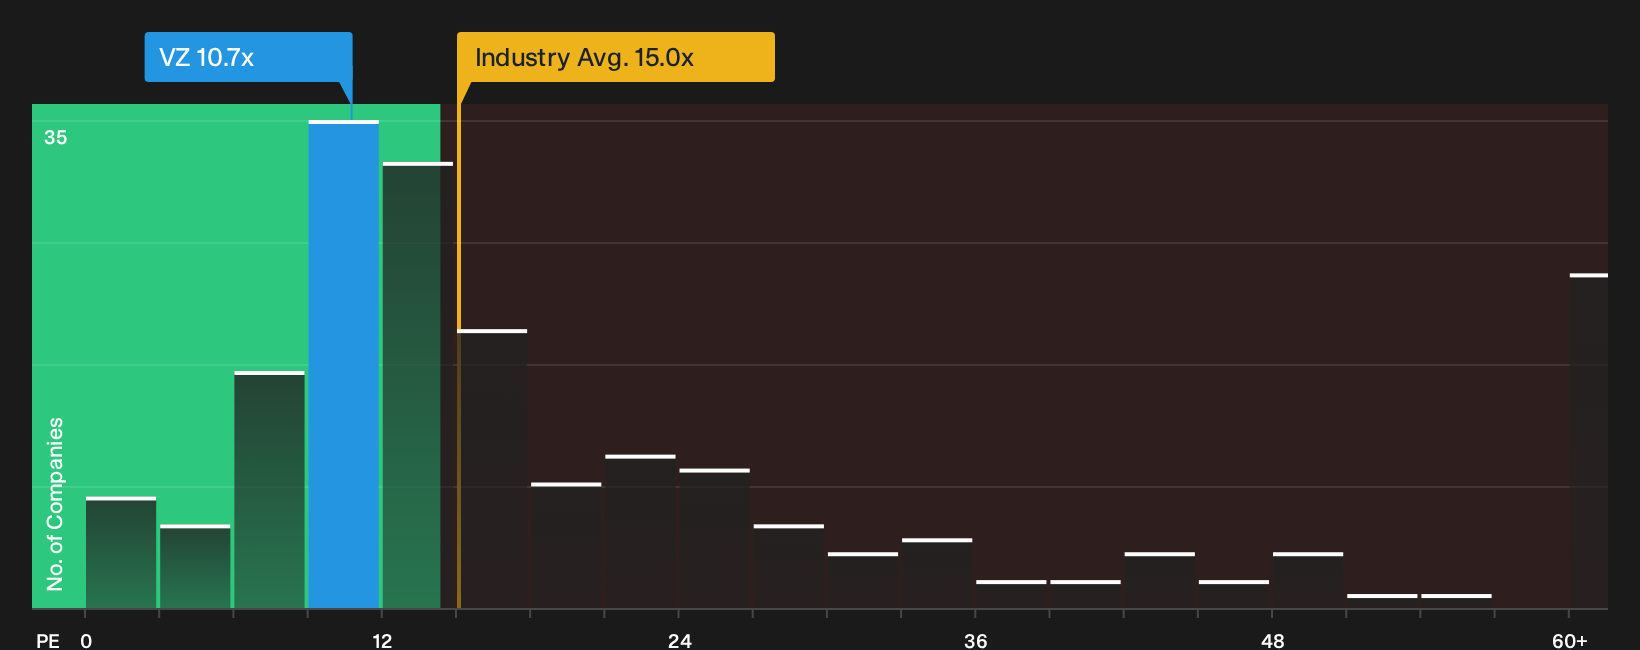
P/E works well for Verizon Communications because earnings remain a central anchor for how investors judge large, mature telecom stocks. On this measure, Verizon trades on a P/E of about 10.7x, which is close to the peer average of roughly 10.5x and sits well below the wider Telecom industry on about 15.0x. That puts the stock at a lower earnings multiple than many sector peers, without suggesting investors are ignoring company specific risks.
The Fair Ratio model, which blends factors like Verizon Communications' profitability, risk profile and industry backdrop into a tailored benchmark multiple, indicates that the current P/E is below where it might trade on those fundamentals. Despite the competitive threat highlighted by SpaceX’s push into low band spectrum, the earnings multiple still prices Verizon at a discount to both the sector and this more customised yardstick. This is where the potential opportunity and risk debate really starts. Explore the numbers behind Verizon Communications's P/E valuation.
The Verizon Communications Narrative: What Would Justify Today's Price?
Narratives pick up where the Verizon Communications valuation puzzle leaves off. They spell out which paths for revenue, margins and earnings would need to play out for the current share price to look too high or too low, and they sit on Simply Wall St's Community page. Rather than relying on a single multiple or one model outcome, each scenario lays out its own fair value assumptions so you can compare them with future results as they arrive.
One of the top community narratives on Verizon Communications: 19% undervalued
"Digital transformation among enterprises and increased remote work are sustaining demand for Verizon Communications private network and AI enabled connectivity offers…"
Discover why this Narrative puts Verizon Communications at 19% undervalued.
For Verizon Communications, the sticker price is only one piece of the puzzle
Who steers Verizon Communications, how their incentives are structured, and whether those rewards line up with your interests can matter as much as any P/E ratio you see on screen. See who runs Verizon Communications and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com