


As global markets experience volatility due to geopolitical tensions and fluctuating energy prices, the Asian market presents unique opportunities amidst these challenges. Small-cap stocks in particular can offer potential growth, especially when they demonstrate resilience and adaptability in a dynamic economic environment.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Eurocharm Holdings | 2.66% | 3.48% | 7.39% | ★★★★★★ |
| SPRIX | 13.12% | 6.95% | -5.71% | ★★★★★★ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Shanghai Fudan Microelectronics Group | 16.49% | 9.29% | -6.62% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Let's uncover some gems from our specialized screener.
Beijing Caishikou Department StoreLtd (SHSE:605599)
Simply Wall St Value Rating: ★★★★★★
Overview: Beijing Caishikou Department Store Co., Ltd., along with its subsidiaries, operates in the gold and jewelry retail sector in China, with a market capitalization of approximately CN¥11.16 billion.
Operations: The company's primary revenue stream is from its gold and jewelry retail segment, generating CN¥34.61 billion. Its financial performance is significantly influenced by this sector, with a net profit margin that reflects the efficiency of its operations in the competitive retail market.
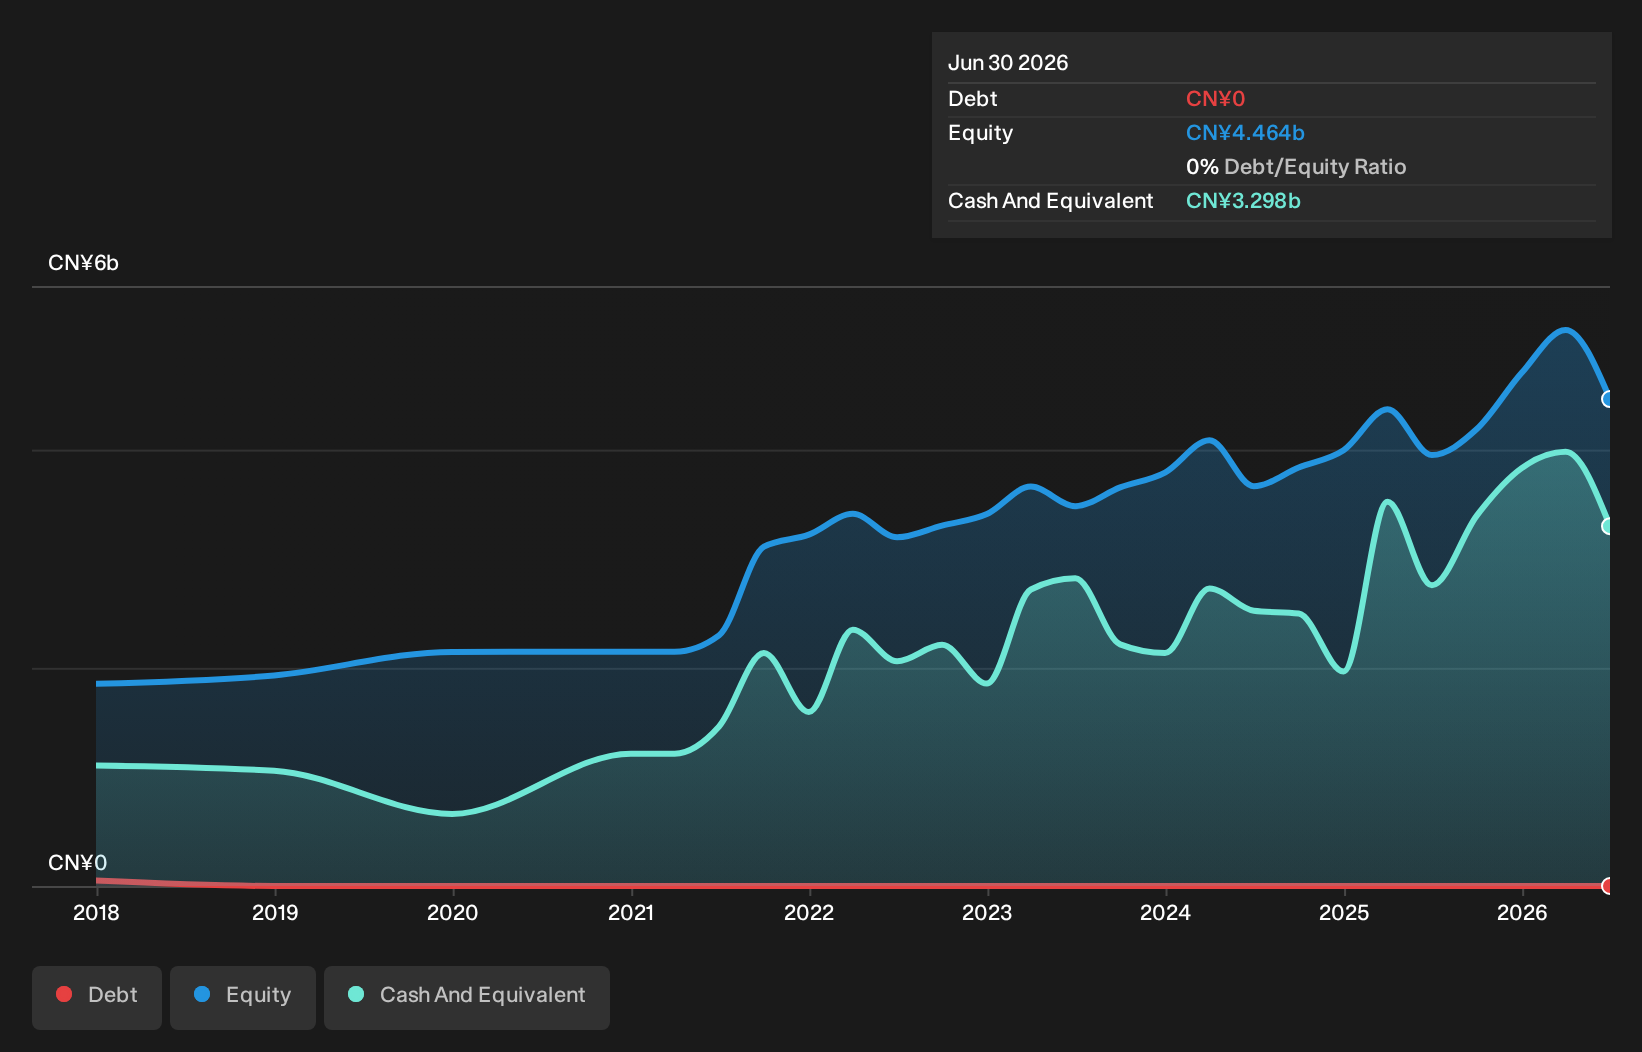
Beijing Caishikou Department Store, a promising player in the specialty retail sector, has demonstrated impressive earnings growth of 42.8% over the past year, outpacing the industry average of 22.6%. The company reported half-year sales of CNY 21.03 billion, up from CNY 15.23 billion a year ago, although net income slightly decreased to CNY 436.78 million from CNY 458.69 million previously. With no debt on its books and trading at an attractive value—64% below estimated fair value—the department store seems well-positioned for future expansion despite recent profit pressures reflected in earnings per share dropping to CNY 0.56 from CNY 0.59 last year.
Koshidaka Holdings (TSE:2157)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Koshidaka Holdings Co., Ltd. operates in the karaoke business both in Japan and internationally, with a market capitalization of ¥80.71 billion.
Operations: Koshidaka Holdings generates revenue primarily from its karaoke business operations in Japan and abroad. The company's financial performance is reflected in its market capitalization of ¥80.71 billion.
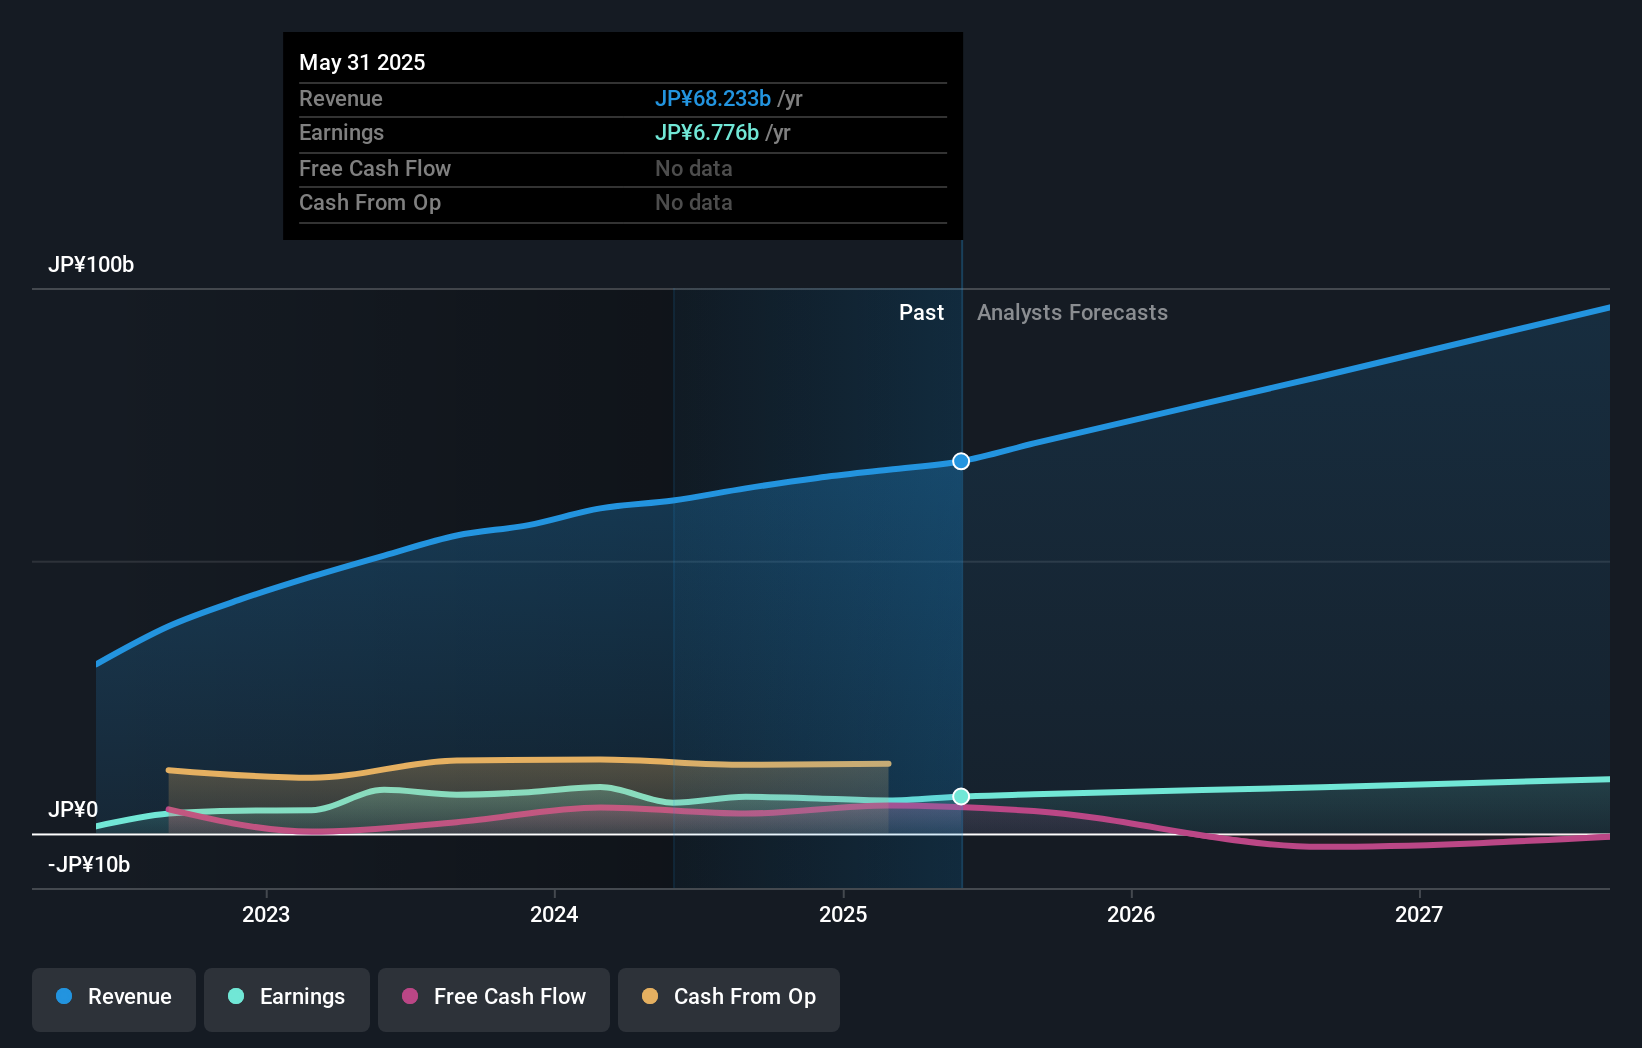
Koshidaka Holdings, a notable player in the entertainment sector, showcases promising financial health with a net debt to equity ratio of 4.8%, reflecting prudent management. Its earnings surged by 20.7% last year, outpacing the hospitality industry's 19.9% growth, indicating robust operational performance. Despite a ¥2.2B one-off loss impacting recent results, Koshidaka trades at an attractive valuation—21% below its estimated fair value—suggesting potential upside for investors seeking value opportunities in Asia's small-cap landscape. With interest payments well covered by EBIT (107x), the company seems well-positioned for future growth and stability amidst industry dynamics.
Toyobo (TSE:3101)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Toyobo Co., Ltd. is a diversified company that manufactures, processes, and sells films, life sciences products, environmental and functional materials, as well as fibers and textiles across Japan, China, Southeast Asia, and globally; it has a market capitalization of ¥145.33 billion.
Operations: The primary revenue streams for Toyobo Co., Ltd. include films generating ¥180.09 billion and environmental and functional materials contributing ¥121.01 billion, while life sciences add ¥35.75 billion to the total revenue mix.
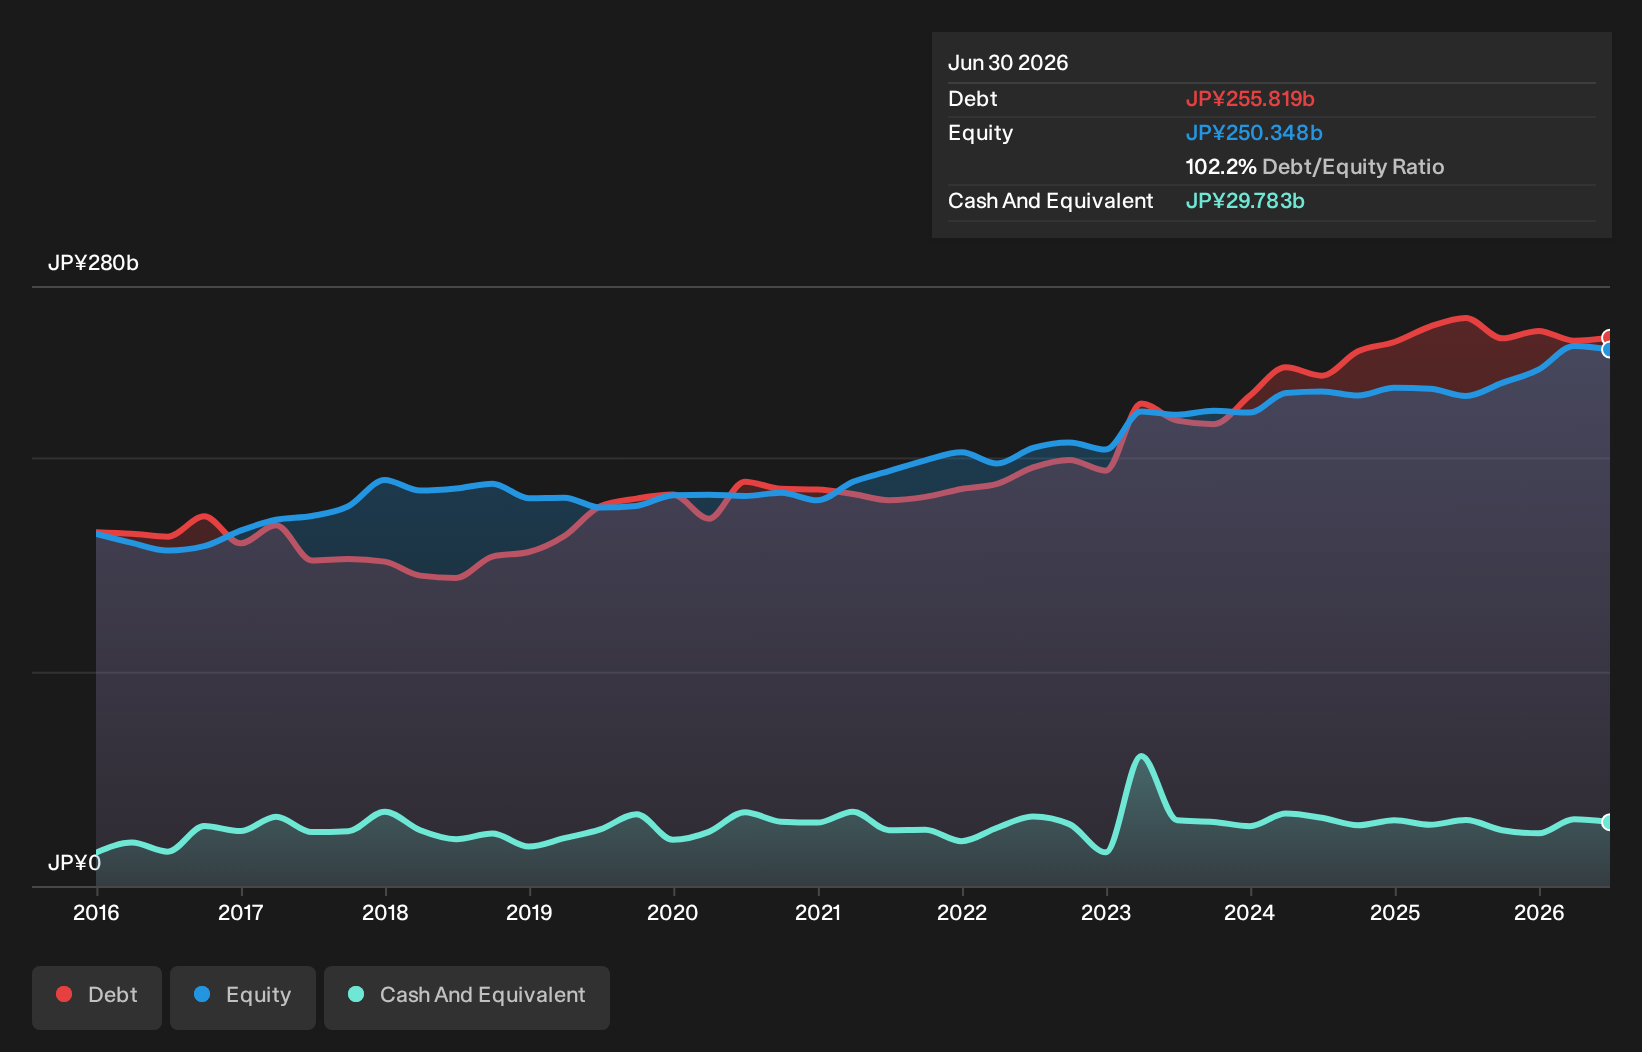
Toyobo, a notable player in the chemicals industry, has showcased impressive earnings growth of 353.9% over the past year, significantly outpacing its industry peers. Despite trading at 41.8% below estimated fair value and offering high-quality earnings, its net debt to equity ratio stands at a concerning 90.3%. The company reported sales of ¥110 billion for Q1 2026, up from ¥103 billion last year, with net income rising to ¥3 billion from ¥1.57 billion previously. Recent strategic moves include a planned absorption-type split within its subsidiary and asset transfers to streamline operations further.
- Click to explore a detailed breakdown of our findings in Toyobo's health report.
Review our historical performance report to gain insights into Toyobo's's past performance.
Seize The Opportunity
- Embark on your investment journey to our 116 Asian Undiscovered Gems With Strong Fundamentals selection here.
- Have a stake in these businesses? Integrate your holdings into Simply Wall St's portfolio for notifications and detailed stock reports.
- Discover a world of investment opportunities with Simply Wall St's free app and access unparalleled stock analysis across all markets.
Interested In Other Possibilities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com