


nVent Electric has been on a powerful multi year run, and with the stock still trading around its recent level of US$167.43, the live question is whether that price is properly supported by the company’s earnings profile today.
- Over the past 5 years the share price has climbed about 460%, which puts real pressure on the earnings story to carry the valuation load.
- Recent coverage has highlighted growing exposure to AI focused data centers and the Maverick Power acquisition, developments that can shape how quickly profits, reinvestment needs, and cash generation evolve from here.
- The analysts covering nVent Electric have run their own numbers. See what analysts think nVent Electric's shares could be worth.
The stock's next move may depend on whether nVent Electric's current earnings are strong and resilient enough to justify this kind of share price run.
If you are weighing nVent Electric against other ways to play this build out in power and data infrastructure, a focused screen of 43 power grid technology and infrastructure stocks.
Is nVent Electric Getting Expensive on Earnings?
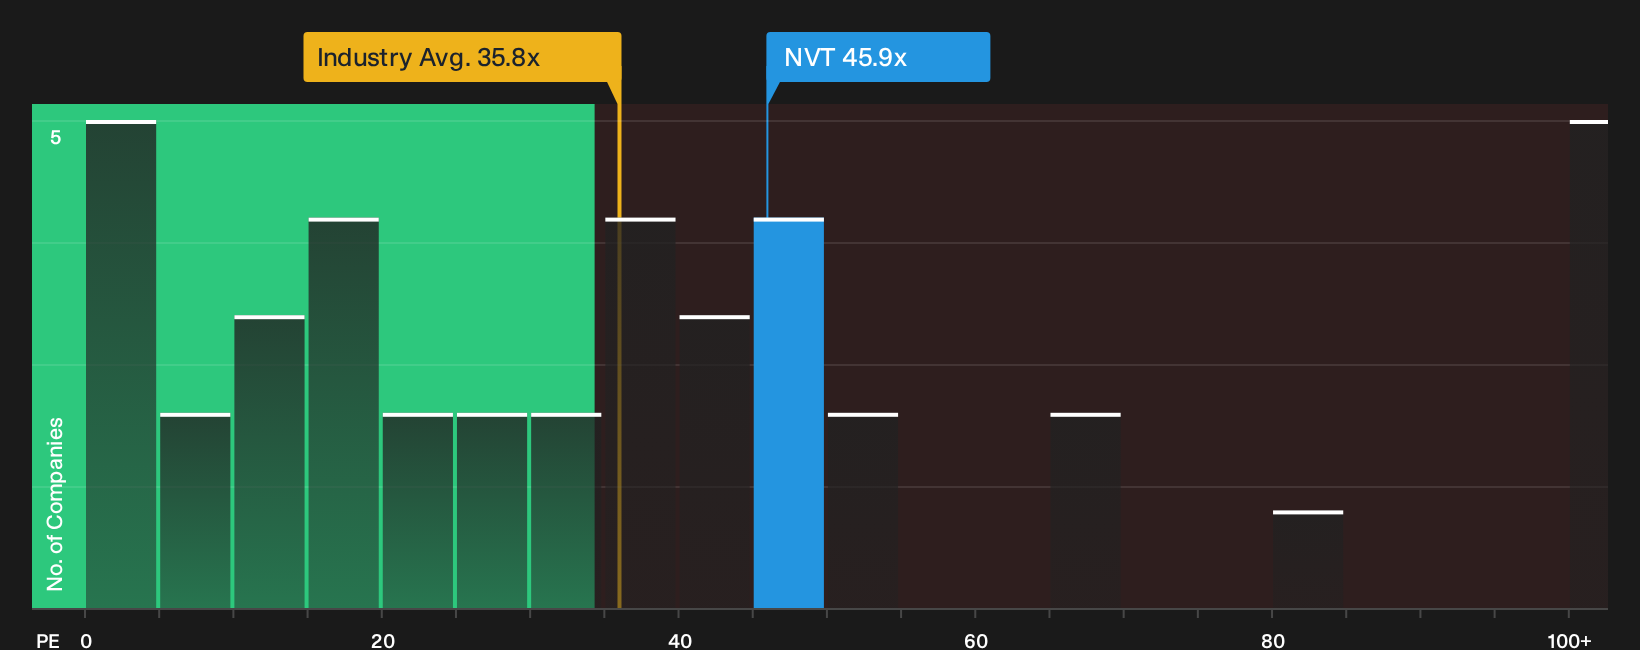
The P/E ratio is a natural lens for nVent Electric because earnings are the main hook for the story investors are paying up for here. On this measure the stock trades on roughly 45.9x, which is richer than both the Electrical industry average of about 35.8x and the peer group around 31.5x. Against the tailored fair P/E level implied by its own profile, that current tag also screens on the expensive side.
Because the share price has already reacted to enthusiasm around AI focused data centers and the Maverick Power deal, this premium P/E multiple asks you to assume that today’s earnings power and reinvestment needs justify a higher entry price than many sector alternatives. The gap to both peers and the modelled fair range signals that a lot of optimism is already embedded in the valuation, so any comparison with other power and data plays probably starts with how comfortable you are paying this kind of earnings multiple for nVent Electric. Explore the numbers behind nVent Electric's P/E valuation.
The nVent Electric Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where nVent Electric's valuation puzzle leaves off. They spell out which assumptions about future growth, profitability and earnings would need to hold for the shares to be worth materially more or less than today’s price, and sit on the stock’s Community page. Each Narrative frames nVent Electric's implied worth as a specific thesis about the business that can be revisited over time rather than a one off snapshot.
Community views on nVent Electric are split between potential upside from AI-heavy infrastructure demand and concern that a rich P/E leaves little room for mistakes.
Bull case: 19% undervalued
"Accelerating AI related data center spending, supported by nVent Electric’s roughly $2.5b backlog and guidance that total data center sales are expected to move above $2b in 2026…"
Discover why this Narrative puts nVent Electric at 19% undervalued.
Bear case: 7% overvalued
"While nVent Electric is leaning into rising electricity demand for utilities and data centers, the added $800 million of senior notes due 2036 and $600 million term loan to fund Maverick Power raise fixed financing costs…"
Explore why this Narrative puts nVent Electric at 7% overvalued.
The share price is only one piece of the nVent Electric puzzle
Price and today’s P/E tell only part of the story, because analyst expectations a few years out give you a separate yardstick to compare against what the market is charging right now. Explore where analysts expect nVent Electric to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com