


Energy route disruptions and refinery capacity constraints in the Gulf of Mexico have pushed Murphy USA (MUSA) into focus as investors reassess how tighter fuel supply could affect margins and long term profitability guidance.
Murphy USA’s recent move to a US$529.14 share price, with a 1-day share price return of 2.11% and a year-to-date share price return of 30.55%, comes after a 90-day share price decline of 13.37% that tempers strong multi year total shareholder returns of 40.75% over 1 year and 227.05% over 5 years, suggesting that the latest fuel supply shock is being interpreted as a new catalyst rather than a reversal in the longer narrative around the business.
Scan fuel retail peers that could also see margin pressure or support from supply disruptions through our curated list of solid balance sheet and fundamentals (25 results), which is aligned with this Murphy USA story.
Murphy USA appears to be a robust fuel retailer based on recent figures. However, a US$529.14 share price following a sharp multi year run raises a key question: are investors paying a fair price for that strength today?
Most Popular Narrative: 14% Undervalued
Murphy USA’s most followed valuation story puts fair value at $617.80, which sits well above the recent $529.14 close and frames the tight fuel market as a key support for that gap.
Structurally higher all in fuel margins, supported by guidance of about $0.35 per gallon for the back half of 2026 and evidence of rational pricing and higher breakeven levels for marginal retailers, could keep Murphy USA’s gross profit and net margins above prior cycles.
Consistent contribution from the integrated fuel supply chain, with controllable economics in the range of $0.02 to $0.03 per gallon and leverage to periods of tight physical supply and price volatility, creates an additional earnings stream that can support overall margin resilience.
See why 12 investors see Murphy USA as 14% undervalued.
Result: Fair Value of $617.80 (UNDERVALUED)
Still, the bullish Murphy USA story can unravel quickly if fuel margins soften faster than analysts expect or if insider selling triggers a sharp P/E reset.
Find out about the key risks to this Murphy USA narrative.
Another View: Murphy USA Through The Earnings Multiple
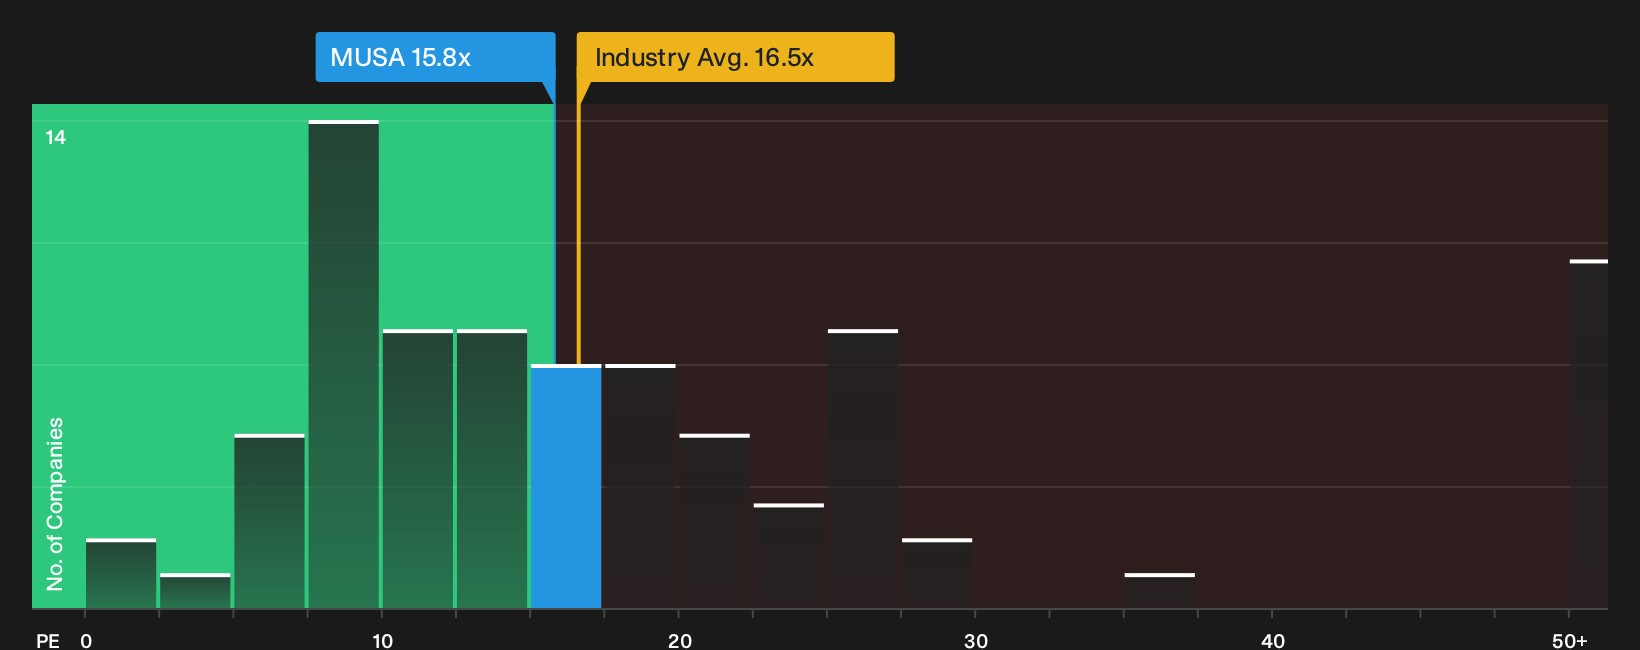
There is a different message when Murphy USA is viewed through its earnings ratio instead of the bullish fair value of $617.80. The stock trades on a P/E of 15.8x, above a peer average of 13.8x and above a fair ratio estimate of 12x, which suggests less room for error if the story shifts.
To pressure test that view against detailed earnings data and peer comparisons, focus on what the numbers imply for valuation risk rather than any single target price See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this Murphy USA story appears finely balanced between potential upside and risk, consider acting promptly, reviewing the key metrics yourself, and weighing both sides using the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Murphy USA?
If you want a broader view of opportunities, use the Simply Wall Street Screener to see how other businesses stack up on quality, value, and risk.
- Target reliable cash generators by reviewing companies on our 29 high quality undervalued stocks that blend strong fundamentals with appealing valuations.
- Prioritise stability and sleep-at-night resilience by scanning the 31 resilient stocks with low risk scores focused on businesses with lower overall risk scores.
- Get ahead of the crowd by tracking future standouts through our 20 high quality undiscovered gems before they appear on everyone else's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com