


ATCO’s merger deal and dividend decision set the stage
Emera Incorporated has agreed to acquire ATCO (TSX:ACO.X) in a CAD 6.6b all share transaction, while ATCO plans to spin off its industrial services arm and retain a 20% stake in the combined utility entity.
Alongside that pending merger, ATCO has affirmed a quarterly dividend of CA$0.5196 per share, payable on December 31, 2026, with both the ex date and record date set for December 3, 2026.
ATCO’s recent merger announcement and dividend affirmation have arrived alongside strong share price momentum, with the stock up 7.0% over the past week and showing a 40.99% year to date share price return from a CA$79.76 level today.
That short term move comes on top of a longer run of gains, with a 61.02% total shareholder return over one year and triple digit total shareholder returns over three and five years. This suggests that investors have been steadily repricing both future growth potential and risk around the business as these latest corporate moves unfold.
Spot emerging utilities and infrastructure plays reacting to deals like ATCO’s merger by scanning our hand picked 43 power grid technology and infrastructure stocks.ATCO’s surge could indicate that investors are reassessing the industrial spin off and utility merger as a shift in business quality rather than simply a change in sentiment. The valuation now needs to be examined with that perspective in mind.
Most Popular Narrative: 12% Undervalued
ATCO’s most followed narrative pegs fair value at CA$91.00, modestly above the CA$79.76 last close, which frames today’s merger driven rally as only a partial reflection of the underlying thesis.
Robust long term demand for modular and affordable housing, driven by government policy and urbanization, positions ATCO to capitalize on significant infrastructure investment initiatives in Canada and internationally. Recent government commitments and ATCO's scalable modular manufacturing capacity are likely to translate to higher revenue growth over the next several years.
See why 33 investors see ATCO as 12% undervalued.
The narrative leans on a 6.44% discount rate and a CA$91.00 fair value, which together imply that ATCO’s CA$5,319.0m of annual revenue and CA$182.0m of net income are being weighed against a long runway of projected earnings expansion and margin recovery. That view also intersects with the SWS cash flow work, which currently has ATCO trading 4.3% below an estimate of future cash flow value at CA$83.38, suggesting that both earnings based and cash flow based frameworks are pointing in the same general direction.
The result is a story where upside in the narrative relies on execution against that housing and utilities pipeline, while the current share price already embeds some of the recent momentum and merger optimism.
Result: Fair Value of CA$91 (UNDERVALUED)
Still, heavy capital needs and rising debt, along with reliance on government backed projects, could challenge ATCO’s thesis if funding or costs shift in an unfavorable way.
Find out about the key risks to this ATCO narrative.
Another View: ATCO’s valuation looks rich on earnings
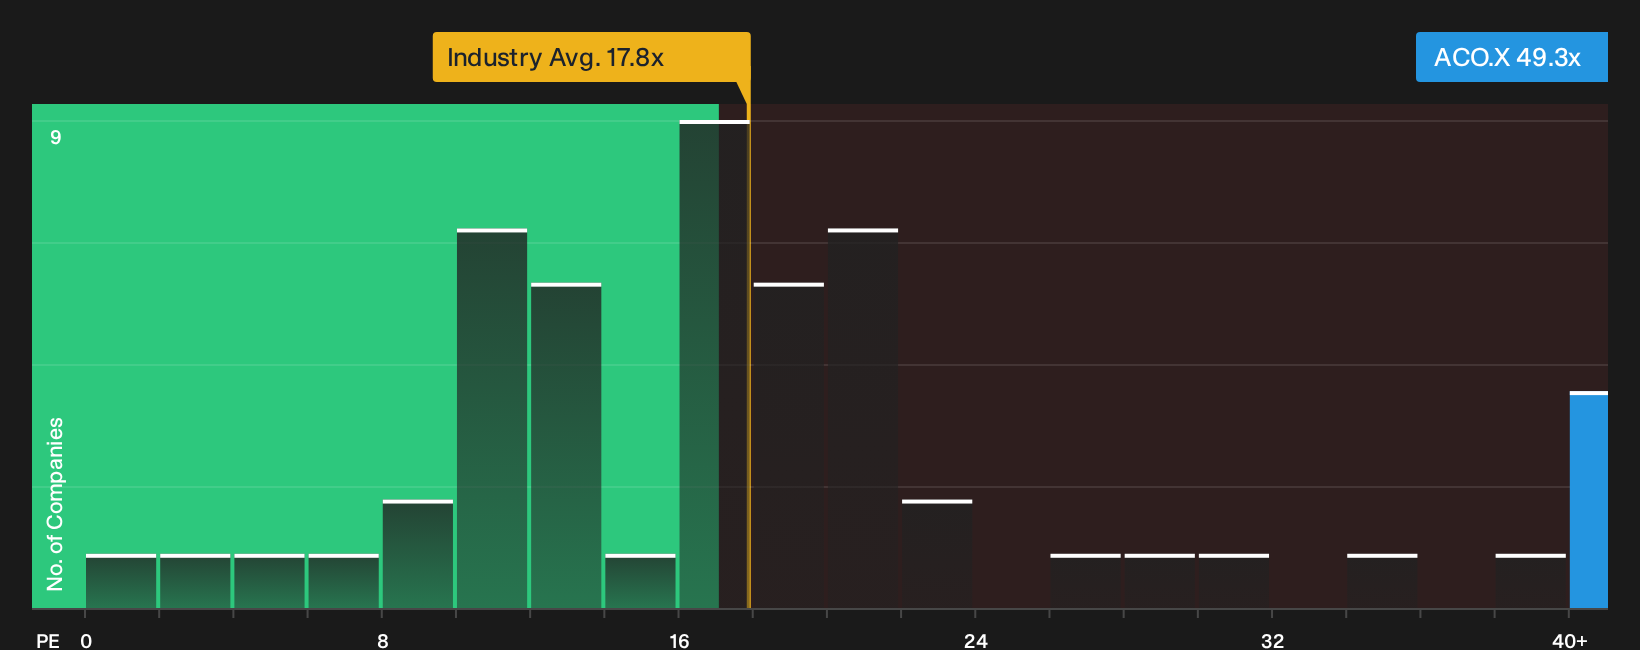
On the story and DCF work, ATCO screens as modestly undervalued. On plain earnings, the picture flips. The stock trades on a P/E of 49.3x versus 17.8x for the global integrated utilities group and a fair ratio of 39.5x, which points to meaningfully higher valuation risk if expectations cool.
For investors weighing that gap between price and earnings power, the key question is whether ATCO’s merger and housing narrative really justify such a premium multiple.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If sentiment around ATCO feels mixed, that is the point. The data holds both caution and optimism, so consider it promptly and ground your own stance in the 2 key rewards and 3 important warning signs.
Looking for more ATCO style investment ideas?
If ATCO’s story has you thinking bigger about your portfolio, do not stop here. The next opportunity you rate highly could be one smart screen away.
- Target resilient cash generators by scanning companies on the 8 high quality undervalued stocks that combine quality fundamentals with pricing that has not fully caught up.
- Strengthen your income stream by finding potential high yield payers through the 3 dividend fortresses before the wider market focuses on them.
- Rebuild your shortlist around financial resilience by using the list of solid balance sheet and fundamentals (7 results) so you are not caught holding fragile stories when conditions change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com