


Dominion Energy has delivered a 68.1% share price return over the past three years, while also landing in the middle of a proposed US$66.8b takeover by NextEra Energy. With that mix of stock gains and corporate change, the open question is whether the current valuation makes sense when you focus squarely on Dominion Energy's earnings power.
- A 68.1% return over three years puts real weight on the question of whether Dominion Energy's earnings can carry the price that investors are now paying.
- The proposed NextEra merger, along with Virginia regulators approving securitization of underrecovered fuel costs, can reshape how quickly Dominion Energy converts future earnings into cash and what level of capital spending it may need to support the utility business.
- The analysts covering Dominion Energy have run their own numbers. See what analysts think Dominion Energy's shares could be worth.
The issue now is whether Dominion Energy's current share price is justified by what the company is earning today and what its earnings profile suggests over time.
If you are weighing whether Dominion Energy's 68.1% three year return is justified by its earnings, it can help to compare it with other regulated utilities inside our 43 power grid technology and infrastructure stocks.
Does Dominion Energy Look Fairly Valued on Earnings?
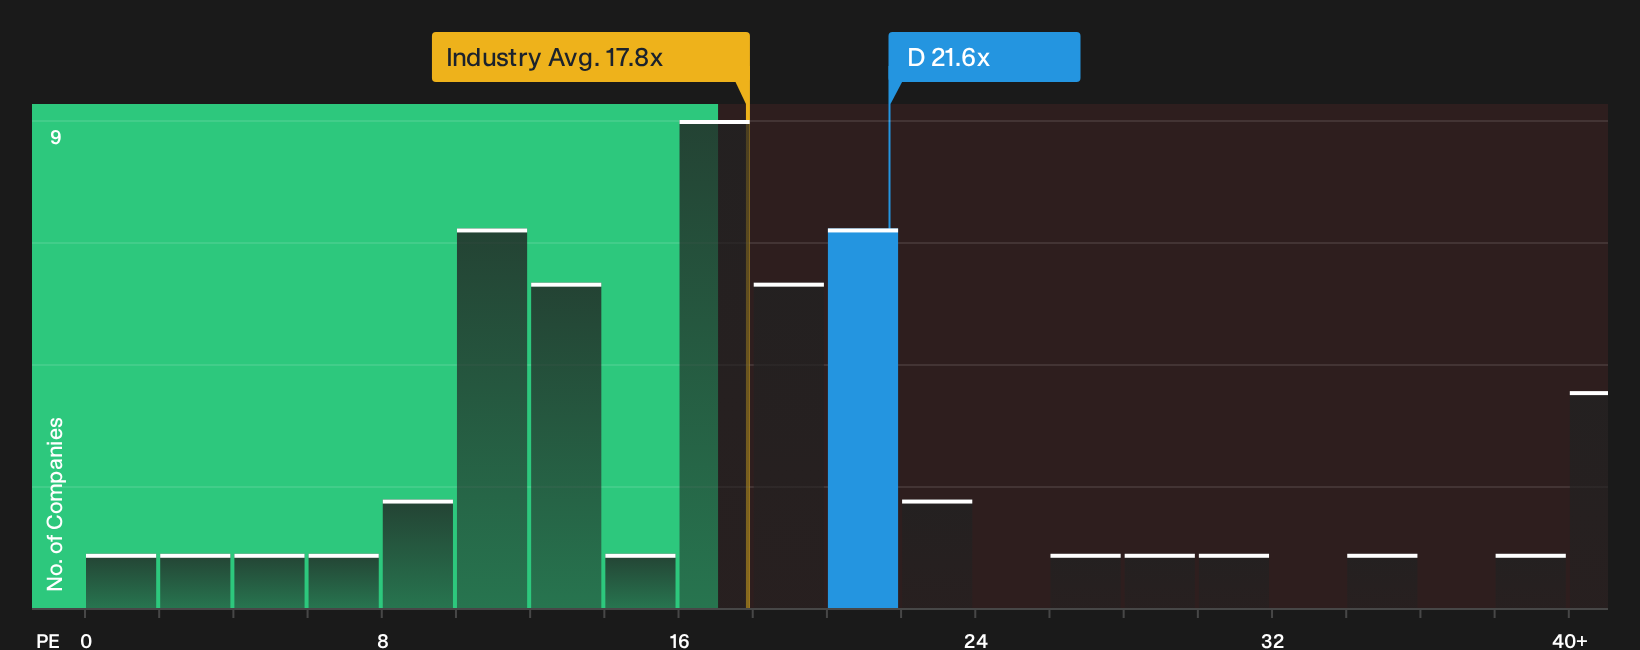
The P/E ratio fits Dominion Energy because earnings still anchor how investors weigh a regulated utility's value against its cash outlay and capital needs. Dominion Energy currently trades on a P/E of 21.6x, compared with about 17.8x for the broader Integrated Utilities group and 19.8x across its immediate peer set, so the earnings multiple carries a clear premium to the sector.
The Fair Ratio model, which adjusts for Dominion Energy's profit profile, size, industry and risk, points to a level close to where the shares trade today, so the stock looks roughly in line with what that framework would suggest. Because the proposed NextEra deal has pulled fresh attention to Dominion Energy's earnings outlook, that kind of middle ground valuation indicates the stock already reflects some optimism about future profitability without drifting far from a modelled anchor. Explore the numbers behind Dominion Energy's P/E valuation.
The Dominion Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Dominion Energy pick up where the valuation question leaves off. They spell out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today’s price on the Community page. Each scenario ties its number to a concrete view of how Dominion Energy's growth, profitability and risk profile might evolve, giving you a reference point to revisit as new information arrives.
One of the top community narratives on Dominion Energy: 14% undervalued
"Surging large-load demand in Dominion Energy’s Virginia territory, including over 53 GW of data center capacity in the pipeline, supports ongoing grid and generation buildout…"
Discover why this Narrative puts Dominion Energy at 14% undervalued.
Dominion Energy’s valuation still leaves one powerful variable unexplored
Numbers only tell part of the story, because the people setting Dominion Energy’s priorities, incentives and pay structures can tilt long term outcomes in ways the multiples alone never capture. See who runs Dominion Energy and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com