


Stewart Information Services (STC) has drawn fresh attention after a sharp share price pullback, with the stock down about 23% over the past month and 26% over the past 3 months.
That recent slide comes after a weaker stretch, with the share price down about 27.6% year to date and the latest close at US$50.70. The 1 year total shareholder return has declined 22.9%, but the 3 year total return is still up 30.9%. This suggests momentum has faded in the short term, even though longer term holders remain ahead overall.
Scan how Stewart Information Services compares with other pullback candidates across a hand picked group of 29 high quality undervalued stocks that combine quality fundamentals with discounted share prices.
After that drop, Stewart Information Services trades well below both analyst targets and one intrinsic value estimate, so the next step is simple: How far apart is price from a reasonable view of fair value?
Most Popular Narrative: 38.4% Undervalued
On the most followed view, Stewart Information Services screens as materially undervalued, with a fair value of $82.25 against the latest close at $50.70. That gap rests on specific expectations for how the business mix evolves.
Ongoing growth in Stewart Information Services’ commercial title operations in areas such as energy, data centers, industrial and site development, with commercial revenue having roughly doubled to about US$450 million over the last four quarters and commercial share rising toward the 13.5% to 14% range, could further lift segment revenue and adjusted pretax income if this mix continues to increase.
See why 2 investors see Stewart Information Services as 38% undervalued.
Result: Fair Value of $82.25 (UNDERVALUED)
Still, Stewart Information Services faces real pressure if housing activity stays weak and higher operating expenses in Real Estate Solutions and commercial services limit any margin progress.
Find out about the key risks to this Stewart Information Services narrative.
Another View: Stewart Information Services On Earnings Multiples
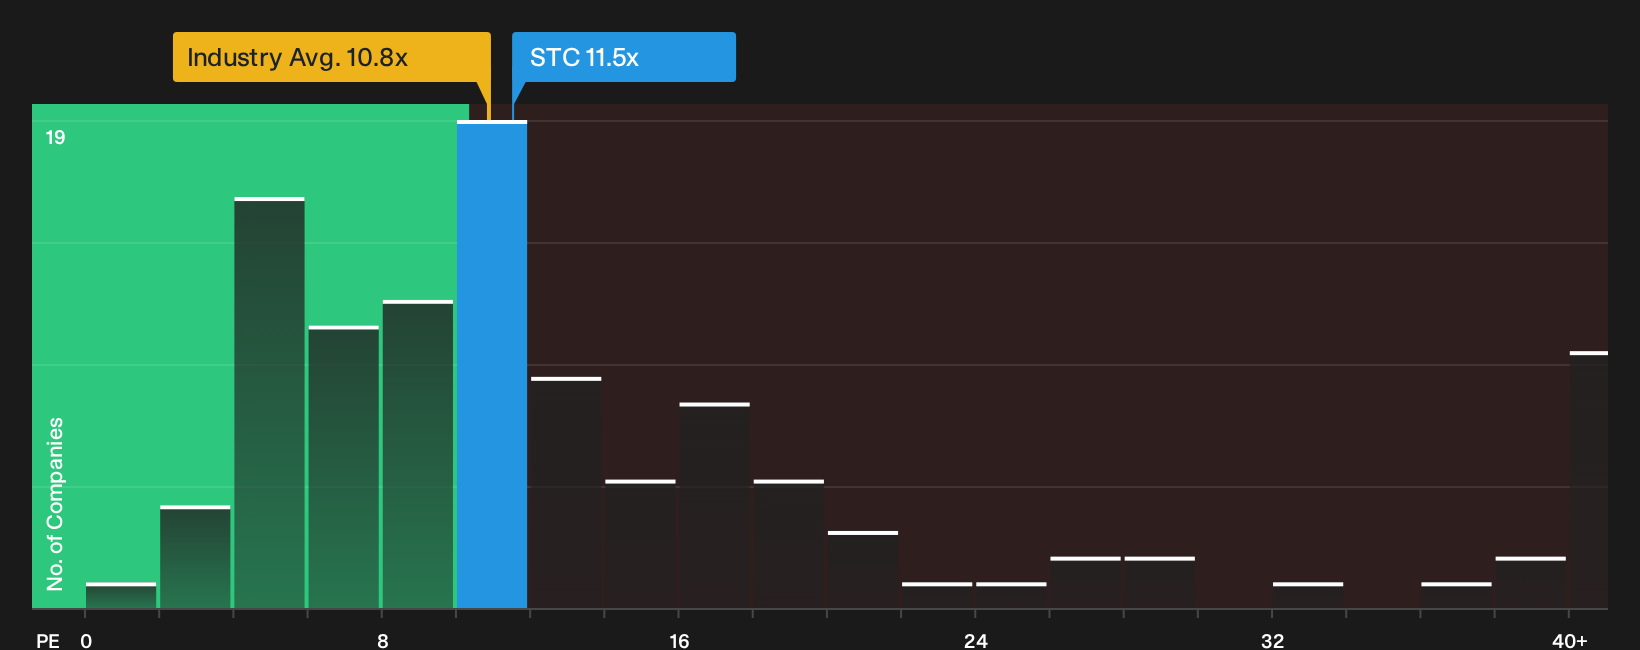
The analyst narrative presents Stewart Information Services as materially undervalued on future earnings with a US$82.25 fair value target. A simple P/E cross-check suggests a different perspective. At 11.5x earnings, STC trades above both the US Insurance industry at 10.8x and its peer set at 10.7x, while sitting below a fair ratio of 12.6x that the market could eventually lean toward.
For you as an investor, that combination of slightly richer pricing than sector and peer averages, but a discount to the fair ratio, points to a balance of upside potential and valuation risk that is less straightforward to interpret. It raises an uncomfortable but useful question: is the recent share price drop enough of a margin of safety if the higher multiple does not hold up?
See what the numbers indicate about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like these only matter if you pressure test them yourself and act while the data is fresh. Take a closer look at the company’s positive factors through 5 key rewards
Looking for more investment ideas beyond Stewart Information Services?
If you stop with Stewart Information Services, you risk missing other setups that fit your style. Put a few minutes into scanning targeted ideas that match what you actually want from your next position.
- Target higher income potential and stress test payout strength through a focused set of 8 dividend fortresses.
- Hunt for quality at a discount by scanning a curated 20 high quality undiscovered gems before the wider market pays attention.
- Prioritise resilience first and filter for durability with a research driven 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com