


CVR Energy has delivered a powerful run in recent years, and that kind of climb naturally raises a basic question for anyone looking at the stock today. Is the current share price at US$58.02 still in step with what the business earns, or have expectations moved ahead of its earnings power?
- CVR Energy has returned about 300.0% over the past 5 years, which puts a lot of weight on whether the current valuation can be backed up by its earnings profile.
- The company’s results hinge on how efficiently it can convert refining and related activities into consistent profits, which can influence how much investors are willing to pay for each dollar of earnings.
- Your read on CVR Energy is one view; the desks covering it have another. See what analysts think CVR Energy's shares could be worth.
The issue now is whether CVR Energy’s earnings are strong and reliable enough to justify where the stock trades today.
If you want to stress test CVR Energy’s earnings-based valuation against a broader set of ideas, compare it with the companies in the our screener containing 20 high quality undiscovered gems
Does CVR Energy Look Pricey on Earnings?
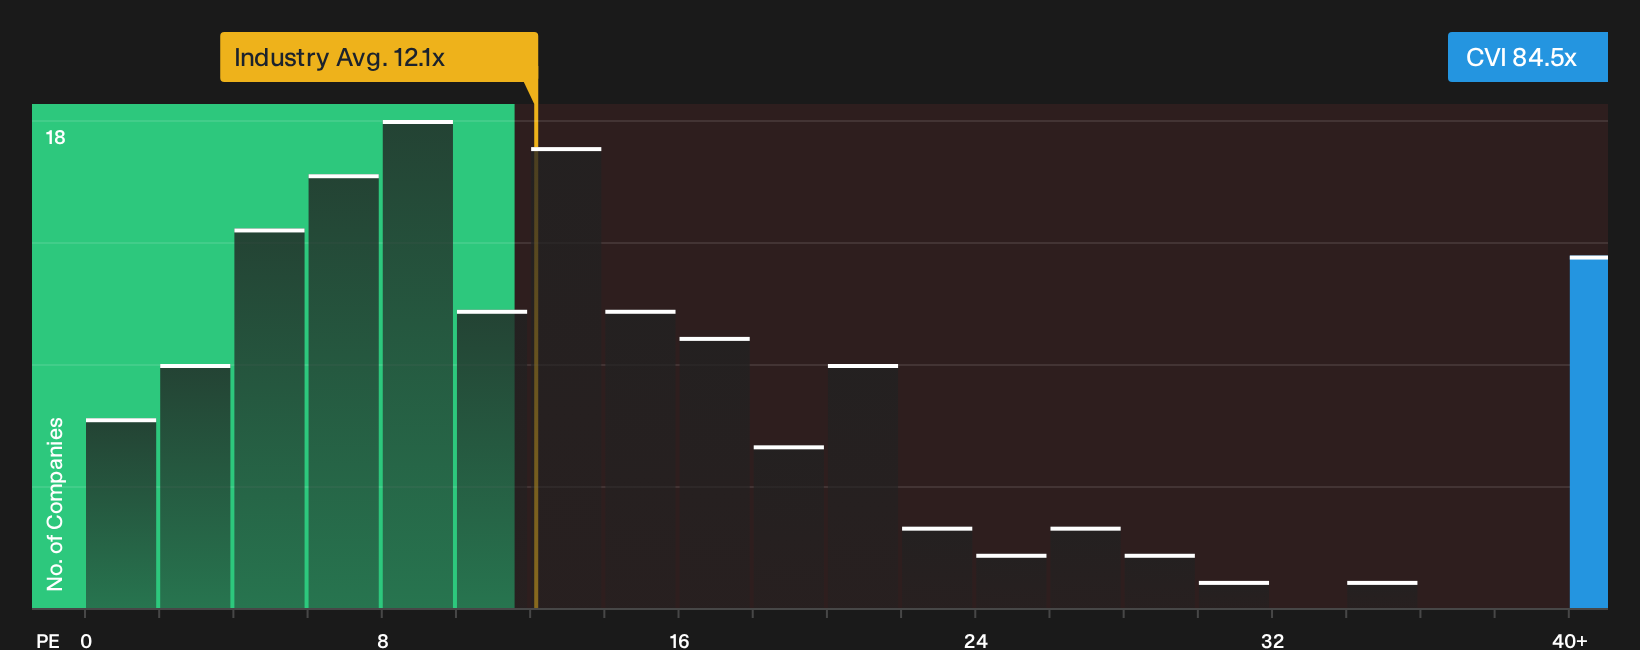
The P/E ratio fits CVR Energy because earnings are still the main anchor for how investors frame this refining and energy business. At about 84.5x earnings, CVR Energy trades at a far richer multiple than the wider Oil and Gas industry, where the typical P/E is roughly 12.1x, and also well above the peer group average of about 12.2x.
The model that blends CVR Energy’s growth outlook, profitability profile, size and risk suggests a materially lower P/E would be more in line with those fundamentals. This points to the stock being overvalued on this measure. For anyone considering the shares, that gap means you would want strong conviction about the durability and quality of future earnings before treating today’s price as attractive on an earnings basis. Explore the numbers behind CVR Energy's P/E valuation.
The CVR Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for CVR Energy pick up where this valuation puzzle leaves off by spelling out which assumptions on future growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price on the Community page. Each thesis sets out a view of CVR Energy’s fair value as a set of conditions about the business that investors can revisit over time to see how it holds up against new information.
One of the top community narratives on CVR Energy: 54% overvalued
"The current numbers, including sizable RIN expense, hedge losses and a modest recurring dividend, imply a share price that already reflects strong refining and fertilizer conditions…"
Discover why this Narrative puts CVR Energy at 54% overvalued.
One more CVR Energy angle that could change how you see the stock
Price tags and earnings multiples only tell part of the story, because the people steering CVR Energy and the way their pay is structured can heavily influence how your interests are treated over time. See who runs CVR Energy and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com