


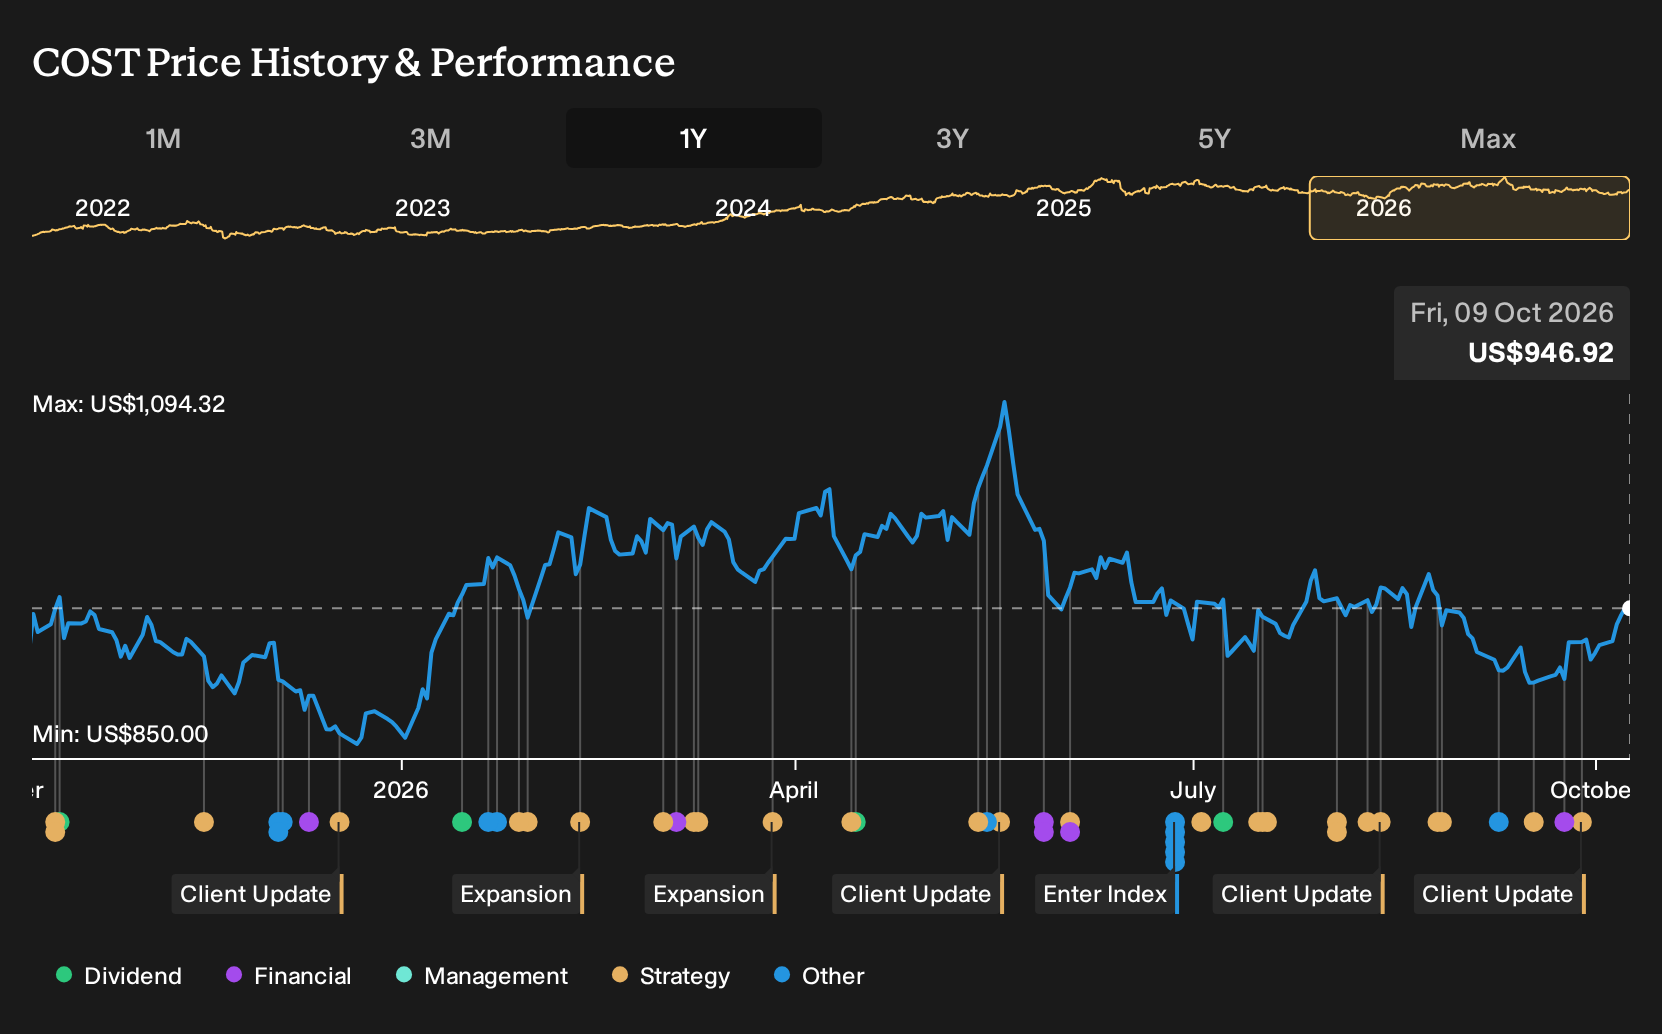
- Costco Wholesale reported September 2026 net sales of US$30.02b for the five weeks ended October 4, up 13.0% from US$26.58b a year earlier, alongside an update via a pre recorded sales and trading statement call.
- Stronger traffic in both warehouse and online channels points to consumers seeking value at Costco despite financial pressure, reinforcing how the membership model can pull more everyday spending into the warehouse club format.
- Now the focus shifts to what this stronger September sales performance means for Costco Wholesale's investment narrative built around membership driven warehouse expansion.
Costco Wholesale Investment Narrative Recap
To own Costco Wholesale, you need to believe the membership warehouse model can keep pulling more of each member’s wallet into both physical clubs and digital channels. The September net sales of US$30.02b, up 13.0% year on year, support that view but do not change the reality that membership growth has slowed and remains a key swing factor.
In the near term, the main catalyst is still execution on warehouse openings, higher capital spending and digital partnerships that can sustain traffic and mix. The biggest risk remains pressure on membership trends, along with foreign exchange and the beef pricing inquiry, none of which are meaningfully altered by one strong monthly sales update.
The September sales announcement is the clearest operational data point to link to Costco Wholesale right now. Comparable sales excluding gas and currency reportedly climbed 7.6% in September, which signals healthy underlying demand in the warehouse and online channels that management is building out through higher capital expenditure and broader delivery coverage.
For you as a shareholder, that same release ties directly into both catalysts and risks. Solid sales support the case for spending about US$7.5b in FY27 on roughly 30 net new warehouses per year and on expanding digitally enabled sales above US$33b. Any future slowdown in similar updates would quickly refocus attention on membership deceleration and regulatory scrutiny.
Costco Wholesale Analyst Expectations In Context
Analyst assumptions give you a rough roadmap for how Costco Wholesale might need to perform for current pricing and targets to make sense. The consensus view points to forecast revenue of about US$377.5b and expected earnings of US$12.2b by 2029, built on an annual top line growth rate of 7.6% and a small lift in profit margins from 3.0% today to 3.2% in three years.
On the earnings side, current profit of around US$9.2b would need to increase by roughly US$3.0b to reach that US$12.2b consensus estimate in 2029. That implies Costco Wholesale has to convert higher warehouse capital expenditure, a larger digital business and expanding ancillary services into meaningful incremental profit rather than just more volume.
Valuation expectations are closely linked to those operating targets. Analysts are effectively underwriting a 2029 outcome where Costco Wholesale generates US$377.5b in sales and US$12.2b in earnings and trades on a P/E of 47.4x, compared with about 44.4x today and 18.1x for the wider US consumer retail industry. For investors, the gap between those figures and today’s metrics highlights how much of the story depends on long term execution on membership engagement, international growth and digital adoption.
Costco Wholesale's narrative projects revenues of about US$377.5b and earnings of roughly US$12.2b by 2029. That path is built on 7.6% yearly revenue growth and an earnings increase of about US$3.0b from current earnings of around US$9.2b.
Uncover why Costco Wholesale's fair value indicates a 12% potential upside to its current price before the discount closes for Costco members and investors.
Exploring Other Perspectives
For Costco Wholesale, the bearish twist in the story centers on margin pressure rather than membership. The lowest analysts were penciling in only 6.4% annual revenue growth and about US$11.8b of earnings by 2029, before this September sales surprise. That gap with consensus shows how widely opinions can differ. It makes sense to explore both narratives and decide where you sit if forecasts shift after this update.
Explore 13 other Costco Wholesale fair value estimates, including one that suggests as much as 23% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Costco Wholesale research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Costco Wholesale. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Costco Wholesale's overall financial health at a glance.
Looking for more investment ideas beyond Costco Wholesale?
Once you have a view on Costco Wholesale, it can help to compare it with other opportunities that have different risk and income profiles using the Simply Wall St Screener.
- For investors who want potential mispricing with quality fundamentals, start with a focused set of 29 high quality undervalued stocks that already screen for both financial strength and attractive pricing.
- If capital preservation ranks high for you, consider a curated list of solid balance sheet and fundamentals (25 results) that can help you concentrate on companies with sturdier financial footing.
- Those looking to broaden their watchlist with off the radar opportunities can review a 20 high quality undiscovered gems that filters for lesser known businesses with strong underlying numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com