


Talos Energy has delivered a powerful 1 year share price run, which naturally puts fresh attention on what investors are paying for its sales today. With the stock now around US$16.80, the question is how well that price lines up with the revenue base behind the story.
- The share price has climbed 76.5% over the past year, so anyone looking at Talos Energy now is effectively betting on how its sales profile justifies that move.
- The business model is tightly tied to converting produced barrels into cash, so future spending needs and the timing of revenue can matter as much as headline top line growth for the valuation.
- Your read on Talos Energy is one view; the desks covering it have another. See what analysts think Talos Energy's shares could be worth.
The issue now is whether Talos Energy's current share price is well supported by its sales when set against the Fair Ratio benchmark.
If you are weighing Talos Energy on its sales and want extra context, a focused stock screen built on similar valuation angles can help. You can start with 29 high quality undervalued stocks.
Does Talos Energy Look Undervalued on Sales?
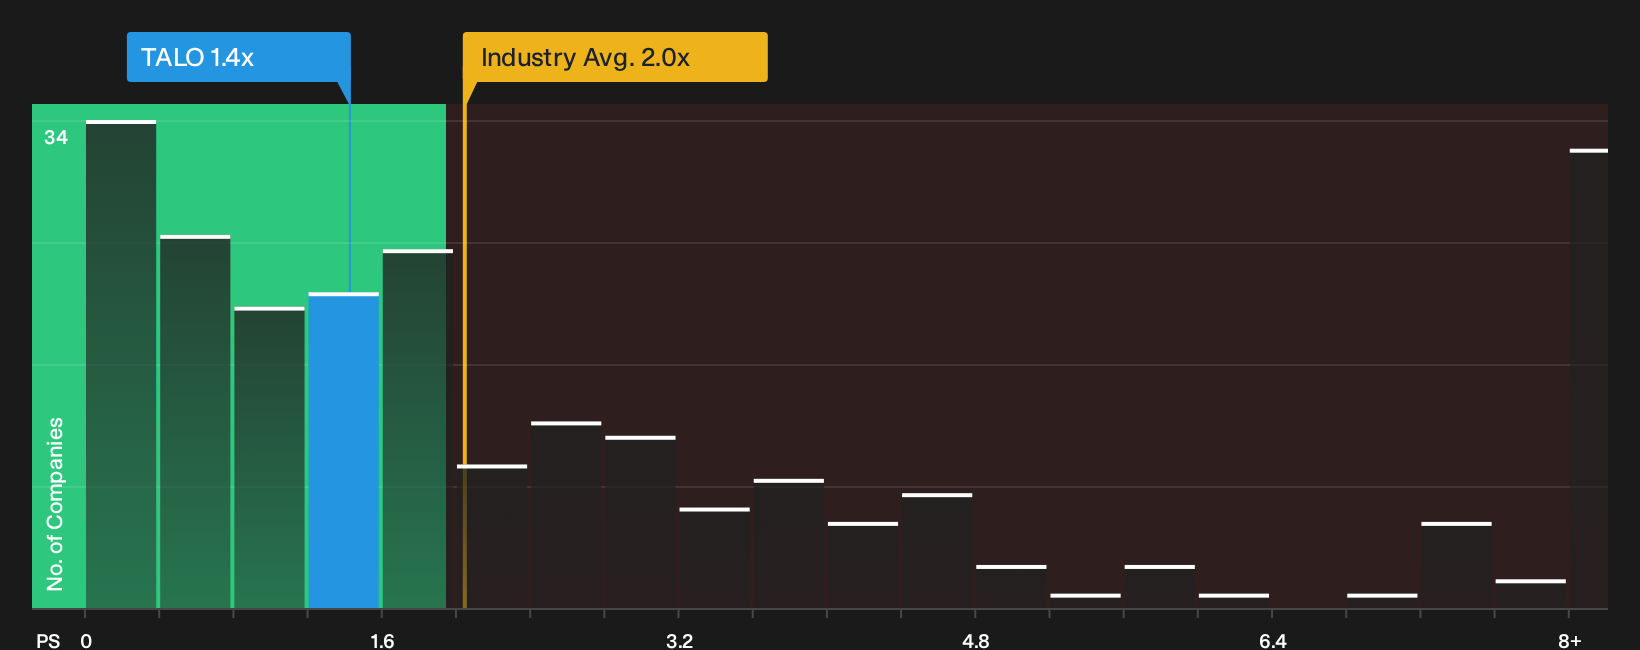
P/S is a clean way to look at Talos Energy because the business is built around turning barrels into revenue before anything else matters. On this lens, the stock trades on a P/S ratio of about 1.4x, compared with an Oil and Gas industry average near 2.0x and a peer group closer to 2.6x. That means investors currently pay less for each dollar of Talos Energy revenue than for many comparable producers.
The Fair Ratio framework, which estimates the multiple you might expect given the company’s growth profile, margins, size and risk, also points to a higher level than where the shares trade today. Talos Energy therefore screens as undervalued on sales compared with what that model suggests would be typical for a business with these characteristics. For anyone weighing whether the recent share price run already prices in the story, this gap on the P/S line is a key piece of the puzzle. Explore the numbers behind Talos Energy's P/S valuation.
The Talos Energy Narrative: What Would Justify Today's Price?
Talos Energy narratives on Simply Wall St build on this valuation puzzle and explain which potential paths for future growth, margins and earnings would need to occur for the stock to be worth materially more or less than today’s price. This helps you see what kind of future is implicitly being discussed. Each scenario links its figures to a clear view on how Talos Energy's growth, profitability and risks might change over time, which you can revisit as new information becomes available.
One of the top community narratives on Talos Energy: 30% undervalued
"The numbers imply that the current Talos Energy share price treats its low offshore cost base, growing production guidance, and planned shareholder returns as only partly valued by the market..."
Discover why this Narrative puts Talos Energy at 30% undervalued.
Talos Energy's valuation story leaves one crucial angle unexplored
The numbers around Talos Energy only go so far, since our broader checks also flag areas of concern that investors may want to weigh for themselves. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com