


Olympus (TSE:7733) is back in focus after a voluntary Class II recall of its BiCOAG Hemostasis Probe and a shake up in its boardroom and Compensation Committee in the same month.
Recent trading hints at investors weighing these developments carefully, with Olympus posting a 12.64% 90 day share price return and a 10.21% 1 year total shareholder return, even as the year to date share price return is down 1.70%.
Scan how investors are pricing recall and governance risk across the sector by comparing Olympus with a curated set of 23 resilient stocks with low risk scores.
After a recall, a board reshuffle and a 12.64% 90 day share price gain, Olympus now asks a simple question of investors: Does the current valuation still skew the risk reward toward buyers?
Most Popular Narrative: 8% Undervalued
Olympus closed at ¥2,000 against a widely followed fair value estimate of ¥2,184.62. The current price sits modestly below that narrative anchor while investors weigh recall and governance noise against longer term execution.
The reorganization into more customer-focused divisions, including Gastrointestinal Solutions and Surgical and Interventional Solutions, remains aimed at sharpening execution and market penetration so that future procedure volume growth can translate more directly into revenue and net margin gains.
See why 2 investors see Olympus as 8% undervalued.
Result: Fair Value of ¥2,184.62 (UNDERVALUED)
Still, this story can flip if China stalls again, or if U.S. tariffs linger longer than expected and squeeze the margin path that Olympus is priced for.
Find out about the key risks to this Olympus narrative.
Another View: Olympus Through The P/E Lens
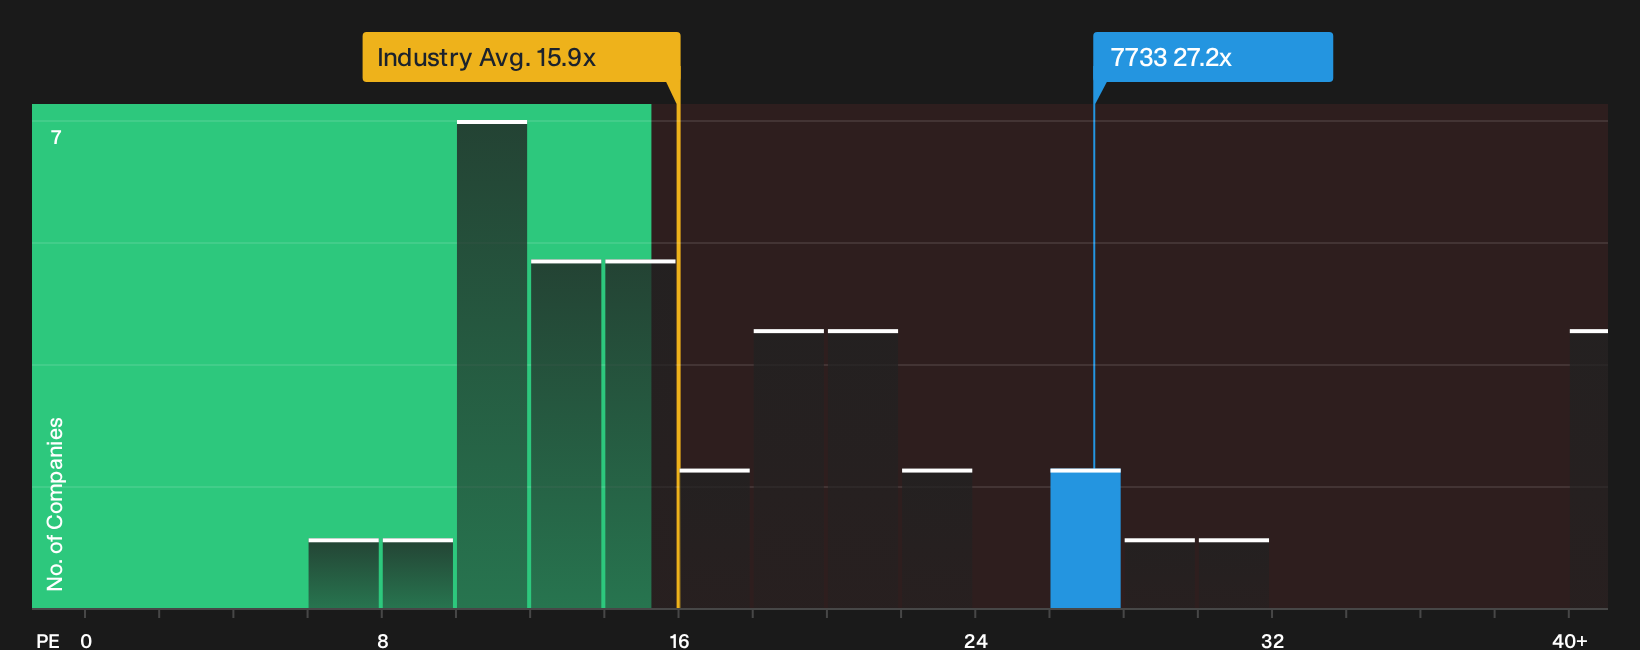
The story looks different when you swap the fair value narrative for plain P/E math. Olympus trades on a 27.2x P/E, compared with 15.9x for the JP Medical Equipment industry and a fair ratio of 26.5x. That richer multiple leaves less room for mistakes if the thesis on margins or China timing slips.
For investors, the question is simple: is that premium a reasonable price for execution risk, or a signal to demand a wider discount before feeling comfortable with Olympus at ¥2,000?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Olympus can feel messy, so move quickly from headline noise to your own take by weighing both sides through 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Olympus?
If Olympus has you thinking harder about risk, reward and price, use that momentum and widen your watchlist with a few focused stock searches.
- Target potential mispricing by scanning a curated pool of companies that screen as 12 high quality undervalued stocks.
- Strengthen your downside protection by concentrating on businesses with resilient finances using the list of solid balance sheet and fundamentals (22 results).
- Boost your income radar by zeroing in on companies highlighted as 28 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com