


Schaffhausen, Switzerland-based Garmin Ltd. (GRMN) designs, develops, manufactures, markets, and distributes a range of wireless devices. Valued at $51.8 billion by market cap, the company designs, develops, manufactures, and markets hand-held, portable, and fixed mount GPS-enabled products serving automotive, aviation, marine, outdoor, and fitness markets. The leading provider of navigation and communication devices is expected to announce its fiscal third-quarter earnings for 2026 before the market opens on Wednesday, Oct. 28.
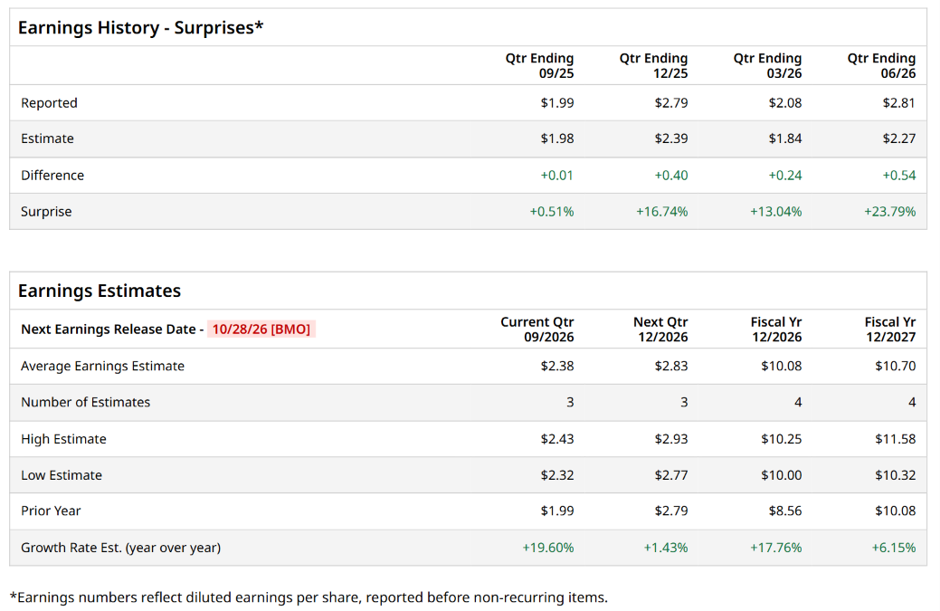
Ahead of the event, analysts expect Garmin to report a profit of $2.38 per share on a diluted basis, up 19.6% from $1.99 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
For the full year, analysts expect Garmin to report EPS of $10.08, up 17.8% from $8.56 in fiscal 2025. Its EPS is expected to rise 6.2% year over year to $10.70 in fiscal 2027.
GRMN stock has underperformed the S&P 500 Index’s ($SPX) 16% gains over the past 52 weeks, with shares up 4.6% during this period. Similarly, it underperformed the State Street Technology Select Sector SPDR ETF’s (XLK) 37% gains over the same time frame.
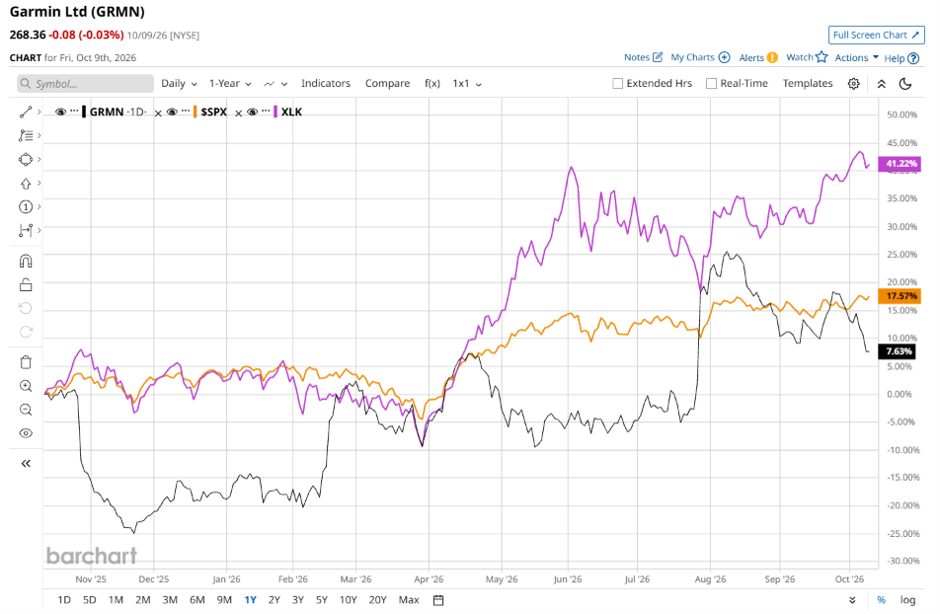
Despite strong fundamental performance across core segments like Fitness and Aviation, GRMN faced periods of relative market underperformance due to macroeconomic headwinds and elevated investor expectations. Broader consumer discretionary spending pressure weighed on high-end hardware demand, while rising component costs particularly in memory chips and potential supply chain expenses pressured margins, dampening investor momentum during periodic sell-offs.
On Jul. 29, GRMN shares jumped 16.2% after reporting its Q2 results. Its adjusted EPS of $2.81 beat Wall Street expectations of $2.27. The company’s revenue was $2 billion, exceeding Wall Street forecasts of $1.9 billion. GRMN expects full-year adjusted EPS to be $10, and revenue is expected to be $8.1 billion.
Analysts’ consensus opinion on GRMN stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of eight analysts covering the stock, three advise a “Strong Buy” rating, four give a “Hold,” and one recommends a “Moderate Sell.” GRMN’s average analyst price target is $294.14, indicating a potential upside of 9.6% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.