


With a market cap of $26 billion, FirstEnergy Corp. (FE) is a diversified energy company that generates, transmits, and distributes electricity through its subsidiaries across the United States. Operating through its Distribution, Integrated, and Stand-Alone Transmission segments, the company serves customers in six states with a mix of coal, nuclear, hydroelectric, wind, and solar energy sources.
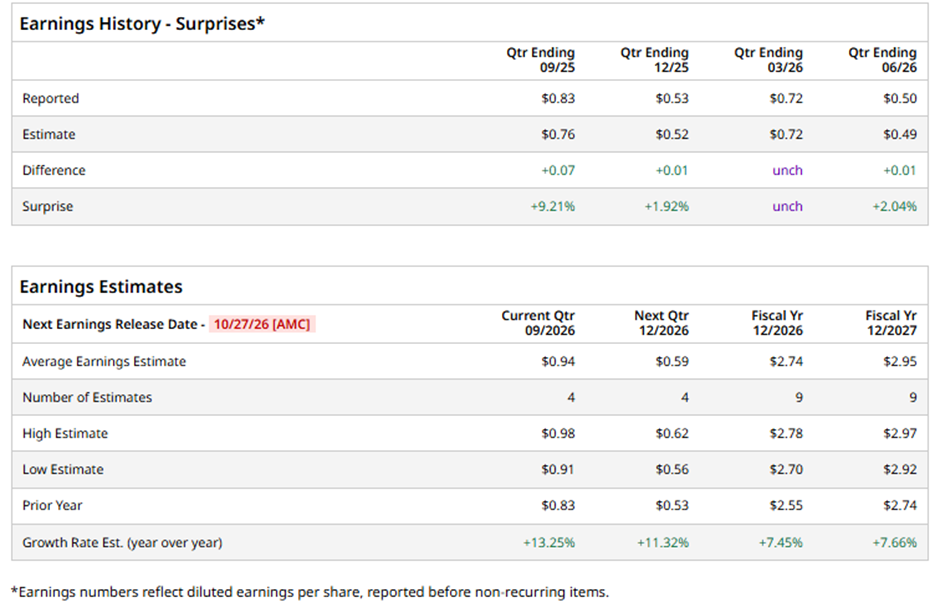
The Akron, Ohio-based company is slated to announce its fiscal Q3 2026 results after the market closes on Tuesday, Oct. 27. Ahead of this event, analysts expect the company to report a profit of $0.94 per share, up 13.3% from $0.83 in the year‑ago quarter. It has exceeded or met Wall Street's earnings expectations in the past four quarters.
For fiscal 2026, analysts project the utility company to post EPS of $2.74, a rise of 7.5% from $2.55 in fiscal 2025. Moreover, EPS is anticipated to grow 7.7% year-over-year to $2.95 in fiscal 2027.
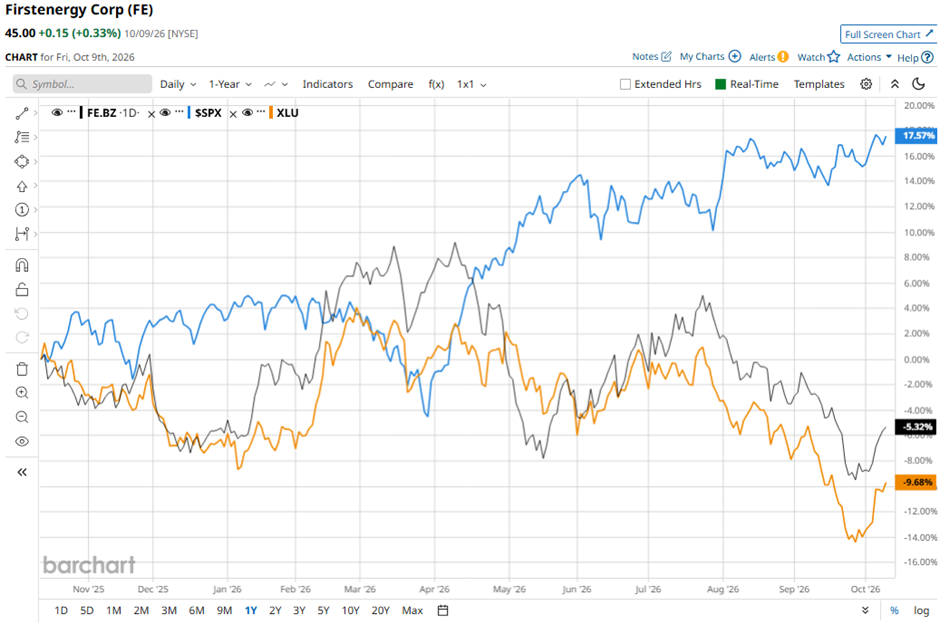
Shares of FirstEnergy have fallen 3.6% over the past 52 weeks, lagging behind the broader S&P 500 Index's ($SPX) nearly 16% return. However, the stock has shown a less pronounced decline than the State Street Utilities Select Sector SPDR ETF's (XLU) 8.6% drop over the same period.
FirstEnergy reported higher Q2 2026 results on Jul. 28, with profit of $288 million, or $0.50 per share, compared with $268 million, or $0.46 per share, a year earlier, driven by rising data center demand and more efficient operations. Data center demand (contracted and pipeline) increased 30% quarter over quarter to 6.4 GW, while demand in West Virginia surged 137% to 4.3 GW, reflecting growing electricity requirements from data centers.
The company reaffirmed its full-year core earnings guidance of $2.62 per share - $2.82 per share and its target of 6% - 8% compound annual growth from 2026 to 2030, although adjusted earnings of $0.50 per share fell slightly short of analysts’ estimate.
Analysts' consensus view on FE stock remains cautiously optimistic, with a "Moderate Buy" rating overall. Out of 16 analysts covering the stock, seven recommend a "Strong Buy," one "Moderate Buy," and eight "Holds." The average analyst price target is $52.62, indicating a potential upside of 16.9% from the current levels.
On the date of publication, Sohini Mondal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.