


Rate worries are back. On Oct. 7, the 10-year Treasury yield hit 5.36%, its highest level in 24 years. Fresh Fed minutes added fuel, showing most policymakers thought another rate hike before year-end made sense. Stocks didn't take it well; the S&P 500 ($SPX) slipped 0.22%, the Dow Jones Industrial Average ($DOWI) fell 0.66%, and the Nasdaq 100 ($IUXX) gave up 0.21%.
That kind of market usually sends investors hunting for steady cash flow and fat dividends, and tobacco stocks check both boxes. Altria Group (MO) sits at the center of that trade. The company bumped its quarterly dividend by 4.7% in August, from $1.06 to $1.11 per share, and MO stock is up more than 24% so far in 2026.
But there's a catch. Higher yields give investors other places to earn income, so Altria has to work harder to justify its risks. With Altria's Oct. 29 third-quarter earnings report around the corner and management guiding for 2026 adjusted EPS of $5.61 to $5.72, does MO stock still offer enough income and growth to be worth owning as rate fears build? Let’s take a closer look.
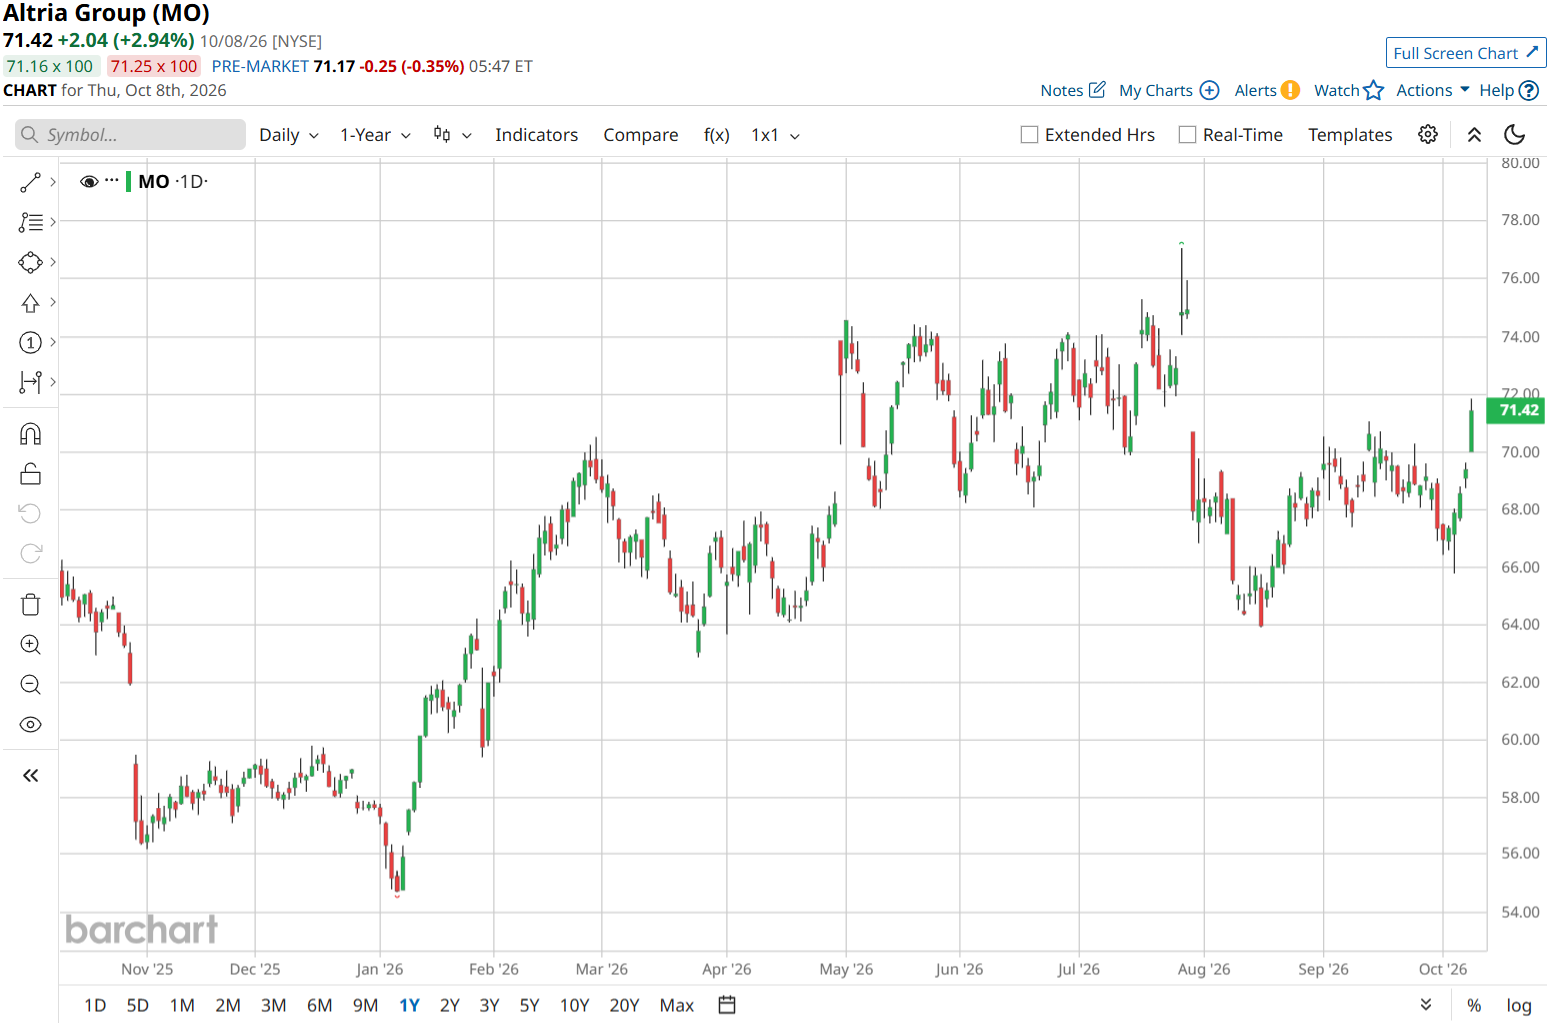
Altria’s Fundamentals Face the Market Test
Altria's Q2 results showed that its pricing power is still doing the heavy lifting as cigarette demand shrinks, although the quarter wasn't perfect. Revenue excluding excise taxes rose 1.2% year-over-year (YOY) to $5.36 billion, which was in line with the $5.35 billion analysts expected, while adjusted EPS climbed 2.8% to $1.48, just shy of the $1.50 forecast.
Operating margin also slipped to 58.6% from 61.1% in the year-ago period. Still, first-half adjusted EPS rose 4.9% to $2.80. Altria also handed nearly $3.9 billion back to shareholders through dividends and buybacks. That was enough for management to lift the low end of its 2026 adjusted EPS guidance to $5.61 to $5.72, good for 3.5% to 5.5% growth.
Altria is also looking for savings beyond price hikes. In August, the company's Philip Morris USA unit signed a contract-manufacturing deal with non-U.S. affiliates of Philip Morris International (PM), with first shipments expected in early 2027. The tie-up could make manufacturing more efficient, cut costs, and open doors to international nicotine markets, although management says it won't move the needle on 2026 results. For now, any further upside this year comes down to delivering on guidance and investors sticking with its defensive income story.
Tobacco Stocks Have Appeal as Rate Concerns Resurface
Money started moving into tobacco stocks on Oct. 7 as Treasury yields jumped and the rest of the market stumbled. The 10-year yield touched 5.36% after minutes from the Fed's September meeting showed most policymakers thought one more rate hike before year-end was the right call. Rising oil prices stoked inflation worries, too, putting extra heat on bonds and rate-sensitive stocks.
Investors responded by showing greater interest in tobacco stocks. The logic is simple: These companies bring in steady cash and pay hefty dividends, two things that look a lot better when rising rates rattle growth stocks and cloud the outlook for valuations. Altria fits that bill. Its board raised the quarterly dividend 4.7% to $1.11 per share in August 2026, taking the annualized payout to $4.44.
But higher rates cut both ways for MO stock. A 10-year Treasury yield above 5% gives income investors a government-backed option, and that can dull the shine on dividend stocks. So, tobacco's latest run is really a hunt for defensive earnings and income, not automatic shelter from higher rates. Altria still has to deliver enough yield, earnings growth, and stability to make taking on equity risk worth it.
What Does Wall Street Expect for Altria?
Altria will report its September-quarter results before the market opens on Oct. 29. Wall Street expects adjusted EPS of $1.50 per share, up more than 3% from $1.45 a year ago. For all of fiscal 2026, analysts see EPS reaching $5.67, a nearly 5% YOY increase from $5.42 per share in fiscal 2025.
Analyst opinion is split. On July 7, UBS analyst Faham Baig kept a “Buy” rating on MO stock and raised his target from $76 to $79 per share. Baig sees value in Altria’s pricing power, earnings growth, and higher capital spending. Barclays analyst Pallav Mittal sees it differently, however. On Aug. 11, Mittal kept an “Underweight” rating while lowering his price target from $64 to $58 per share.
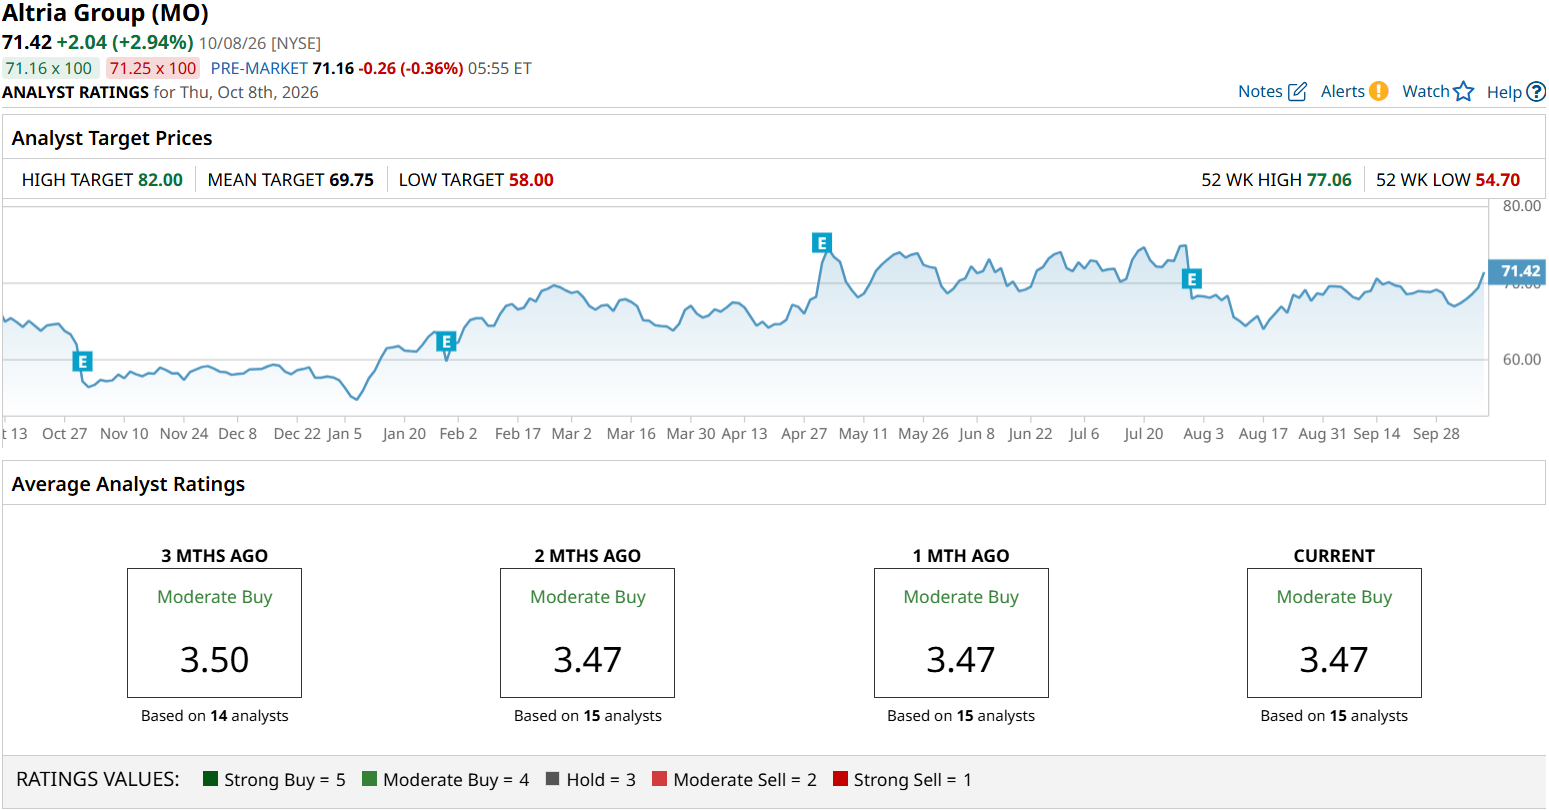
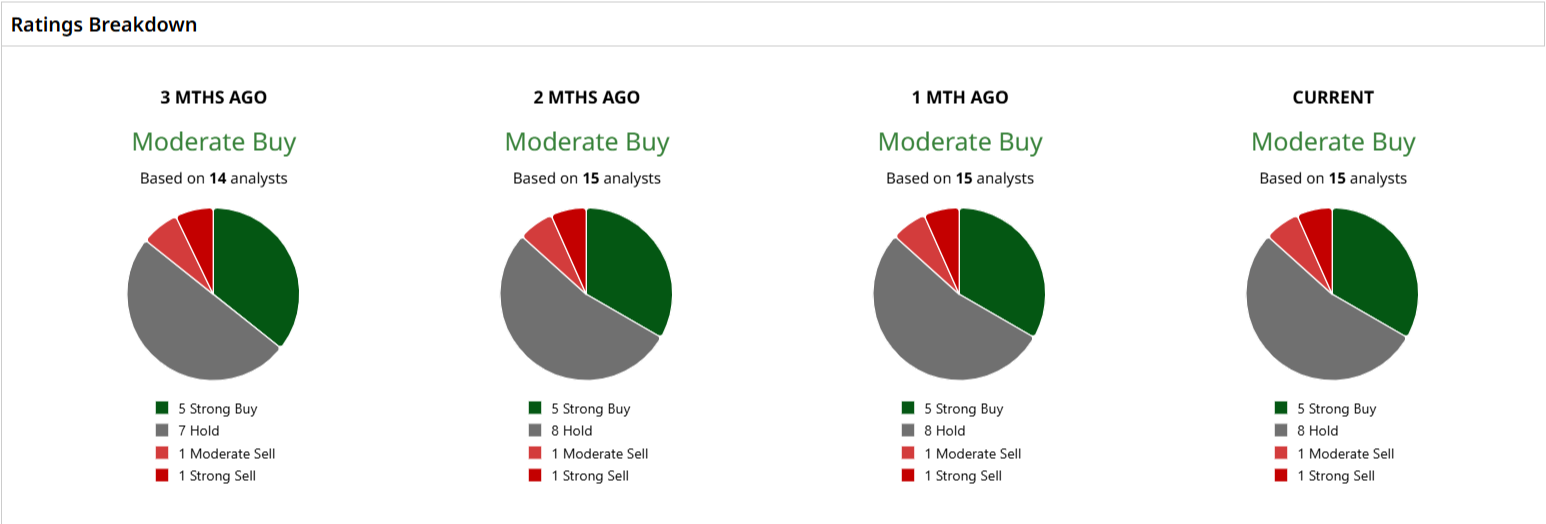
Overall, Altria stock has a consensus “Moderate Buy” rating based on 15 analysts with coverage. The average price target of $69.75 sits roughly 3% below current price levels, suggesting Wall Street sees limited room for gains from here.
Conclusion
So, how should investors view MO stock now? As a solid income play, not a breakout story. Altria brings with it steady pricing power, a recently raised dividend yielding more than 6%, and mid-single digit earnings growth, which fits the current rotation into defensive names as rate anxiety builds. But with the stock trading slightly above its mean target, expectations are already baked in. Shares will likely move sideways to modestly higher from here, with the hefty dividend providing a cushion while the Oct. 29 earnings report sets the next leg. For patient income investors, MO stock still earns its place. Just do not expect fireworks.
On the date of publication, Ebube Jones did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.