


- Williams Companies is pushing ahead with large-scale expansions like the Shelby Connector and Delta Access projects. These are designed to move more Western Haynesville natural gas to Gulf Coast LNG and power customers on a fee-based model.
- The build out of this extra capacity gives Williams Companies more ways to link its gathering network to long haul pipelines. This can deepen customer reliance on its system and concentrate future earnings in long duration contracts rather than short term commodity swings.
- We will now look at how Williams Companies' expansion of Shelby Connector capacity could reshape the existing investment narrative that investors rely on.
Scan the natural gas pipeline space for other Williams Companies style infrastructure plays that could benefit from similar fee-based momentum by checking the curated 43 power grid technology and infrastructure stocks
Williams Companies Investment Narrative Recap
For Williams Companies, the core belief is that fee-based gas transport and gathering will stay in demand from utilities, LNG facilities, and power generators. The current build out, including Shelby Connector and Delta Access, is about filling that role with more contracted capacity. The key short term swing factor is execution, keeping projects moving on time and on budget while integrating them into the existing system.
The biggest near term worry is still capital intensity and funding. Growth capex of about US$7.3b for 2026, higher leverage near 4.1x, and debt that is not well covered by operating cash flow put pressure on financial flexibility. The recent project news does not remove that risk. It instead raises the bar on delivery.
The Shelby Connector expansion sits at the center of the current story because it links Western Haynesville gas volumes to Gulf Coast LNG and power buyers on a fee basis. That aligns with Williams Companies focusing on segment EBITDA from long term contracts rather than short term commodity moves. For investors, the interest is straightforward. More contracted throughput can support more stable earnings.
Project success still depends on permitting, construction performance, and customer follow through. A setback on Shelby Connector or Delta Access would matter, given the size of the capex and the expectation that Haynesville and LNG demand will support higher utilization. As you weigh the stock, the question is how comfortable you are with that execution track in light of elevated leverage and a dividend that is not fully covered by free cash flow.
Williams Companies' narrative projects US$17.2b revenue and US$4.4b earnings by 2029. This is based on an assumed 11.9% yearly revenue growth rate and an earnings increase of about US$1.3b from US$3.1b today.
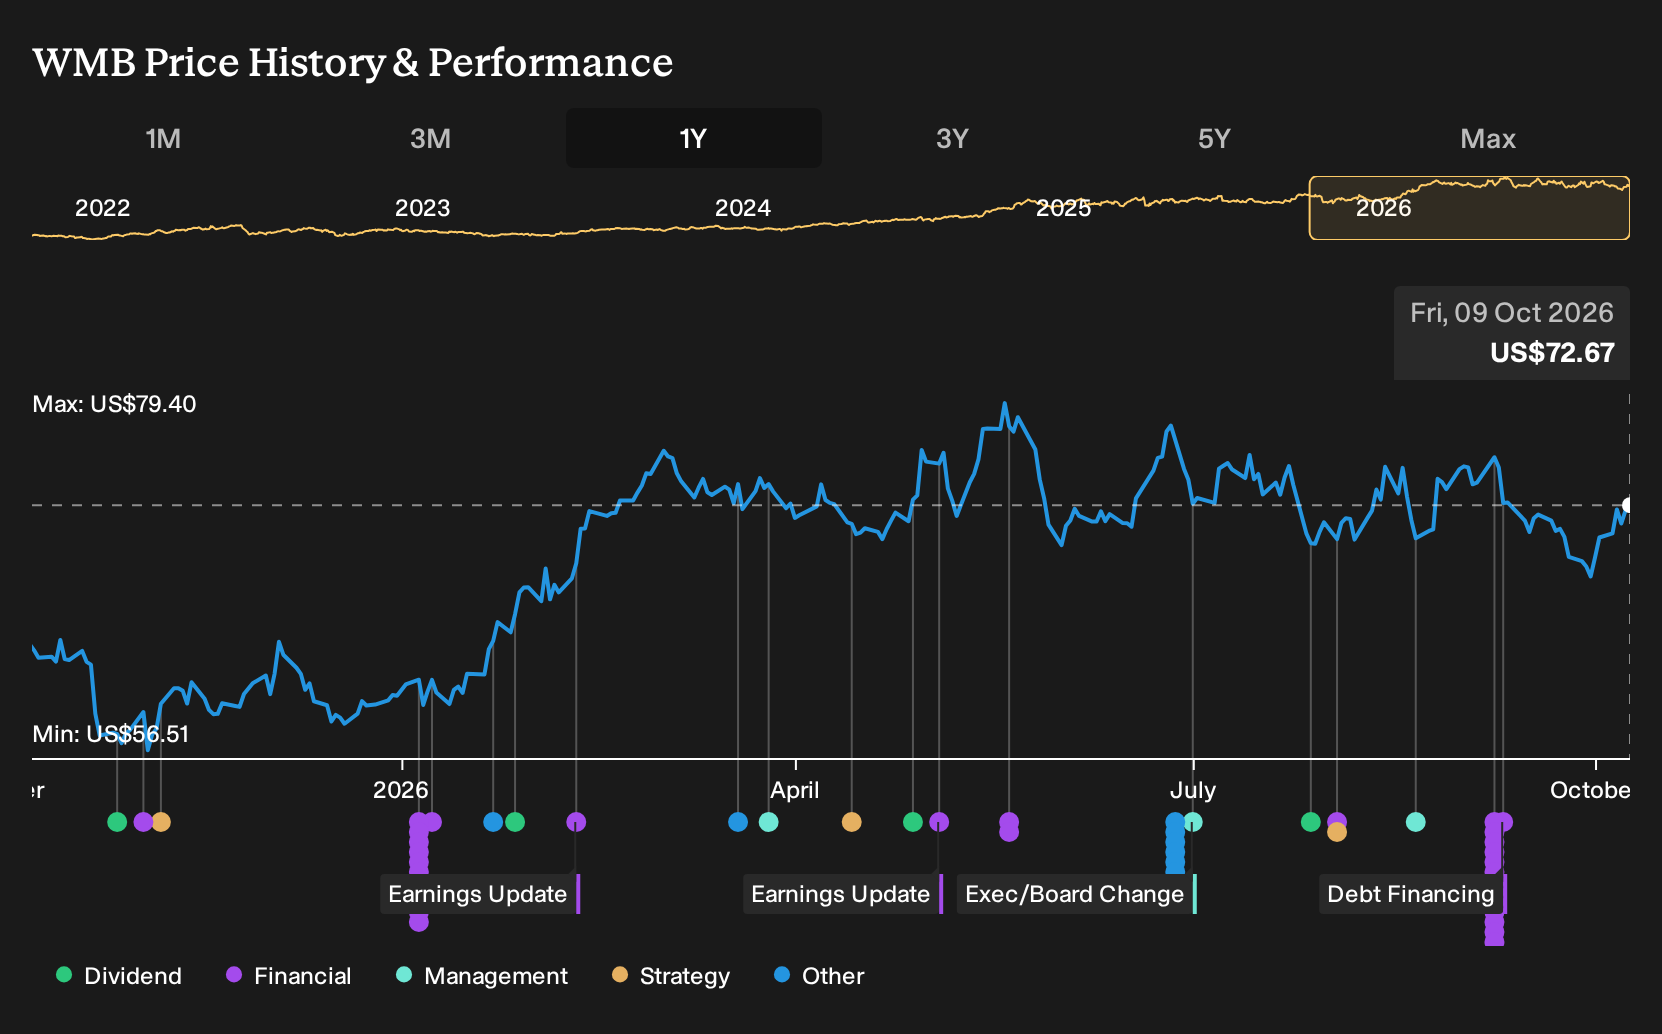
Uncover why Williams Companies' fair value indicates an 18% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view puts far more weight on the risk that Williams Companies overbuilds for data center and LNG demand that later disappoints. Those bearish analysts only had Williams reaching about US$16.7b in revenue and US$3.6b in earnings by 2029. That is a much cooler story, and it may shift as this latest project news sinks in.
Explore 4 other Williams Companies fair value estimates, including one that suggests it could be worth just $73.34.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Williams Companies research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Williams Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Williams Companies' overall financial health at a glance.
Looking for more Williams Companies style ideas?
If the Williams Companies story has you thinking about how fee-based infrastructure fits into your portfolio, it can help to widen the lens and compare it with other businesses that share traits like resilient balance sheets, consistent income, or potential mispricing.
- If capital preservation matters most to you, start with companies that screen well on stability and risk by reviewing 31 resilient stocks with low risk scores.
- If you are hunting for opportunities where price and fundamentals look out of sync, line up candidates using the 29 high quality undervalued stocks.
- If steady cash payouts appeal to you, focus on income heavy opportunities through the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com