


Rising Treasury yields are pressuring borrowing costs, and big US banks are about to show how that strain is flowing through households and companies. Reliable cash payouts suddenly look more attractive when bonds and savings accounts compete harder for attention. That is where a group of higher yielding dividend payers, all screened for coverage, growth and stability, can help. This article highlights three standouts from that shortlist.
The three stocks in this article are just a starter pack, and the full screen surfaced 175 more companies with similar income stories and different sector angles that are not covered here. To identify and analyze the highest conviction dividend payers that match your own criteria, head straight into the Dividend Powerhouses (3%+ Yield) screener.
NIKE (NKE)
Overview: NIKE is a global sportswear business that designs, manufactures, and sells athletic footwear, apparel, and accessories across retail and digital channels.
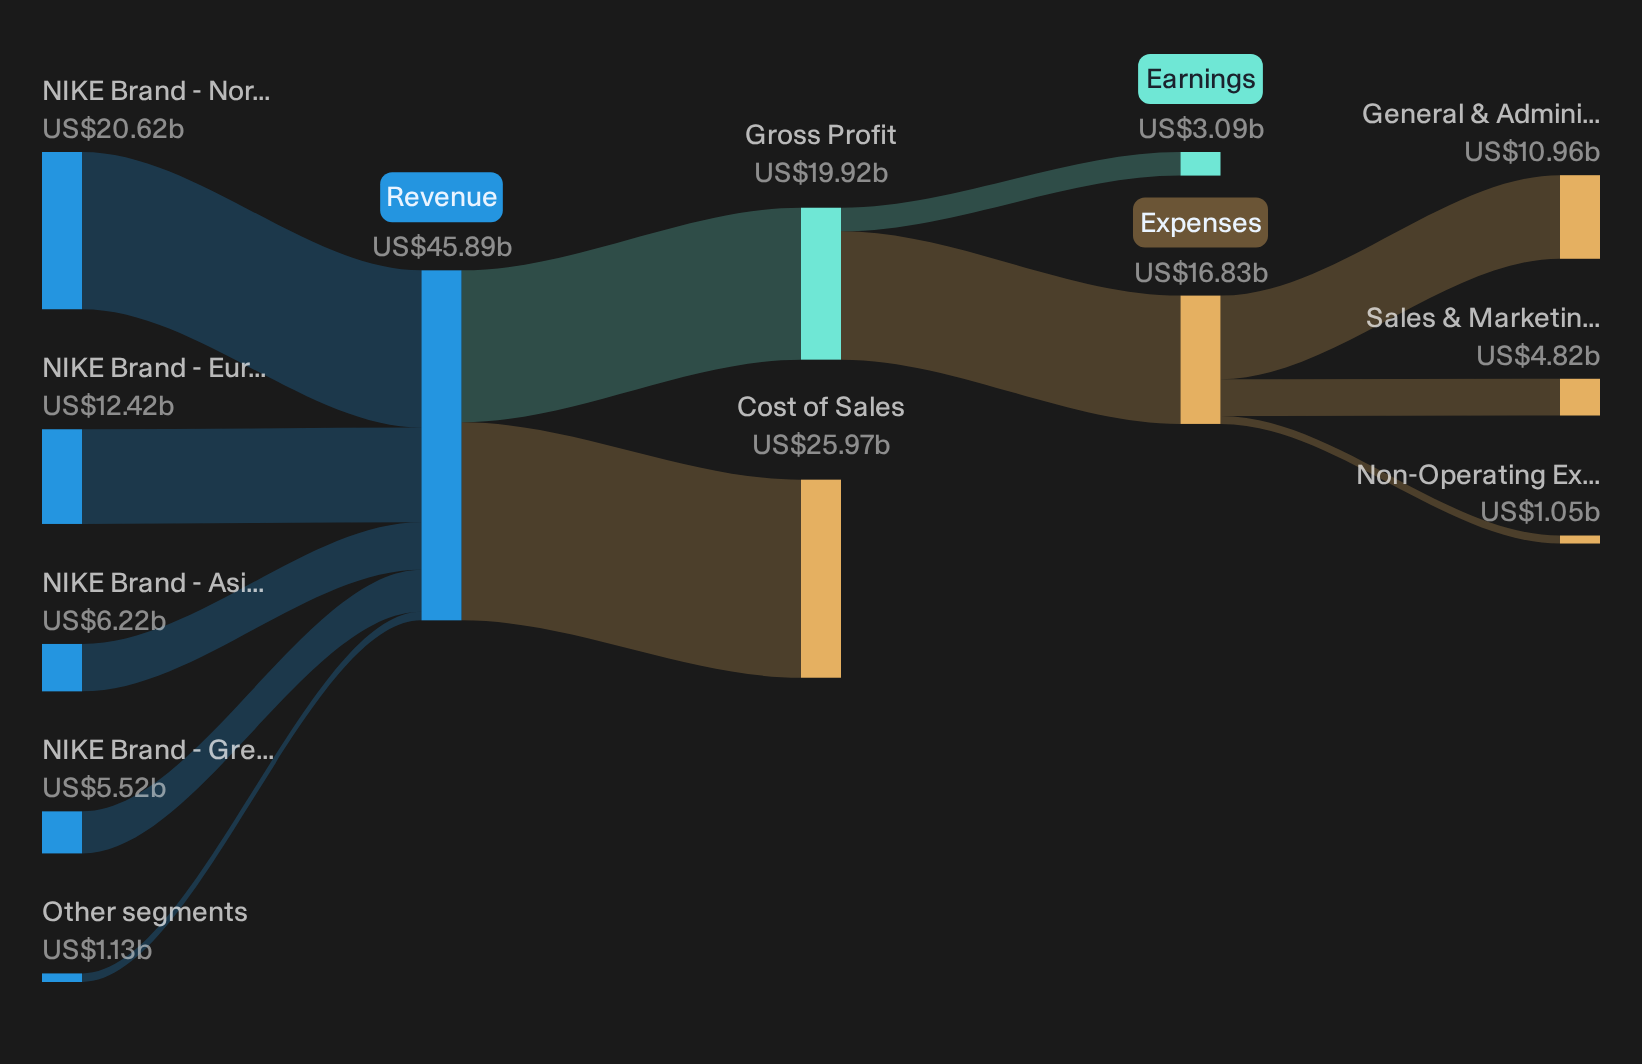
Operations: NIKE generates most revenue from the NIKE Brand in North America at about US$20.6b, with sizeable contributions from Europe, Middle East and Africa at US$12.4b, Asia Pacific and Latin America at US$6.2b, Greater China at US$5.5b, and Converse at US$1.1b.
Market Cap: US$51.6b
NIKE matters for a dividend-focused screen because its global footwear and apparel engine funds a sizeable cash payout that investors watch closely.
"Management is rebuilding Nike around sport and accepting lower revenue now for healthier, full-price demand later. The big risk is that "restored" settles at a 9 to 11% margin, not 13%, which would leave Nike fairly valued at today's price rather than cheap."
What happens if one pressure on NIKE’s cash generation quietly keeps dividend outflows running ahead of the underlying free cash inflows.
That dividend squeeze is only part of the story, and the full narrative for NIKE shows how NIKE’s reset could turn current pressure into a stronger long term cash engine.
Brown-Forman (BF.B)
Overview: Brown-Forman is a Louisville based spirits producer whose Jack Daniel’s led portfolio fuels a long running, cash rich dividend stream.
Operations: Brown-Forman generates about US$3.9b from beverage alcohol consumer products, with US$1.9b reported in the United States and further international sales adjustments.
Market Cap: US$12.2b
For income investors, Brown-Forman matters because dependable cash coming off premium whiskey and tequila brands is what underpins its 3%+ dividend profile.
"Growth in ready to drink products like New Mix, el Jimador Spritz and Jack Daniel’s Tennessee Blackberry, which together are adding multi point value growth contributions in key markets, is creating a higher volume platform that can add to revenue while partially offsetting the impact of softer full strength spirits demand on operating income."
What really decides how compelling that payout looks over the next few years is how one quiet margin headwind ultimately resolves.
That slow burn margin question is where the real opportunity sits, and the full narrative for Brown-Forman lays out how Brown-Forman’s premium positioning could turn pressure into accelerating dividend strength.

Accenture (ACN)
Overview: Accenture helps large organizations run and modernize core operations through consulting, outsourcing and managed cloud, data and AI services that support recurring, contract-backed cash flows.
Operations: Accenture generates about US$22.5b from Products clients, US$15.2b from Health & Public Service, US$14.0b from Financial Services, US$12.7b from Communications, Media & Technology, and US$9.9b from Resources across the Americas, Asia Pacific and EMEA.
Market Cap: US$124.6b
Accenture earns a place in this Dividend Powerhouses screen because its business-process outsourcing and managed services work, especially around cloud and AI, generates steady cash that helps cover a payout above 3%.
"The market is asking whether Accenture can convert AI from a threat into a growth engine."
What really determines how secure that dividend feels over time is how one quiet shift in AI driven service mix ultimately feeds through to margins.
That margin question is exactly where the opportunity starts, and the full narrative for Accenture shows how Accenture’s AI shift could turn today’s uncertainty into accelerating dividend cover.

Seeking Alternatives Before Momentum Flies
Fresh ideas often move first, then the crowd catches up and entry points start dropping. Scan these under the radar for now opportunities while it matters and aim to get in early.
- Identify resilient balance sheets before the crowd by running the list of solid balance sheet and fundamentals (25 results) and focus on businesses structured to handle tougher conditions.
- Explore the next leg of AI-related momentum by scanning the 39 profitable AI stocks that aren't just burning cash so you can concentrate on cash-generating operators instead of purely speculative story stocks.
- Evaluate potential exposure to real assets by checking the curated 36 elite gold producer stocks and review producers that could be positioned to benefit if investor attention shifts toward metals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com