


Why Sun Life Financial stock is back in focus
Sun Life Financial (TSX:SLF) is drawing fresh attention after its U.S. arm folded the Health Navigator advisory service into disability coverage, adding care guidance to a benefit that usually focuses on income protection.
Recent trading has been a mixed bag for Sun Life Financial, with the share price easing over the past week and quarter while still sitting at CA$109.82 after a strong year to date share price return of 27.22% and a 1 year total shareholder return of 32.49%.
Scan 8 resilient stocks with low risk scores, chosen for resilient balance sheets and steadier profiles, if Sun Life Financial's health focused move has you thinking about durability as much as upside.
Sun Life Financial trades at a modest discount to analyst targets and at a much wider gap to some intrinsic value estimates. Yet recent caution around the shares has lingered. Is the Health Navigator expansion a reason for that gap to narrow or stay put?
Most Popular Narrative: 4% Undervalued
On the most followed view, Sun Life Financial screens modestly cheap, with a narrative fair value of CA$114.69 against a last close of CA$109.82. That gap rests on specific growth engines rather than a vague quality label.
Strong growth in Asia individual insurance sales, with $875 million of quarterly sales and over $7 billion of contractual service margin in the region, supports the view that Sun Life Financial can keep expanding its addressable market and add new premium and fee income streams that feed into earnings growth.
See why 69 investors see Sun Life Financial as 4% undervalued.
Result: Fair Value of CA$114.69 (UNDERVALUED)
Still, the Sun Life Financial story hinges on problem areas like U.S. Dental and any renewed pressure on asset management fees that could unsettle this fair value case.
Find out about the key risks to this Sun Life Financial narrative.
Another view on Sun Life Financial's valuation
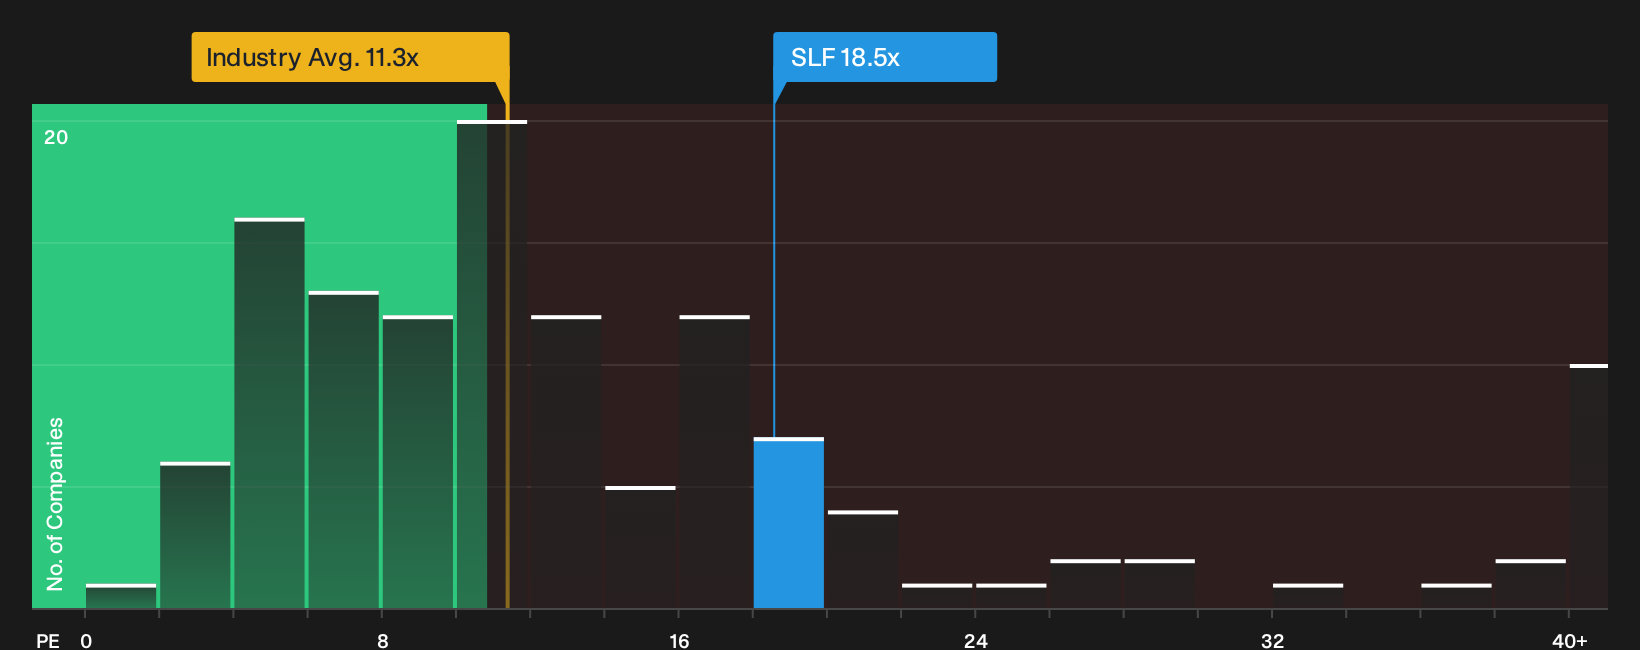
The fair value narrative for Sun Life Financial leans on future earnings and margin assumptions, yet the current P/E of 18.5x sits above the estimated fair ratio of 14.8x, the North American insurance average of 11.3x and even the peer average of 18x. That kind of premium can signal quality, or just valuation risk. Which side do you think it belongs on?
If you want a clearer handle on how that P/E gap could close over time, it is worth digging into the detailed breakdown behind this ratio-focused view, including how sensitive it is to earnings and sentiment shifts, in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed views like these only matter if they shape your own process, so move quickly from headline takeaways to the underlying numbers and decide where you stand. To weigh both the concerns and the brighter spots in Sun Life Financial's profile, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Sun Life Financial?
Do not stop your research with Sun Life Financial. Fresh ideas often come from scanning other corners of the market that match your goals and risk comfort.
- Target higher income potential by reviewing dividend payers screened as 3 dividend fortresses for reliability and yield support.
- Hunt for mispriced opportunities with the 10 high quality undiscovered gems that filters for quality fundamentals hiding outside the usual headlines.
- Prioritise resilience by using the list of solid balance sheet and fundamentals (7 results) to focus on companies with financial strength that can handle tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com