


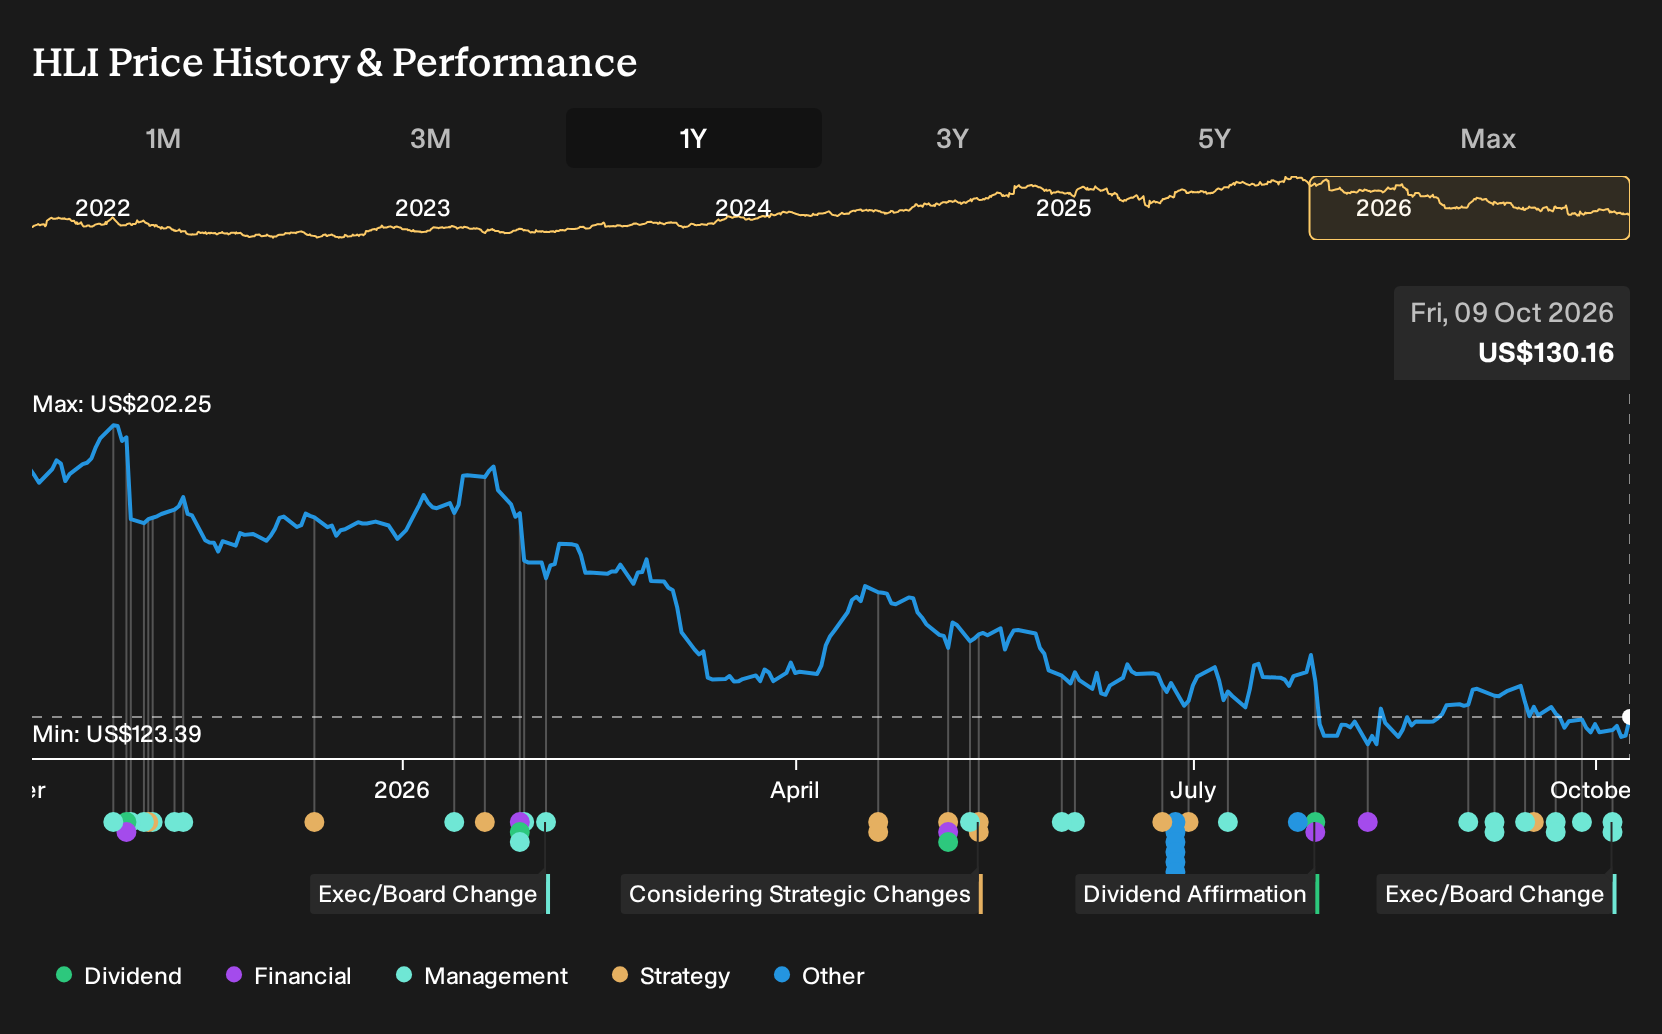
Investors who held Houlihan Lokey over the past year are down 30.8%, including dividends. If you had bought after the October 2025 bullish case that assumed 12.5% annual revenue growth, a profit margin stepping up to 18.5% and a 28.9x P/E in roughly three years, the slide since then feels jarring. Which of those specific expectations about deal activity, margins or valuation multiples did reality challenge, without necessarily overturning the whole advisory expansion story?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
If the move has made Houlihan Lokey harder to judge, start where the gap is still open and scan 29 high quality undervalued stocks.
The Argument Investors Had To Weigh On Houlihan Lokey
The shares cost US$190 at the start of the period, and Houlihan Lokey sat between two sharply different stories that both sounded reasonable on their own terms.
On the bullish side, the Simply Wall St Narrative put Fair Value at US$208, about 9% above the start price. This view was built on 12.5% annual revenue growth and profit margins stepping up to 18.5% within roughly three years.
The bearish view pointed to a Fair Value of US$166, about 13% below the same price. This argument suggested that rapid advances in AI could slowly commoditise advisory work and pressure long term fee levels and net margins.
What The Results Put To The Test For Houlihan Lokey
The clearest development was Houlihan Lokey agreeing to buy Intrepid Financial Partners, adding 34 energy specialists and supporting the expansion story from the bullish case. At the same time, Q1 2027 results showed revenue falling to US$511 million and net income slipping to US$78 million, with net margin easing to 15.3%. The evidence cut both ways.
The lesson is simple. When a thesis leans on rising profitability, it is important to keep checking reported net margin against the forecast step up, particularly after acquisitions and periods of rapid hiring.
What Houlihan Lokey's Lower Price Now Asks You To Believe
With Houlihan Lokey now trading at US$130, this Narrative’s Fair Value sits above the current price and leans on a business mix that ties mid market M&A, restructuring and Capital Solutions more tightly together.
The key assumption to test is whether record Corporate Finance pipelines and Capital Solutions activity can translate into enough completed higher fee deals to outrun rising costs.
"The main thing that has to go right is that Houlihan Lokey converts its record Corporate Finance pipelines and growing Capital Solutions and secondaries activity into completed higher fee transactions at a pace that outstrips rising non compensation costs and ongoing investment in technology and data."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking Beyond Houlihan Lokey
When you study Houlihan Lokey, you are really studying deal mechanics. Advisory firms live on transaction pipelines, fees and careful risk control.
Step one away and a different need appears. Those deals, once closed, often reshape how clients move and hold money.
Another business focuses squarely on that movement. It runs a technology platform that lets people and merchants send, receive and store funds digitally.
Instead of advising on transactions, it earns by processing them. That creates a different question for you.
How might a cash generating payments specialist evolve as finance keeps shifting online?
One Narrative has already put a figure on it. → Uncover the company trading 32% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com