


- Kratos Defense & Security Solutions and Airbus recently completed the first European flight of the U740 Valkyrie uncrewed combat aircraft, validating rocket-assisted take-off, maneuvering and in-flight mission adjustments as they work toward a Collaborative Combat Aircraft for European forces.
- This successful test gives Kratos a concrete proof point that its Valkyrie platform is maturing toward operational use, which matters for defense customers assessing long-term procurement, production ramp timing and the firm’s role in future unmanned combat fleets.
- We will now look at how this European U740 Valkyrie test flight could reshape Kratos Defense & Security Solutions' investment narrative.
Kratos Defense & Security Solutions Investment Narrative Recap
To own Kratos Defense & Security Solutions, you need to believe the business can turn its unmanned systems, satellite software and C5ISR exposure into durable programs, not just one off wins. The recent European Valkyrie flight and 5G NTN work speak to that ambition but do not remove the near term pressure from heavy R&D, facility build out and tight free cash flow.
The key short term catalyst remains proof that these investments convert into sizable, funded production contracts that support better margins and cash generation. The biggest risk stays the same. Kratos is spending ahead of awards, relies on concentrated government budgets and critical suppliers, so any contract delay or cost spike could hit earnings quality.
The 5G NR Non Terrestrial Network trial using Kratos’ OpenSpace platform looks most relevant to the Valkyrie story because it underlines how the company is tying airborne assets to software defined, multi vendor networks. For you as a shareholder, the interest is less about one demo and more about whether OpenSpace becomes embedded in future satellite and defense communications programs.
If OpenSpace moves from trials with partners like KT SAT into repeat contracts, it could support the multi domain modernization catalyst that analysts highlight and help diversify beyond pure drone production. Execution risk is real. Kratos still needs to manage supplier concentration, ongoing CapEx and working capital while scaling both Valkyrie and OpenSpace without eroding already thin 2% net margins.
Kratos Defense & Security Solutions' current analyst narrative points to US$3.0b in revenue and US$188.7m in earnings by 2029. That profile assumes 24.7% yearly revenue growth and an earnings increase of about US$157.8m from US$30.9m today.
Uncover how Kratos Defense & Security Solutions' fair value indicates a 141% potential upside to its current price before the market closes that gap.
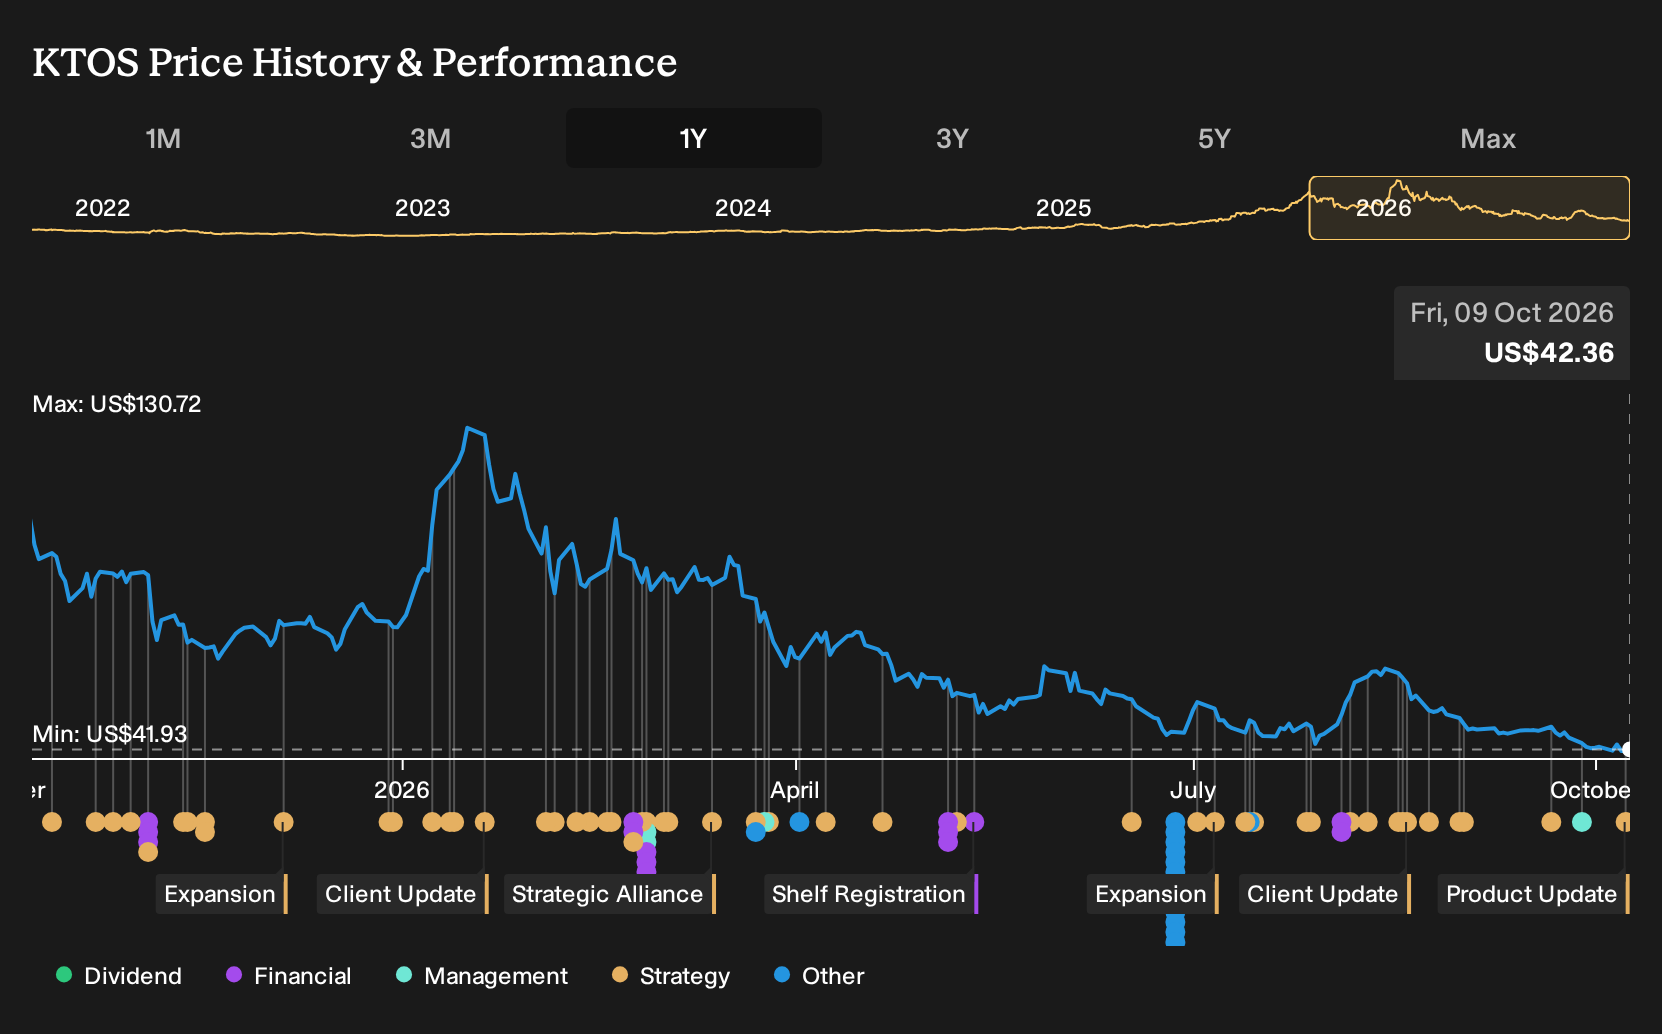
Exploring Other Perspectives
One bullish twist on the Kratos Defense & Security Solutions story focuses on hypersonic and engine scale rather than drones. The most optimistic analysts were already penciling in US$3.4b of revenue and US$274.3m of earnings by 2029 before this Valkyrie and OpenSpace news. You can treat those projections as one possible path and compare them with your own view.
Explore 5 other Kratos Defense & Security Solutions fair value estimates, including one that suggests as much as 254% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Kratos Defense & Security Solutions research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Kratos Defense & Security Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kratos Defense & Security Solutions' overall financial health at a glance.
Looking For More Investment Ideas Beyond Kratos Defense & Security Solutions?
If the Kratos Defense & Security Solutions story has you thinking about where else advanced defense and infrastructure themes might show up in your portfolio, it can help to scan a broader universe of stocks with similar financial traits. The Simply Wall St Screener lets you filter by quality, balance sheet strength and income profile so you are not just relying on headlines or hype.
- For investors who want growth potential without ignoring financial discipline, check out a curated 20 high quality undiscovered gems that may not yet be on most radars but already show solid fundamentals.
- If capital preservation sits high on your priority list, focus on resilience first and return second by scanning a 31 resilient stocks with low risk scores that screens for businesses with sturdier risk profiles.
- When balance sheet strength is non negotiable, start with a list of solid balance sheet and fundamentals (25 results) that filters for companies carrying less debt and healthier financial buffers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com