


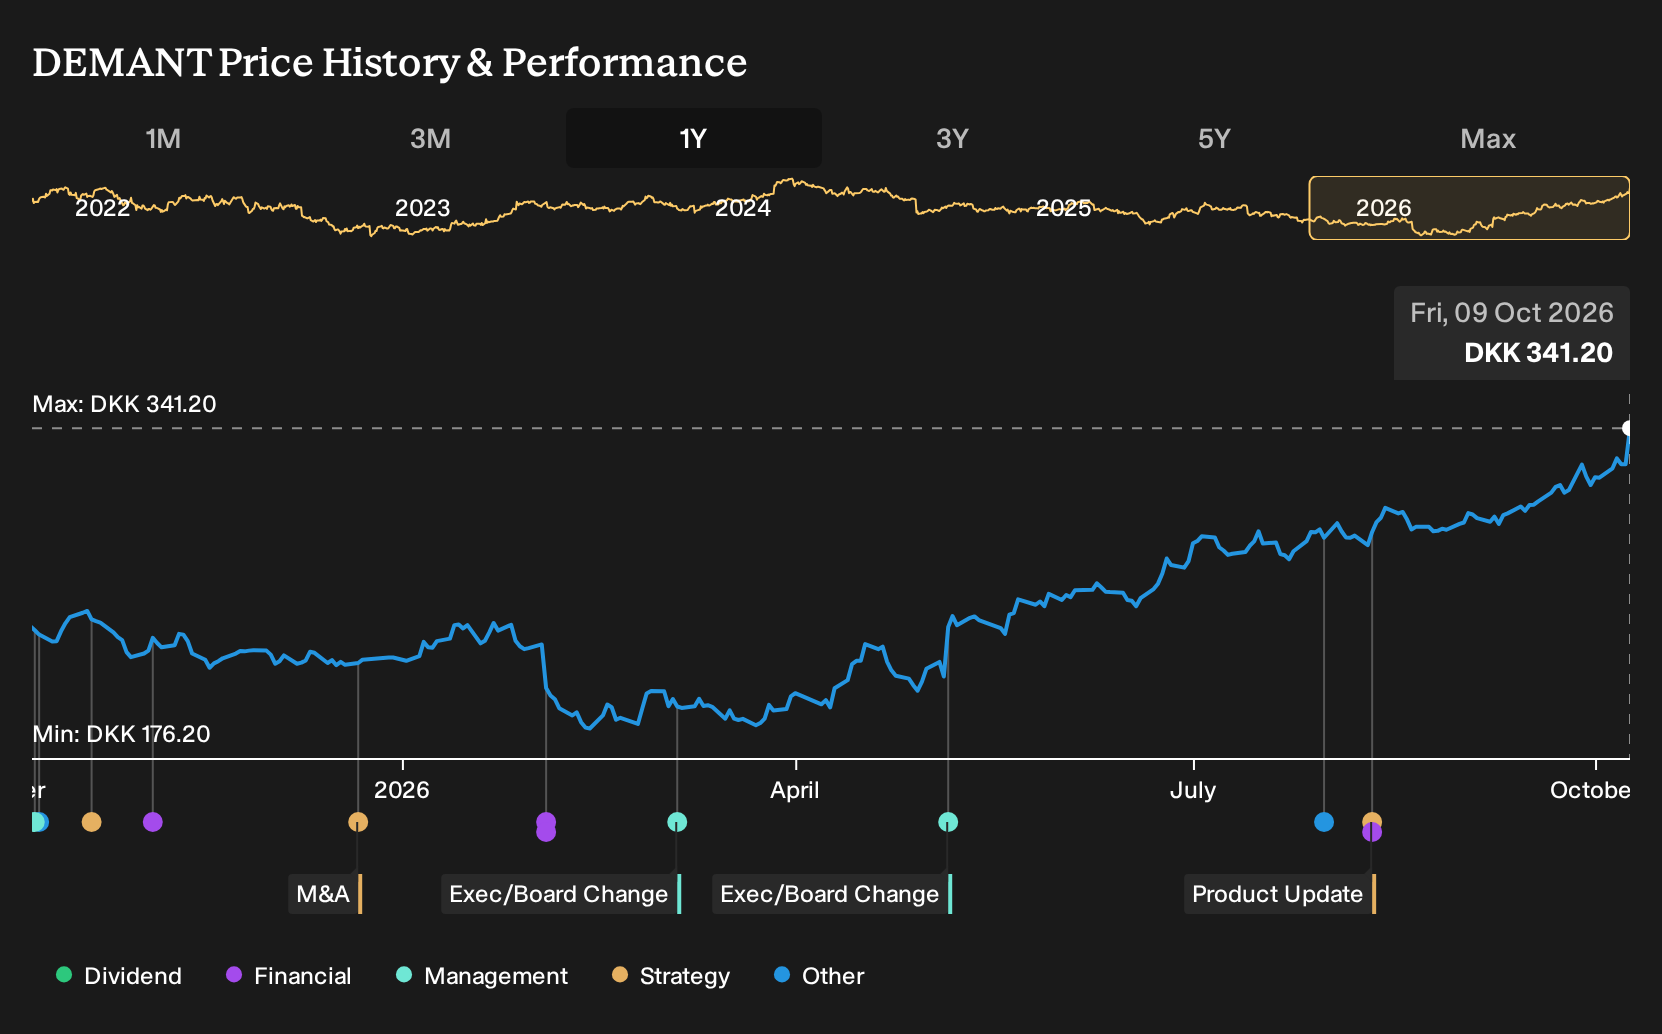
- Demant recently reported that its new flagship hearing aid, Oticon Reveal, has been very well received and that this product performance has led management to raise growth and earnings forecasts, supported by strong demand in the US.
- The decision to lift guidance on the back of Oticon Reveal suggests that product execution and reception in key markets are currently central to Demant's operating outlook.
- This article will examine how Demant's investment narrative is affected by the raised growth and earnings forecasts tied to Oticon Reveal.
Scan how other hearing care and medtech players are priced for product-driven growth by checking the hand picked 618 high quality undiscovered gems alongside Demant.
Demant Investment Narrative Recap
To own Demant, you need to believe in a hearing healthcare group that can turn product launches and retail reach into steadier earnings, despite choppy demand and pressure on margins. Oticon Reveal being well received and tied to raised growth and earnings forecasts supports that thesis, because it points to healthy US demand and product execution that currently appears to be working.
The key short term catalyst is whether Oticon Reveal can sustain momentum without sacrificing pricing or mix. The biggest immediate risk is that macro cautiousness, competition and a tilt toward lower priced markets keep weighing on margins, leaving Demant carrying high debt while net profit margins, already at 9.8%, stay under pressure.
Recent guidance tied to Oticon Reveal is the clearest update for this catalyst. Management has lifted growth and earnings forecasts on the back of strong reception and US demand. That puts product cycle execution at the forefront. The thesis depends less on broad hearing health themes and more on whether this flagship can support pricing, volumes and operating leverage.
That same announcement also reshapes how you think about risk. A successful flagship can partially offset pressures from lower average selling prices in some geographies and the strain from competition in retail channels. It does not remove the structural issues around high leverage and weaker diagnostic demand, so the story still hinges on disciplined capital allocation and careful promotion spend as Demant pushes Oticon Reveal through its network.
Demant's current analyst story points to DKK 30.7b in revenue and DKK 3.9b in earnings by 2029, based on expected yearly top line growth of 7.7%. That earnings path implies an increase of about DKK 1.5b from the DKK 2.4b reported today.
Uncover why Demant's fair value indicates a 9% potential downside to its current price, a premium that may not be sustained.
Exploring Other Perspectives
Some of the most optimistic analysts focus on a different catalyst for Demant. They lean on faster market share gains and a stronger retail footprint, and before this Oticon Reveal news they were already modelling DKK 32.4b of revenue and DKK 4.5b of earnings by 2029. That is far above consensus. It shows how widely views can differ. Use this new product update as a reason to compare those upbeat assumptions with your own and see which narrative feels closer to how you think the story may evolve.
Explore another Demant fair value estimate, including one that suggests as much as 61% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Demant research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Demant. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Demant's overall financial health at a glance.
Looking for more investment ideas beyond Demant?
Once you have a view on Demant, it can help to place that opinion alongside other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you filter for very specific traits so you can build a broader watchlist that matches how you like to invest.
- If you want potential upside with stronger fundamentals than the typical small-cap, scan the 122 elite penny stocks with strong financials that combine higher risk with more robust financial profiles.
- For investors who care most about quality and price discipline, focus on companies in the 179 high quality undervalued stocks that pair solid balance sheets with cash generation at valuations that may look more reasonable.
- If resilience matters more than excitement for your portfolio, concentrate on the 226 resilient stocks with low risk scores to find businesses that screen well on financial stability and risk metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com