


Evercore (EVR) has drawn fresh attention after appointing Philip von Malsen-Plessen as a senior managing director in its investment banking arm in Frankfurt. The move is aimed at deepening its DACH-region advisory footprint.
Recent activity around Evercore includes upcoming Evercore ISI conferences in automation tech and storage, yet the share price tells a cooler story. The stock is up 1.92% on a 1 day share price return and 2.45% over 7 days, but down 20.56% on a 90 day share price return and 22.61% year to date. At the same time, the 3 year total shareholder return of 113.06% and 5 year total shareholder return of 90.02% point to much stronger longer term wealth creation than the recent pullback suggests.
Scan how Evercore fits alongside other potential opportunities by reviewing the hand picked 20 high quality undiscovered gems that may be flying under most investors' radar.
Evercore is hiring heavyweight talent in Europe while the share price has pulled back sharply this year. Does that mix argue for stepping in now, or does patience for a better entry still look wiser as the valuation details come into focus?
Most Popular Narrative: 23% Undervalued
Evercore's most followed valuation narrative points to a fair value of $354.70 versus the recent close of $271.86. This frames the latest hiring moves and advisory build out as happening against a discounted share price.
The increasing role of non-M&A areas such as Private Capital Advisory, Private Funds Group, restructuring and liability management, ECM, equities and wealth management, which together provided more than 40% of revenues over the last 12 months, gives Evercore more ways to monetize client activity and can smooth revenue and earnings across deal cycles.
See why 19 investors see Evercore as 23% undervalued.
Result: Fair Value of $354.70 (UNDERVALUED)
Still, if Evercore's higher non compensation spending persists while advisory and non M&A fees slow, the current undervaluation story could quickly lose momentum.
Find out about the key risks to this Evercore narrative.
Another View: Evercore Through The P/E Lens
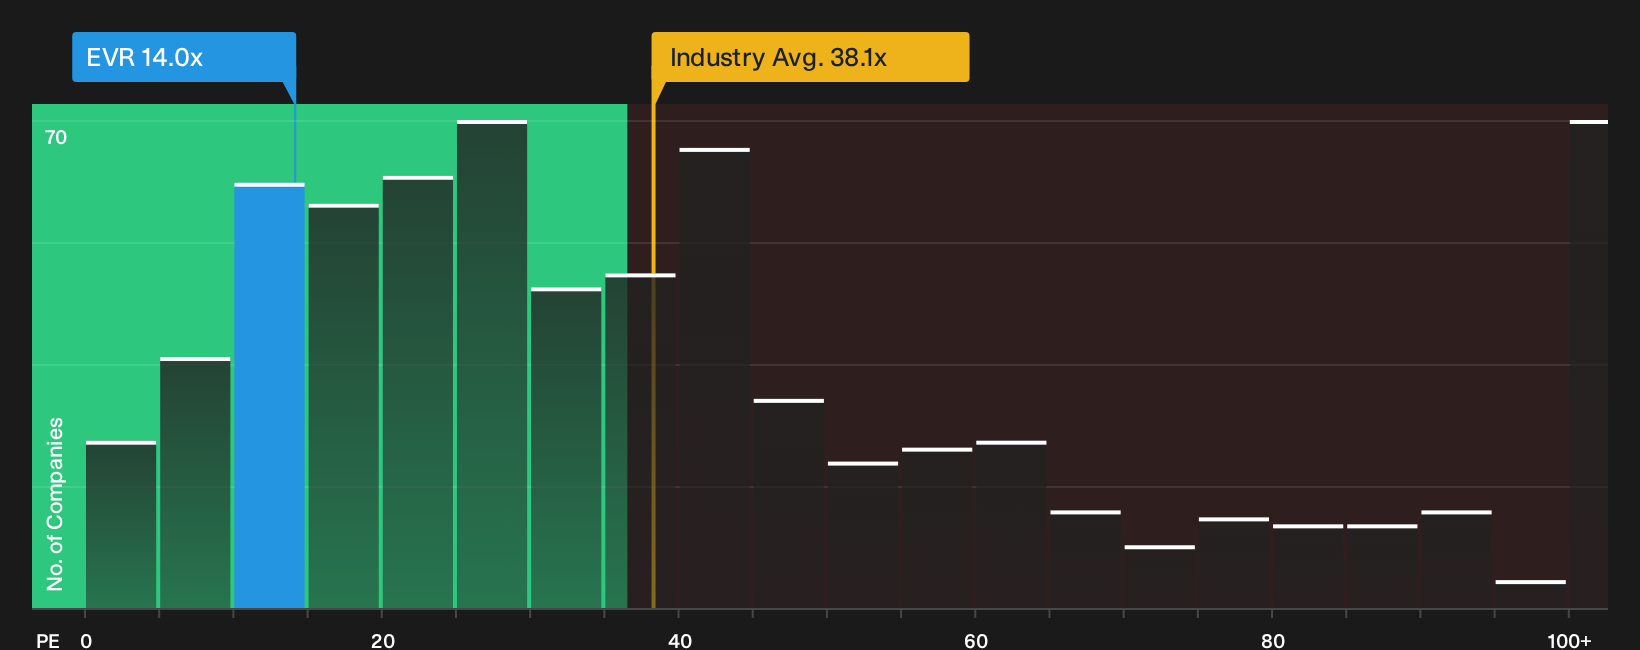
Evercore looks cheap on one scoreboard and richer on another. The shares trade on roughly 14x earnings, which is far below the US Capital Markets industry average of 38.1x and the peer average of 26.7x. Yet that same multiple sits above the estimated fair ratio of 12x, which hints at some valuation risk if expectations cool.
Investors weighing this mix of discount versus peers and premium to the fair ratio may want to see what the detailed breakdown implies for upside and downside before leaning too hard on the undervaluation story See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling mixed about Evercore after all this
Let the numbers speak for themselves and move quickly from the headline story to your own judgment by starting with the 3 key rewards.
Looking for more Evercore style investment ideas?
If Evercore has your attention, do not stop here. Broaden your watchlist with a few focused sets of stocks that fit clear, disciplined criteria.
- Target underpriced quality by scanning companies that combine strong fundamentals with appealing valuations using the 29 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on firms that carry sturdier finances through the list of solid balance sheet and fundamentals (25 results).
- Sharpen your edge in overlooked opportunities by tracking tomorrow's potential leaders with the 12 elite penny stocks with strong financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com